Stock Pitch - finnCap (LON:FCAP)
finnCap was pitched to the Stockopedia Investment Club (SIC) on 10th August 2021 at a share price of 33.5p.

Since the company’s IPO on the Alternative Investment Market (AIM) in December 2018, it has succeeded in aggressively growing its operations in the brokerage services and investment advisory industry, and taking market share. Despite its impressive growth over the last few years, the company still trades on a trailing price to earnings ratio of just 6.7x and hands out 4.69% annually to its shareholders in the form of dividends.
This raises some question marks around the low valuation, especially given the company’s historical growth record and future ambitions.
It seems that the market doesn’t believe that finnCap’s current tailwinds from the heightened levels of capital markets activity being seen around the world is sustainable. IPOs, Mergers & Acquisitions, Fundraisings, Investment & Debt advisory have all witnessed a tremendous rebound in activity since the pandemic lows of March 2020, and eventually appetite for these will somewhat subside.
After a strong start to the current year (FY 2022), it appears as though little of the current upside from the strong macro backdrop is priced in. Could finnCap’s share price rerate on the back of this, or is the market right to be wary of the cyclical nature of the company’s operations?
Bull points: Significant activity in capital markets (IPOs, placings, M&A, advisory), impressive growth and taking market share, excellent financial position to fund both organic & acquisitive growth, whilst simultaneously returning capital to its shareholders.
Bear points: Highly reliant on current market conditions continuing, results may have already peaked in the current cycle, poor share price momentum after what appears to be a case of ‘buy on the rumour sell on the news’.
Profile
About the stock:
AIM-listed finnCap (LON:FCAP) operates under the Financials sector, in the Investment Banking & Investment Services industry. The group is based in London, and currently focuses on providing most of its services in its core UK markets, but is growing its operations internationally.
At the current share price of 32p, the current market capitalisation is around £58.5 million. The shares are relatively illiquid, with an Exchange Market Size of 8k.
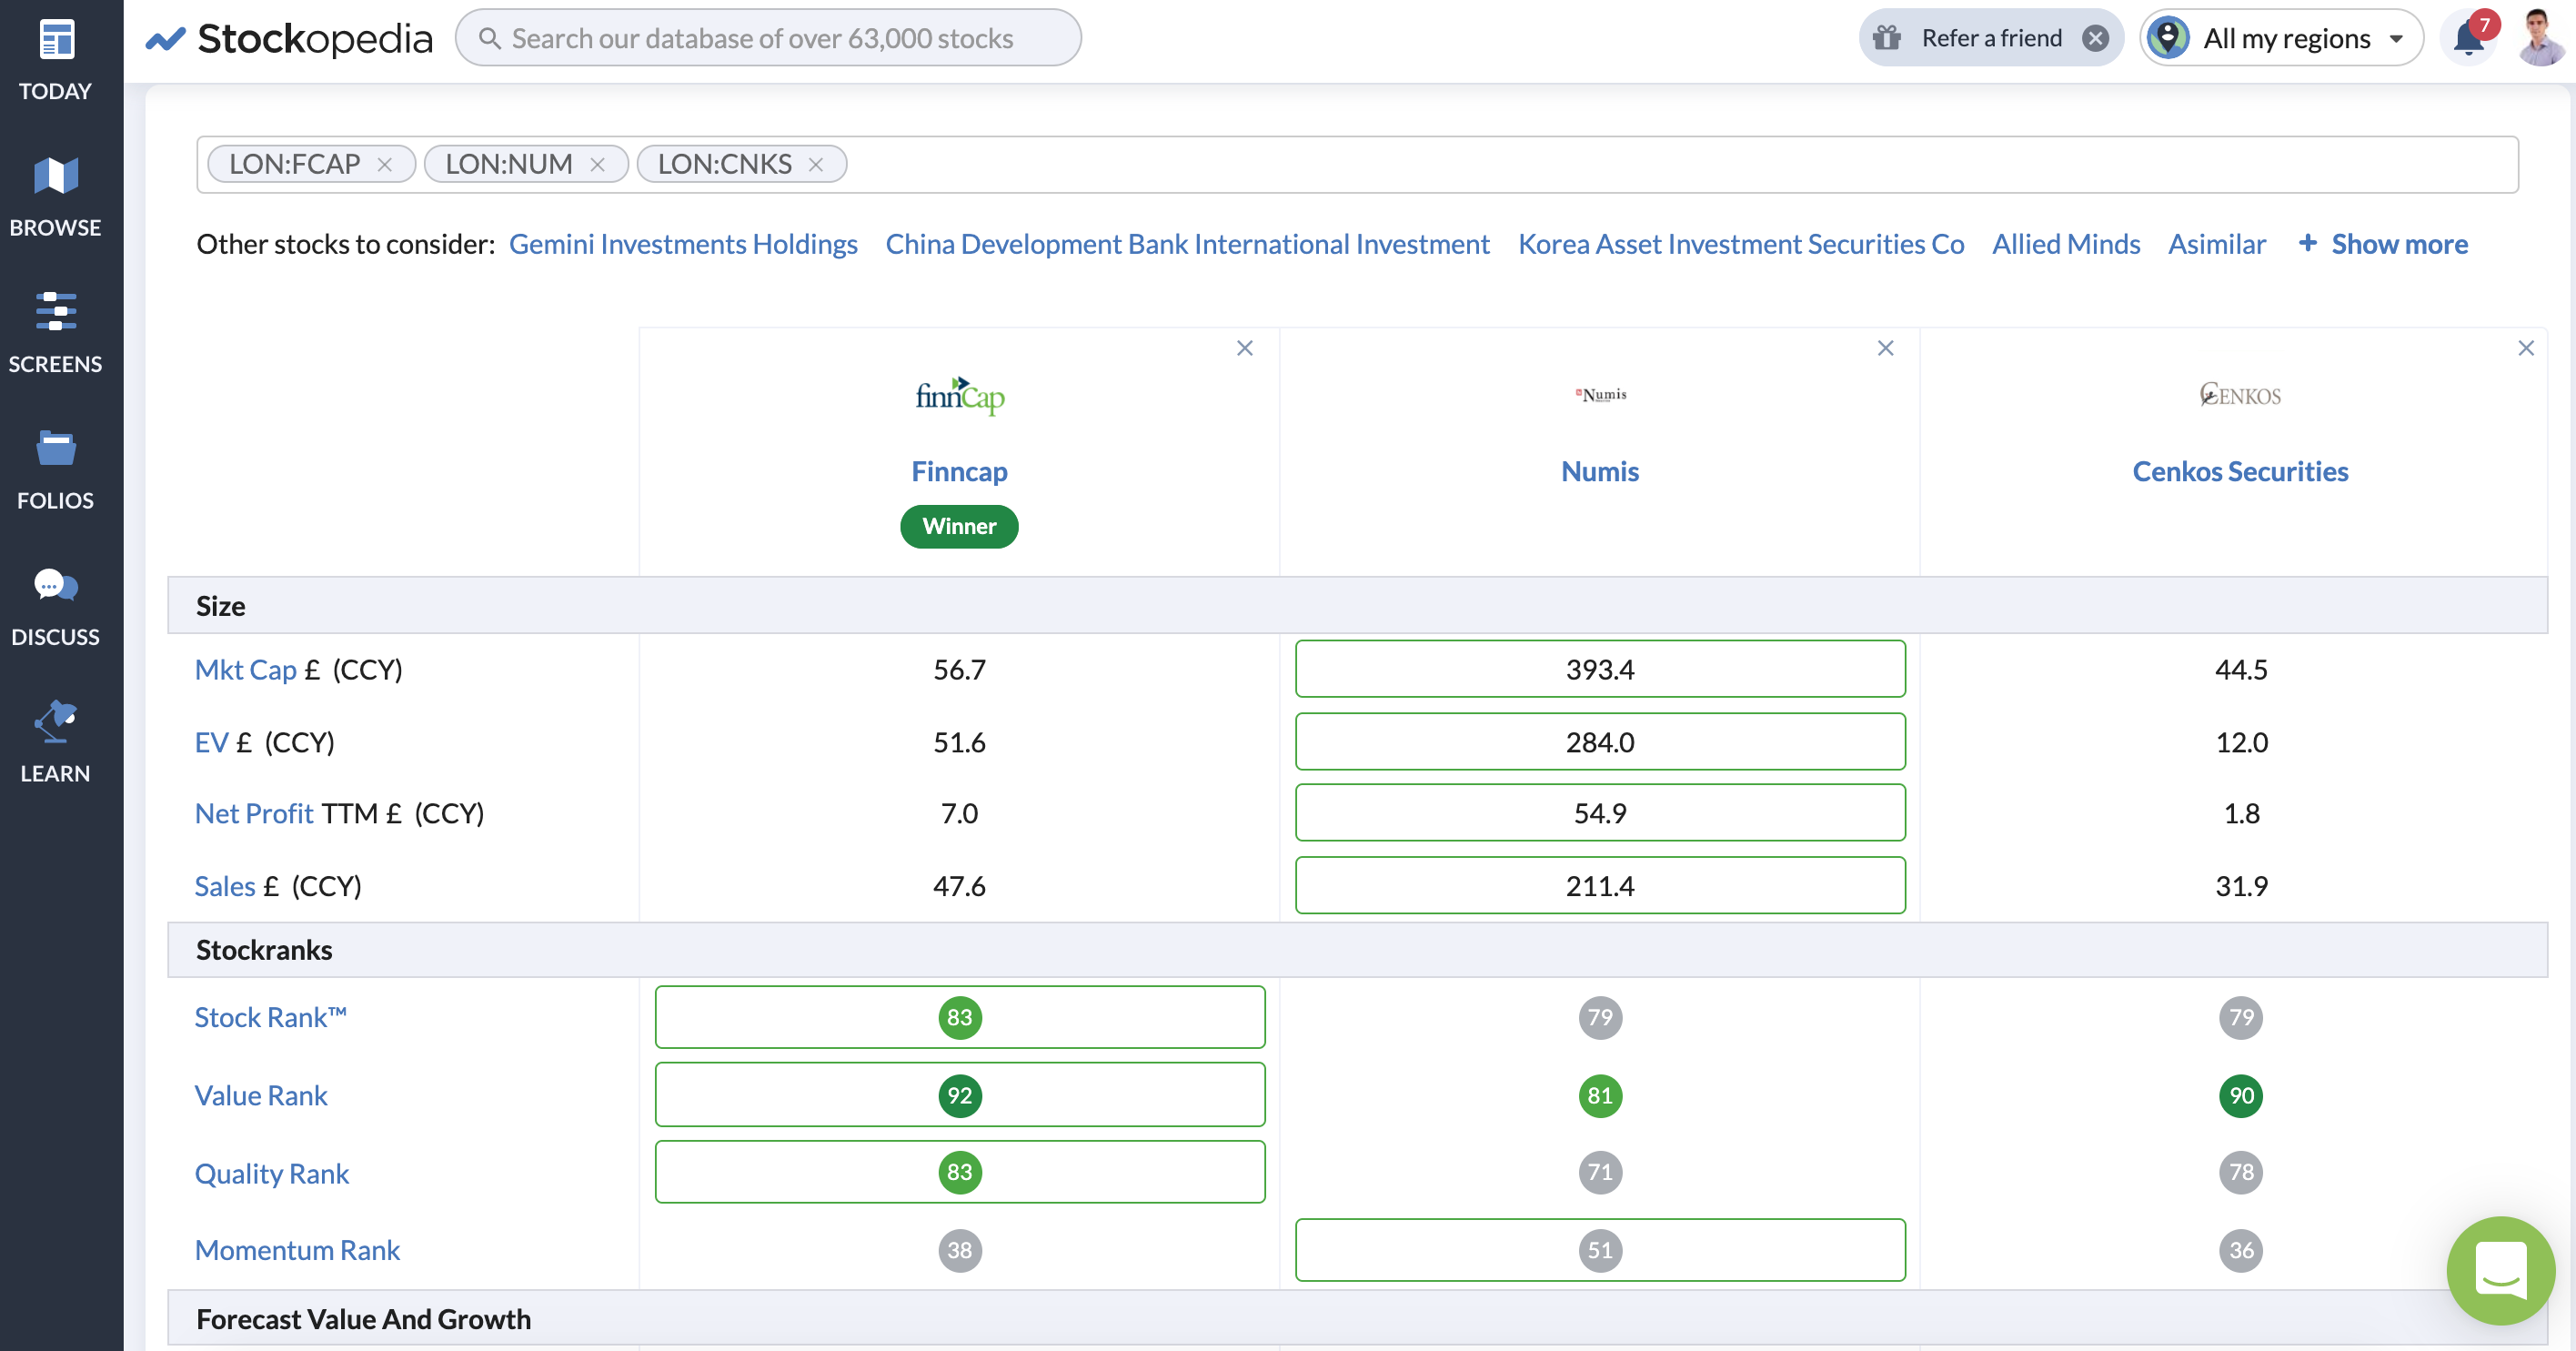
According to Stockopedia’s classification systems, finnCap is currently an Adventurous Small Cap Contrarian stock. The current trailing 12m price to earnings ratio is 6.7x, dividend yield 4.69%, and the StockRank sits at a commendable 83.
The Quality and Value Ranks stand out here, at 83 and 92 respectively. finnCap also qualifies for the T Rowe Price and Philip Fisher growth screens, due to its strong historical growth rates.
Business & Model
What is the company history & what does it do?
A relative newcomer to the brokerage & investment advisory world, finnCap was founded by current CEO, Sam Smith, in 2007. The company was formed from the partial buyout of the corporate finance and broking business of private client stockbroker, JM Finn & Co Limited.
In 2018, the company acquired Cavendish Corporate Finance LLP, enabling the company to develop its M&A activities.
Initially focused on raising capital for micro-cap companies, finnCap has risen to prominence in recent years, as a leader in the small cap broking world. It has been able to do this through its vision on putting clients first and doing things the right way .
finnCap describes itself as a specialist in advising ambitious growth companies, providing them with access to capital and promoting their stories across private & public markets. The company has been expanding its services in recent years, to provide to its clients across a wider range of sectors.
What is the business model? How does it make money?
The two principal divisions of finnCap Group are finnCap Capital Markets and finnCap Cavendish. The finnCap Capital Markets division looks after everything from sponsor, nomad & broking services to IPOs, fundraisings, strategic and debt Advisory. Furthermore, the Capital Markets division is also responsible for all equity research, sales & execution (market making) and finnCap analytics, which is a new subdivision of the company focused on providing data analysis to larger hedge funds and institutional investors.
finnCap Cavendish, formed from the acquisition of Cavendish Corporate Finance LLP in 2018, is one of the UK’s leading mid-market M&A advisers. Through the company’s partnership with Oaklins, it has a global presence in over 45 countries, across the US, Asia and Europe. The division’s unrivalled expertise has seen it successfully complete over 1700 deals globally over the past 5 years.

Market & Competition
What is the state & size of the company's market?
The financials and investment services market is one of the largest in the world. In the UK alone, the financial services market generated £76 billion in 2020, the equivalent to 10.1% of the total tax revenue earned by the government (according to the City of London).
The brokerage services & investment advisory market might be more niche, but there is still plenty of activity within this group. The latter half of 2020, and this year so far have seen a remarkable uptick in brokerage service & investment advisory activity. The market conditions are favourable for those operating in this subset of the financial services industry, and plenty of listed companies in this space have posted promising results over the last year.
Who are the company's key competitors?
Numis & Cenkos Securities are finnCap's main competitors, providing much of the same services to mid/small cap growth orientated companies. There are several other private companies that offer competing services, such as Peel Hunt & Panmure Gordon. Numis is the largest of the 3 listed companies, but finnCap is growing at a much faster rate than its peers. See finnCap compared to its peers below (the Growth Rank also currently stands at 87).
What is the company's strategy?
The company has a clearly defined strategy to provide 'the best advice for each business requirement to fuel faster growth, build value and we are trusted to deliver. We believe this is the reason we are the largest Nomad and AIM company financial adviser and No. 1 broker on AIM.'
Testament to its AIM reputation are the recent deals that the company has pulled off, which include: IPO and £25m fundraise for Poolbeg Pharma PLC, Revolution Bars Group £21m fundraising, Ideagen £75m debt refinancing and the Best of the Best £60m placing. A full list of all the company’s transactions can be seen here.
How does it derive its competitive advantage (if any)?
Across the company’s site, and in its management releases, finnCap relentlessly reiterates its message of putting clients first and focus on its core AIM market. It could be argued that the relationships that it has developed by doing so give it a cutting edge over its rivals. The management are very ambitious with a strong-desire to be the best in class in their home markets.
Is the competitive advantage durable and is there any evidence of one in the financials?
From the company’s quality metrics, we can see some evidence of the competitive advantage. The Return on Capital and Return on Equity are in the top quartile of the industry, and these have remained impressively stable over the past 5 years (with the exception of 2020). It may be that the company’s focus on putting clients first enables them to charge out higher rates, due to clients placing a higher level of value on their services.

Financials & Ownership
What is the record of revenue growth & profitability?
Revenue growth has been exceptional over the past 6 years, growing from £18m in FY2016 to £47.6m in FY2021. Although revenue forecasts appear to have peaked, current forecasts seem quite conservative, which we’ll get into later on.

Profits have also grown in recent years, albeit at a lesser rate until recently. The last year has seen profits surge to over £7m, representing a huge rise on prior years.
What is the state of the balance sheet?
The balance sheet is in good shape at the moment, even after heavy investment into growing operations organically over the past year. Cash currently sits at over £20.4 million, although this does reduce to a net cash position of just over £5 million if you take the company’s capital lease obligations of £15m into account.

Is there evidence of historic share dilution or buy backs?
There’s no real evidence of share dilution in recent years, and with the company’s current cash position, it is unlikely that there will be further dilution (unless an acquisition takes place).
What is the ownership structure of the company and do management have stakes?
Management and employees do have significant stakes in the company, as well as some prominent private investors and venture capitalists. Baron Leigh, Sam Smith, Geoff Nash, Mark Tubby, are all management or board members with stakes of 3% or more.
(Source: finnCap.com)

Valuation
How does the relative valuation compare versus industry and sector?
finnCap is currently trading on a TTM P/E of 6.7, with a PEG less than 0.1 (a number so low it can’t be calculated on the StockReport). The current dividend yield is the best amongst its direct rivals and its overall Value Rank is a cool 92.
The compelling valuation and extraordinarily high growth levels is what differentiates the company from its peers. finnCap ranks the best across the vast majority of these metrics, and seems comparatively undervalued.

Trends & Catalyst
Are there any significant macro trends that the business is benefiting from?
Perhaps the main argument for purchasing the shares right now is the overall macro tailwinds that we are witnessing. Capital markets are buoyant, IPO activity is reaching levels not seen for over a decade and M&A activity is rife.
Companies of all sizes are looking to capital markets to raise funds and take advantage of current market conditions. Whilst the central banks continue to prop up the global economy, individuals will continue to look to the stock markets and other asset classes for success, a trend which finnCap will only benefit from in the immediate term.
Are there any catalysts that could drive a rerating in the medium term?
finnCap’s half-year results are typically released in November, and having started the year strong, the company could generate some strong interest when it publishes its results.
Any surprise acquisitions, further encouraging trading updates or updated broker notes could also provide some catalysts over the medium term.
Risks, Threats & Hurdles
What are the biggest risks, threats or hurdles that the business may face?
Competitive Risk - Whilst one of the larger players, finnCap still faces risks from smaller brokerage & investment advisors who may be more willing to undercut their offering. Equally, a larger player, such as Numis may decide to focus more of its efforts on small caps, which could reduce finnCap's market share.
Market Risk - Perhaps the main risk the company faces at this time is a change in market conditions. We have witnessed a remarkable post-pandemic recovery across markets, which makes March 2020 feel like a small blip. There are euphoric conditions across many financial markets and this is typically a signal that we are reaching the top. Should the post-pandemic recovery falter, or an unforeseen economic shock hit, then finnCap might be one of the first companies to suffer.
Expansion Risk - This could also fall under operational and reputational risk. finnCap's ambitions to become the best in class has seen it recruit and invest heavily into its operations over the last year. The company has a great track record of execution, so there could be some friction as the company expands into new sectors and domains.
Recent Trading & News
Summarise the most recent announcements, news, and trading statements and market reaction to them?
Director Dealing - Exercise option by the executive director of the Company, Tom Hayward, for over 600,000 ordinary shares. Sold 325,000 to fund the exercise price and to pay tax arising from the exercise and transferred the rest to ISA and SIPP.
FY 2021 Results - Record results were published on 1st July 2021 for the company’s preliminary FY2021.
Highlights included the following:
- Total income up 84% to £47.6m,
- finnCap Capital Markets revenue up 84% to £34.5m; finnCap Cavendish revenue up 66% to £12.1m,
- Adjusted PBT up from £1.6m to £9.6m; PBT up from £1.2m to £8.4m,
- Adjusted EPS up from 0.8p to 4.80p; basic EPS up from 0.49p to 4.41p,
- Total dividends 1.5p,
- Cash of £20.4m at 31 May, down to £17.2m at 29 June 2021.
Paul Scott provided an interesting analysis of the results in the Small Cap Value Report, which you can see here.
Sentiment
What do the brokers currently think and are they upgrading estimates?
finnCap has received several upgrades over the past year. Progressive Equity Research commented the following after finnCap's FY2021 results:
'Perhaps the most notable points that the FY 2021 numbers underline are the benefits to the Group of its diversified offering to clients and its investment in evolving its capacity and sectoral capabilities. Coupled with a robust balance sheet, finnCap appears, to us, to be very well positioned to cope with relatively uncertain markets and to act on further growth opportunities – both organic and acquisitive.'
What is private investor sentiment at the moment?
Whilst private investors are disappointed with the overall market reaction to the full year results, there are plenty that have highlighted the value opportunity, with the stock priced extremely cheaply based on its historical & potential growth and relative to its peers.
What would the person selling to us be thinking and who are they?
Most likely to be individuals selling out after the preliminary FY2021 results. From a technical perspective, it appears that the stock is now oversold. However, with the momentum currently shot, investors might seek better opportunities elsewhere.
Conclusion
Due to our maximum position size of 16 in the Stockopedia Investment Club, when pitching finnCap a stock had to be selected to be sold. After a stellar run with Ergomed, this was selected as the candidate to sell as its StockRank had dropped close to our cut-off point of 50.
It was a close call in the end, but the club decided to purchase shares in finnCap and sell Ergomed. The shares in finnCap were purchased at a price of 32.95p on 16th August 2021.

From the results we can see some hesitation around purchasing finnCap, despite the attractive valuation and growth prospects. Was the club right to purchase these shares that appear so undervalued, or is this simply a period of supernormal profits for the company on the back of unsustainable market conditions?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

10 comments
Mark Simpson talks about why he invested in Finncap on this weeks Capital Employed Podcast, if it's of interest to shareholders -
https://podcasts.google.com/fe...
I note that Ergomed (LON:ERGO) share price has shot up about 20% since 16th August, also the Stockrank has gone up also, not sure why.
What did the club sell them for?
Interim results are out on 28th September.
Finncap A very good analysis but the wrong conclusion. Terry Smith has made a great success out of clearly defining what are not investment grade businesses. The list is not endless and includes airlines and low margin activities such as supermarkets. It concentrates the mind wonderfully to the areas most likely to increase returns to investors. Corporate fiance is not such an area it is a highly leveraged bet on the market either a feast or a famine. Sitting between the investors and his return is a capricious talent poo l with a voracious appetite. Not for me
A good analysis, but one thing not covered is the technical aspect of the price. It is bouncing along the 200 DMA and this would deter my decision in voting in favour of selection. I would want to see some positive upturn in the short term DMAs before considering a purchase.
Excellent write up Keelan. The SIC stock pitches are another great addition to stockopedia. I really enjoy reading and learning how you analyse a stock. Very helpful to an amateur investor like myself. Keep up the good work.
Thanks, Tom
"The Quality and Value Ranks stand out here, at 83 and 92 respectively."
... and their results are showing momentum too, all of which accounts for the relatively high stock rank. The problem is, this is all based on 1 year's (peak?) results which are unrepresentative of performance across the cycle. The investment club's rules for both buying and selling are based on stockranks and in general this is a good thing, but when it comes to assessing something so cyclical as this, it is probably more misleading than helpful.
There is a market saying that the right time to buy cyclical stocks is when they look expensive, not when they look cheap. There is a lot to be said for that. Equally, it could be said that the time to buy is when margins and returns on capital are poor and the quality rank is on the floor.
A decision on whether to buy or sell finnCap should really be based on your view of where we are in the cycle, not where it sits in the stockranks. In truth, it probably matters little whether you choose finnCap, Numis or Cenkos. Whether the trade works or not depends little on the specific stock and much more on how the cycle plays out.
Having said that, all this depends a great deal on your intended holding period. If your intended holding period is only a year then what I've said is largely irrelevant. Stockranks work (on average) over 1 year, even taking in to account their limitations regarding cyclical stocks. But I get the sense in these stock pitch write ups (which are a great addition to the site) that you are assessing stocks as long term holdings. In that case, the cycle is the key thing, not the stockrank, and the investment club rules become a bit unhelpful.
I think the trailing P/E and historic divi yield is probably rather flattering as there was a lot of easy money made by brokers last year from capital raises. Looking ahead fees from M&A and IPOs may benefit from increasing activity but I prefer and hold Numis (LON:NUM) as the market leader. Catering to micro-caps is all very well but will these companies stay loyal to their broker as they grow larger and their requirements become more complex?
Hi Momoko,
Thank you for raising some interesting points.
The P/E and dividend yield remain around their current levels when calculated on a 12m forecast basis, given the current estimates for FY2022. Given the strong start to the year, the FY2022 figures (which are slightly below FY2021) might end up being revised upwards as well.
Choosing between Finncap (LON:FCAP), Numis (LON:NUM) and Cenkos Securities (LON:CNKS) wasn't a straightforward decision. Each company has its merits, and I believe that UK-focused brokerages & investment advisors are valued quite attractively across the board at the moment, especially given the current market backdrop.
In my opinion, finnCap's strong growth over the last few years, combined with its future ambitions gives it the best chances for sustained earnings growth and multiple expansion, but I do think Numis could do quite well too!
Kind regards,
Keelan
Hope you are right about Numis (LON:NUM) which I've held for a long time Keelan. I get the feeling my cash has been feeding its Directors all that time.
Silver
Hi Keelan,
Certainly there is no lack of choice in that section with many having high Stockopedia rankings, you could add Jarvis Securities (LON:JIM) and Premier Miton (LON:PMI) as well. I have been considering both Finncap (LON:FCAP) and Jarvis Securities (LON:JIM) recently.
I will have look into Numis (LON:NUM).