Stock Pitch - Integrated Diagnostics Holdings (LON:IDHC)

If you focus on the financial data alone, few listed companies can compete with the kind of consistent double digit growth rates and profit margins notched up by Integrated Diagnostics Holdings (LON:IDHC) - yet this company trades on just 13.8x forecast earnings and is expected to pay out a generous 5.7% dividend.

So why the modest valuation for what appears to be a growing, cash generative healthcare provider in expanding markets?
A part of the answer might be to do with those expanding markets - IDH operates in Egypt and across certain other North African countries. They come with increased opportunities, but also with increased risk. IDH is not your typical London-listed company.
Investors are wary of overseas listings and the group’s abrupt change of auditor only adds to that dubious impression.
But the growing disconnect between financial execution and valuation appears to present an opportunity to buy into a high quality operator exposed to structural growth markets. That’s if you can get over the overseas listing, jurisdiction risk, and abrupt change of auditor, of course. So is this company being unfairly shunned, or has it been left alone for good reason?
IDH was pitched to the Investment Club on July 13th at a share price of $1.19.

Bull points: Double digit top line and bottom line growth over many years; double digit returns on capital and profit margins; net cash with great cash conversion; structural growth drivers in growing, fragmented markets; dominant market position in Egypt with economies of scale and barriers to entry; accredited brands give it pricing power; capital-light expansion model.
Bear points: emerging market volatility and geography risk; short listed history and limited analyst coverage; recent abrupt change in auditor; temporary Covid boost to diagnostics trade; products and services could become lower margin and more commodity-like in future.
Profile
About the Stock:
Integrated Diagnostics Holdings (LON:IDHC) trades in the Healthcare segment as part of the Healthcare Providers & Services industry group.
It listed on the LSE Main Market in 2015 and listed in Egypt (EGX) in May, 2021. It is an Egyptian company with headquarters in Jersey and expanding operations in the Middle East and North Africa (MENA).
The market cap is around £513m, although shares are thinly traded and the spread varies.
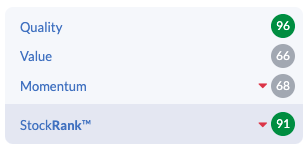
Stockopedia classifies IDH as an Adventurous Mid Cap Super Stock. The forecast PE ratio is 13.8x, the forecast dividend yield is 5.74%, and the StockRank is 92, with an eye-catching 96 Quality Rank.
About the Opportunity:
This is a quality / growth-at-a-reasonable-price (GARP) stock.
Quality: IDH has some market-leading quality scores, including a ROCE of 31.1% and an operating margin of 37.1%. Returns on capital are high and improving over time.

Along with a net cash position and solid financial health, these attributes earn the group its Quality Rank of 96.
GARP: Revenues, operating profit, and net profit have gone up every year for the past 5 years, all with compound annual growth rates in excess of 20%. A forecast PEG of 1.1x presumes quite modest earnings growth in FY22 - significantly below the five-year trend - on very little broker coverage.
Meanwhile the group shows no signs of slowing down: it is expanding into new markets, opening new branches, looking for acquisitions, and has just listed on EGX.
IDH passes 3 screens:
- Value Momentum Screen (momentum)
- Winning Growth & Income (income)
- Buffettology-esque Historical Growth Screen (quality)
Business & Model
What is the company history & what does it do?
IDH provides more than 2,000 high-quality medical diagnostic services operating across four key geographies. In order of revenue (as of the most recent trading update), these are:
- Egypt (81.5% of revenue),
- Jordan (16.8% of revenue),
- Nigeria (1.1% of revenue), and
- Sudan (0.6% of revenue)
History:
- 1979 - MK lab established in Cairo,
- 1990 - Al Borg medical lab in egypt founded (first to operate hub, spoke, spike model),
- 2008 - IDH established. Acquired 77% of Al Borg,
- Additional acquisitions in subsequent years, alongside steady branch openings,
- 2011 - Acquisitions take the company into Sudan and Jordan,
- 2012 - Buys out biggest competitor Al mokhtabar,
- 2013 - Establishes the largest automated lab in Egypt,
- 2015 - Lists on LSE (50% at $4.45 USD, market cap of $667.5m)
- 2018 - Establishes holding company, JV with man capital to buy biz in Nigeria. Launches radiology offering.
- 2020 - Grows through covid, with revenue from COVID tests offsetting a drop in demand for normal services
What is the business model? How does it make money?
IDH operates a ‘hub, spoke, and spike’ model.
Its Mega Lab - the diagnostic hub - is the largest automated lab in Egypt and is equipped with the latest technology to provide a full suite of diagnostic tests. Its scale allows for cost synergies on diagnostics kits, logistics, and quality control.
At present there are seven B Labs (the spokes), with more being added. These process routine tests on site. They are larger and have more capacity than the C Labs (the spikes).
C Labs are collection centres and conduct basic tests. They require little capital to open and so are an effective way for IDH to expand into fragmented markets. They only take 1-2 months to set up and 4-6 months to break even. There are currently around 400 of these C Labs.
IDH serves the private healthcare market in Egypt and other regions. General practitioners are rarer here, and patients typically choose their diagnostic service and obtain results themselves. They then bring these diagnostic results back to the physician that recommended them.

IDH distinguishes between Contract and Walk-In segments. Contract revenue was around 54% of revenue in FY20, with the remainder coming from Walk-In.
The walk-in clients, also referred to as “self-payers”, pay out of pocket for diagnostic tests and other services. In the first quarter of 2021, only about 34% of IDH’s 2.4m customers were walk-ins, but these represented 47% of revenue.
IDH’s contract clients include institutions who enter into one-year renewable contracts at agreed rates per-test and on a per-client basis. Corporate clients include unions, private and public insurance companies, banks and corporations, and public institutions.
Market & Competition
What is the state & size of the company's market?
There are powerful structural growth drivers in place that underpin a promising outlook for medical diagnostic services in the Middle East and North African regions. These include:
- A large, rapidly-growing populations,
- A high disease burden with an increasing prevalence of lifestyle-related medical conditions, and
- An expanding, health conscious middle class.
Healthcare expenditures per capita and lab tests per capita indicate IDH’s large, growing markets are underpenetrated. They are also fragmented, with lots of individual clinics run by doctors.
At just over 100 million people, Egypt is the third most populous country in Africa and by far the most populous in the Middle East. It also has a high disease burden and a high incidence of lifestyle-related medical conditions. A growing consumer class is, however, becoming more health and wellness conscious.

IDH enjoys a dominant market position here, with more than 50% share of revenue in the private chain market segment of the Egyptian Diagnostics Industry. It has a substantially larger footprint than its competitors but there’s plenty of scope for additional branches.
In terms of the Diagnostics market itself, this can be viewed as a subset of Healthcare alongside Pharmaceuticals and Primary Care. Diagnostics is key because as much as 70% of medical decisions are based on lab results.
There are three main participants in the Diagnostics value chain: original equipment manufacturers (OEMs), third party equipment suppliers, and service suppliers. Larger players like Siemens and Roche occupy the upstream end of the value chain and their positions are hard to surmount as they use their scale to give away lab equipment for free to clients who can guarantee large volume purchases of the reusable products required to conduct tests.
Downstream we have operators such as IDH, who provide diagnostics services to customers and provide the actual tests. It’s a big marketplace and, in emerging markets in particular, can be fragmented. IDH is small, but acts as a consolidating force.
Who are the company's key competitors?
Competitors in Egypt include Alfa labs, which is half the size and lacks IDH’s scale advantage, lab accreditation, and brand strength.
The two largest private hospital groups in Egypt are Almeda and Cleopatra but neither have the scale to be a serious threat. Public hospitals are under severe pressure to keep up with a growing population and the government is actively encouraging the private sector to assist with the growing demand.
The remainder of the market comprises polyclinics, family practices and universities.
What is the company's strategy?
IDH ‘aims to be a leading healthcare provider in every community and region that it serves, becoming every doctor and patient’s first choice for quality, accurate diagnostic testing and cost effective services’.
More specifically, it’s looking to drive growth through four strategic goals.
- Expand customer reach. It’s opening new laboratories and is reaching out to customers via marketing and new services.
- Expand geographically. IDH is looking for acquisitions in African and Middle Eastern markets where its business model is well-suited to capitalise on similar healthcare and consumer trends. These tend to be fragmented markets, where it can leverage its scale, expertise, and capital-light model to quickly take share.
- Increase tests per patient. Opening more branches will add both patients and tests, which should drive the tests per patient KPI.
- Diversify into new medical services. The group also looks to add diagnostic and medical services not currently provided on a large scale.
How does it derive its competitive advantage (if any), is it durable and is there evidence of one in the financials?
IDH’s markets are characterized by high barriers to entry and persistent high margins. The group has scale advantages, as well as established brands which provide a degree of pricing power.

Its facilities have sought after international accreditation: College of American Pathologists (CAP) and the International Organization for Standardization (ISO).
Key stakeholder relationships - building a scalable platform requires strong relationships with all stakeholders, from key suppliers to the Ministry of Health.
These go some way to explaining the group’s ability to maintain margins over time.

Valuation
How does the relative valuation compare versus industry and sector?
While IDH is growing and profitable, the share price has not risen alongside earnings.
This means that the group’s relative valuation has declined considerably despite solid strategic execution. Assuming this continues, the share price should at some point rerate to reflect the financial growth.

It is rare to find a company with such quality metrics and growth rates as IDH on a low-teens forecast PER. As such, a rerating of share price multiples combined with steady earnings growth in keeping with its established strategy could lead to good upside.
Risks, Threats & Hurdles
What are the biggest risks, threats or hurdles that the business may face?
But there are risks too, hence why investors can pick shares up at just 13.8 times forecast earnings despite the obviously attractive financial characteristics.
IDH specialises in unfamiliar markets and as such, should be viewed as a riskier investment. These markets bring political, security, and economic risks.
This is an Egyptian company listed on LSE, with headquarters in Jersey. It buys imported goods priced in USD with EGP, so there is also currency risk.
KPMG recently abruptly left IDH as its auditor. You can read its statement on the matter here. This is the important paragraph:
The circumstances connected with our ceasing to hold office relate to our concerns in relation to the robustness of the control environment at the Company. This matter led to difficulties in our obtaining sufficient and appropriate audit evidence on a timely basis and, latterly, to a deterioration in our relationship with management. Such circumstances did not however affect our ability to issue an unqualified audit opinion, or otherwise to fulfil our professional obligations in respect of the audit of the financial statements for the year ended 31 December 2020.
PwC, another big accounting firm, has stepped in to replace KPMG. While that provides some reassurance, KPMG’s comments should considered carefully.
Liquidity of stock can be an issue. There is limited daily volume due to tightly held shares.
There is also a longer term threat of commoditisation in diagnostics, although IDH’s brand power and scale could mitigate this.
Recent Trading & News
Summarise the most recent trading statements and comment on them
Integrated Diagnostics Holdings reports record-breaking revenue and net profit growth in 1Q 2021 supported by a strong performance across entire service portfolio… we are upgrading our guidance for full-year revenue growth of over 20% with a consolidated EBITDA margin in line with 2020 levels
Around 47.4% of Q1 revenue came from Covid-19-related testing, so whether or not these growth levels are sustainable remains to be seen. Even after stripping out all Covid-related business, group revenue would have increased by 20%.
While the Covid-19 crisis continued during the early months of year, management believes that 2021 will witness a continued recovery, in part driven by the strong fundamentals of the healthcare industry across the Group's footprint, as well as the ramp up of vaccination campaigns across the globe. Almost halfway into the year, we are confident in the Group's ability to adapt to and overcome the most difficult challenges supported by the adaptability of our business model, the strength of its brands, and the solidity of its financial position. Accordingly, we are again targeting double-digit revenue growth in 2021 and an EBITDA margin of c. 40%.
Sentiment
What do the brokers currently think?
Ten brokers have IDH as a buy/strong buy, and consensus earnings forecasts have been on the rise.

What is private investor sentiment at the moment?
IDH is shunned by institutional investors but appears to be more appreciated by the Stockopedia community.

What would the person selling to us be thinking and who are they?
- It’s an overseas listing with operations in potentially risky areas, and has FX risk.
- Change of auditor could be interpreted as a red flag.
- The boost to results from Covid testing could be understated.
Conclusion
This pitch split the Club, with points of concern balanced against some attractive fundamentals, but the vote was just in favour of a buy.

Clearly this is an unusual LSE listing, but one with obvious quality characteristics. While management appears to have executed competently over the past five years, overseeing substantial revenue and profit growth with plenty of runway for further expansion, the share price has remained rangebound.
Overseas companies get a bad rep - you might argue that this is deserved, but, in this instance, has it led to the mispricing of a growing, quality healthcare operator?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

24 comments
Great preliminary results today, phrases like Outstanding Performance and All-time High. Increased dividend.
company has more upside than down although it does appear to have fragile foundations buy with tight parameters for a quick opt out, large movement in the price would be of concern
Today’s half-year report reads well:
“Integrated Diagnostics Holdings Plc delivers exceptional growth on the back of strong demand across its entire service portfolio”
The one thing I misssed was any reference to who the directors were and what background they had.
Interesting defensive business for sure, i look at their results once per year, i wasn't aware of the auditor resignation, that's concerning, also their perfect financials are a slight concern. I keep my position at around 3%
I found these guys by going stock by stock through Terry Smiths sister fund FEET which i also own. I have been following the company for a few years, take my deep dive with a pinch of salt, i'm no accountant link
Really fantastic summary Jack on £IDHC. In line with my views and bought at 79.55 on 29/3/21 and 2nd tranche on 3rd June following positively quarterly update, which was regrettably just before the disappointing KPMG statement (as an accountant myself by background). However personally: a) think the concerns are in the price b) it is a great blend of value (increasingly so as you said) with growth (asset-light business that is funding its own growth and in growth markets). c) the quality of the investor presentations and data is better than most other companies, which I find reassuring with the high management stake and alignment. I originally heard about it from a podcast with ScotGems, who hold it and it is one of the largest single-company positions I hold so wish the club and all others well with it!! (but a small part of my overall portfolio so happy with this). MP27
If it looks too good to be true, it probably is. Why is this company listed in the UK?
The PE certainly looks reasonable, but is it possible to calculate what it would be on an ongoing basis if the COVID revenues were excluded?
I was intrigued by the reason KPMG gave for resigning as auditors, which I'd never heard of before:
The circumstances connected with our ceasing to hold office relate to our concerns in relation to the robustness of the control environment at the Company
I went and had a look at what a 'control environment' is.
In essence the control environment is the culture and rules that ensures that the employees behave in a way that ensures accurate and consistent financial reporting. For example, making sure there's a robust process in place for checking sales invoices.
So if an auditor is unhappy about the control environment it means it lacks confidence in the information it's receiving. And, presumably, that means it needs to spend more time crosschecking everything to the point where the audit is uneconomic - which KPMG did to the point of being happy to certify the results before walking away.
Personally I wouldn't invest in this - if the financial controls are weak then the possibility of fraud is increased. Auditors can only pick that up after the event, assuming they do at all. That really isn't a safe situation for an investor.
timarr
I agree - auditor resignation in these circumstances makes it a bargepole stock for me. I had a bad experience in a previous life with a private company in the U.K. where the auditors (PWC in that case) resigned and the whole thing unravelled as one big fraud and several directors ended up going to jail.
Reading the company RNS (note the statement is from the company rather than KPMG or the new auditor designate PWC directly) I would be very wary until PWC are definitively signed up and ideally have done their first full audit. It’s possible KPMG have signed off their audit but we don’t know with what caveats. For example they may have made their sign off conditional on being able to assume all information from the company and its officers and employees is true and complete - which is a nonsense if they don’t Trust the Control Environment. It could be the audit issues relate to the possibility of a few suspected fingers in the till at the bottom of the Food chain, but equally might be something rotten a lot higher up in which case the problems could be a lot more serious. It could all be perfectly innocuous and in time the company’s probity will be proven but why take the risk?
Gus.
Yes Timarr I totally agree with you. The cons heavily outweigh the pros for me here esp. the auditors points. However Jack I thank you so much for great work here and I very much look forward to the next stock featured. What a great site this is !
No mention of the risks from politics and religion. Are the key players ie main shareholders, sponsors, etc friends or competitors of the ruling elite? Or do these people own the competitors so that with a little help from the powers that be they could force IDH into an unfriendly "merger"?
50/50. Egypt is currently a stable country but can be volatile occasionally. The fundamentals look encouraging but I personally would rate the stock a bit more speculatively
I bought in just before Q1 2021 results were released in June. By following the link in the Q1 RNS I was able to join the company presentation which unusually mixed private investors with analysts. Whilst the presentation basically repeated the RNS and was a bit dull the company did a good job of trying to answer the questions.
What came across was the company appears to have good control of pricing and is ensuring a standard margin across the range, COVID tests are more expensive but produce the same % margin so are benefiting the bottom line significantly. It came across that the companies forecast that 2021 revenue will be ‘more than 20% above 2020’ is a major understatement. Q1 revenue (1130 EGPm) is equivalent to 42% of 2020 full year revenue (2656 EGPm) and the company confirmed that Q2 had continued as Q1. So I am hoping that H1 revenue alone will be close to 2020 full year. There is scope for a significant upgrade of forecast at that point. I think the company are estimating a drop off in covid related tests fairly quickly, but I wonder if this will be around for some time so 2022 numbers could also be conservative.
The company is also clearly considering M&A and it sounded like they have targets in mind but were playing cards close. They were pushed to say whether the target was middle east based which they sort of did. Clearly the Nigeria addition does not look impressive at this point. They have put in place a US$ 45million financing facility for this purpose.
The company has an excellent investor relations web presence with lots of info.
Not without risk, but plenty of positives at this point.
It is possible that the returns may not be as high in sterling terms due to the Egyptian inflation (the accounting currency is the Egyptian pound). Projections of inflation up to 2026 are around 7.5% and in the recent past have varied between 4% and 23%, rendering some of the historic growth meaningless. Inflation must be considered as a major risk for this asset. I do not hold and this inflation risk means it is unlikely to make it to my watch list. https://www.statista.com/stati...
I've recently built a position in Integrated Diagnostics Holdings (LON:IDHC) . the liquidity is poor so had to buy in several small tranches and call up the broker. The CEO (and her mum who set up the first lab) own 25% via their holding vehicle, she is also a trained clinical pathologist (with US research experience) who has a thorough technical and scientific understanding of the industry. The company reports in EGP so the currency devaluation over the past few years need to be factored in when considering growth figures in USD or GBP. The company's recent expansion into radiology services while leveraging its brand has fantastic further growth potential both in Egypt and other large markets like Nigeria. Integrated Diagnostics Holdings (LON:IDHC) also engages with customers digitally e.g. delivering results via app which may bring further sales opportunity. Egypt's population is ageing which is likely to bring greater demand for medical services all else being equal and elsewhere in Africa populations are better fed and fatter leading to more chronic disease e.g. diabetes and hypertension.
The share price is currently around where it was at the heavily oversubscribed IPO (there has been a stock split) , so given the impressive revenue and profit growth since then the company has significantly derated. I would speculate that the turbulent economic and political circumstances in Egypt has left institutions to largely avoid the shares for now. But in such an environment this business is about as defensive as it gets ( and has a competitive moat to boot).
My view on the recent COVID-19 testing bonanza the company has benefitted from is that these revenues will be somewhat sticky. Egypt currently has a very low vaccination rate, new variants will continue to emerge and test manufacturers are developing other tests for viral respiratory infections e.g. influenza. In future patients (and their doctors) will want to know which virus is causing their cough and will be able to pay for a test to find out.
KPMG resigning should be a major red flag !
Capex has fallen quite sharply for the past two years.Unsure if that is sustainable.
the company's Cairo "megalab" opened and got a US certification in 2018. Was a large one-off spend so likely explains the fall in annual capex. It appears it is quite cheap for the company to open satellite branches which then feeds tests into the larger existing labs.
The fundamentals are impressive, especially the margins which ultimately drive the business forward. The fact that this company is London listed is a great demonstration of its organisation and potential. The directors have been buying shares for some years and not selling which is a sign that they are fully committed. The company is dual listed on he Nilex Egyptian stock market as well. I have bought medical devices from Egypt tend the quality can be excellent but I always have a certain doubt about the fact that the country is basically a dictatorship run by Abdel Fattah Al Sisi and is not a democracy. However apart from Lebanon no country in the Middle East is a democracy and this need not be a limitation to investment. This depends on your approach. I will be investing gin this company as I have done with similar Hikma Pharmaceuticals. but it will always be a smallish holding.
IDHC - great to see this stock pitch. I likewise could not ignore the numbers and made my first investment early June 21 and added more in early July 21, so far -2.61%. Clearly overseas risk, but to consistently grow and maintain margin, shows me this is an efficient growing business.
Hi Jack, did the Club buy this stock?
The voting was very similar to Xpediator (LON:XPD) which was not bought.
It would be helpful if all these were listed under the Investment Club as that would aid searching. I did find this link on an earlier post: https://www.stockopedia.com/co...
Also is it possible to announce any Club stocks when they are stopped out?
Hi Herbie,
The way this one played out is that we had two pitches as part of the same round of voting. One of the Club votes in this instance was to only buy one stock. It was actually a tie between Xpediator (LON:XPD) and Integrated Diagnostics Holdings (LON:IDHC) and so there was a revote.
This second vote, again, was very close but IDH got the nod. Hope that clarifies.
At present it's more a question of design and dev work to have a list of holdings on the blog page.
Here are the holdings right now in order of % gain (or loss in some instances); perhaps we can just start leaving comments clarifying the holdings.
Reach (LON:RCH)
Ergomed (LON:ERGO)
Sylvania Platinum (LON:SLP)
Water Intelligence (LON:WATR)
Ferrexpo (LON:FXPO)
Polar Capital Holdings (LON:POLR)
Safestore Holdings (LON:SAFE)
Volex (LON:VLX)
Ig Group (LON:IGG)
B&m European Value Retail Sa (LON:BME)
Computacenter (LON:CCC)
Gear4music Holdings (LON:G4M)
Tremor International (LON:TRMR)
Tandem (LON:TND)
Integrated Diagnostics Holdings (LON:IDHC)
Tharisa (LON:THS)
And yes we can update on getting stopped out. We did start including a small 'Edit' section at the top of relevant Stock Pitches, we can get back to updating these.
Thanks Jack, that is very helpful. There was some discussion on Fonix Mobile (LON:FNX) yesterday, I thought it would have been stopped out but was not sure.