Stock Pitch - Serica Energy (LON:SQZ)

Serica Energy (LON:SQZ) was pitched to the Stockopedia Investment Club on February 16th 2021 as contrarian value bet on a rerating of quality operators in the oil & gas industry.
This is a sensibly run, cash generative oil & gas producer with production, development, and exploration assets in the UK Continental Shelf (UKCS). It is responsible for around 5% of the UK's gas production.
Serica has a strong balance sheet and a material net cash position. It is initiating dividend payments and there are several explicit near-term catalysts that should further enhance free cash flows over the next couple of years.
Yet oil and gas is unfashionable, with ESG concerns driving capital out of the industry. Meanwhile, Serica needs to develop existing assets and acquire new ones in order to extend its life of operations.
But the shares are cheap compared to cash flows and there are opportunities in the UKCS - in 2020 RockRose Energy rapidly grew into a c£200m enterprise by acquiring assets in this area. There is also scope for further recovery in gas prices.
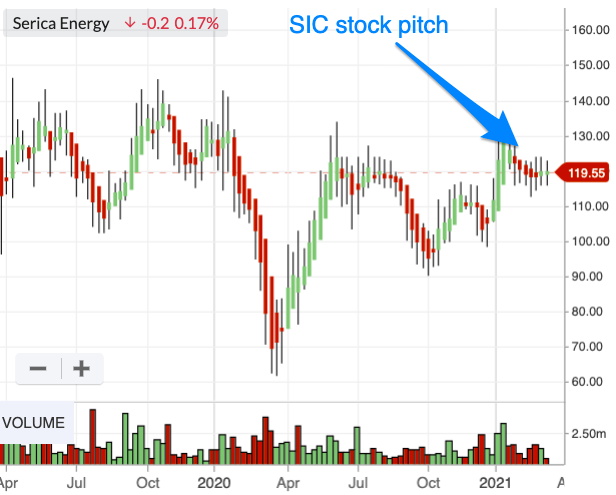
Despite the improving price outlook, Serica's share price remains rangebound. Is this justified or is a rerating on the cards?
Summary
Bull Points - exposure to improving oil & gas prices; experienced management and high-quality assets in a stable jurisdiction; commodity price recovery is now a tailwind; Rhum 3 and Columbus can increase cash flows over the next year or two; £60m of net cash for M&A; initiating dividend payments; limited decommissioning liabilities
Bear Points - Capital is flowing out of O&G; ESG trends are against it; gas and oil prices might fall; R3 and/or Columbus could slip; exploration assets might get relinquished; Serica needs to make acquisitions to expand reserves
Profile
About the Stock:
Serica Energy is a Speculative Small Cap Super Stock trading on the AIM market. It is in the Energy sector, in the Oil & Gas industry.
The share price is 116.8p and so, with 267,904,093 shares in issue, the market cap is £312.9m. A net cash position means the group's enterprise value is smaller, at £251.3m.
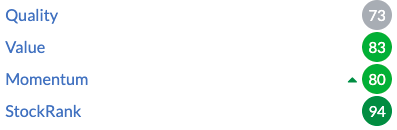
The group has a StockRank of 94 and a strong spread of factors, with a Quality Rank of 73, a Value Rank of 83, and a Momentum Rank of 80.
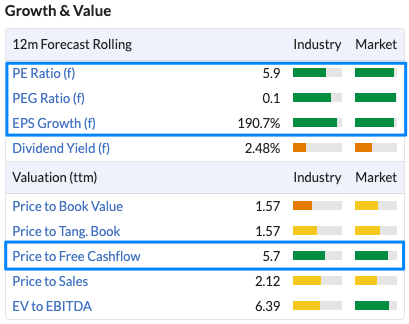
The value on display is highlighted by a forecast PE ratio of just 5.9x and a price to trailing twelve month free cash flow of 5.7x. This improves further once you factor in the net cash position.
Over 80% of its production is natural gas, which has significant environmental advantages over other fossil fuels. Gas is a key element of the UK’s Energy Transition.
In terms of quality, Serica is cash generative even at low spot prices and has a very strong balance sheet. It operates in a stable jurisdiction (the UKCS), decommissioning liabilities are modest, and it has a solid institutional shareholder base including the likes of Polar Capital and Axa Framlington.
Serica also has promising near term operational catalysts in the form of Columbus and Rhum 3 that pave the way for higher free cash flows and 2P reserves over the next couple of years.
Business & Model
What is the company history & what does it do?
Serica owns exploration, development, and production assets in the UK North Sea Continental Shelf. As major companies restructure their portfolios in the region, Serica aims to benefit via value accretive M&A.
The group acquired its interest in Erskine Field from BP in 2014.
In 2018, Serica became a major player in the UKCS with its transformational BKR deal.
What is the business model? How does it make money?
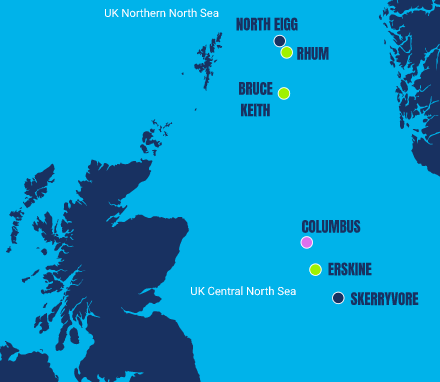
Serica’s main focus is on production and development of gas and oil in the UK North Sea.
Source: Annual Report
It is owner and operator of the Bruce (98%), Keith (100%) and Rhum (50%) assets. These assets are estimated to contain net 2P reserves (proven and probable reserves) of 51.4 mmboe (million barrels of oil equivalent), of which more than 80% is gas.
The Rhum gas field has significant upside potential and Serica is currently working on a third well (R-3) to increase production.
There is also an 18% non-operating interest in the Erskine field, which is operated by Ithaca.
It has one development asset (Columbus) and two main exploration assets: North Eigg (130mmboe P50 prospective resources) and Skerryvore (2 licenses). Columbus start up is targeted for 2021.
Market & Competition
What is the state & size of the company's market?
The offshore oil and gas industry currently meets 45% of the UK’s overall energy needs and will continue to provide energy security for decades to come. Production of domestic oil and gas directly accounts for around 1.2% of the UK’s GDP and will contribute billions of pounds of taxes in the future.
Total production in 2019 was around 630–640 million boe or 1.73–1.75 million boepd. Around 45 billion boe have been recovered from the UKCS since production began in the basin in 1967, with an estimated 10–20 billion boe of potential resources still to be recovered.
SQZ has 62mmboe in total.
What is the company's strategy?
Serica will drive value for shareholders by:
- Reducing costs and expanding producing BKR assets (R-3 and move to 100% ownership),
- Developing existing exploration assets (Columbus and North Eigg),
- Acquiring new assets and licenses, and
- Paying dividends.
How does it derive its competitive advantage (if any)?
Serica has operational expertise and specialises in the UKCS. It knows the assets and infrastructure. Larger companies are divesting non-core assets, and more leveraged operators might become distressed sellers.
Serica can capitalise with its strong cash flows and net cash balance sheet.
Is the competitive advantage durable and is there any evidence of one in the financials?
Returns have been volatile, but often double-digit and usefully resilient in tougher price environments.
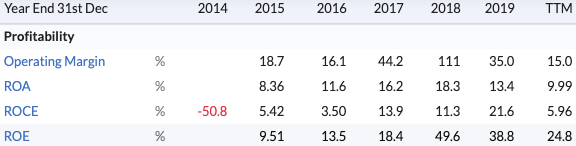
There may not be much in the way of a durable moat here aside from operational expertise, but there are plenty of opportunities for Serica to profitably grow and create value for shareholders.
Financials & Ownership
What is the record of growth & profitability?
The transformational nature of Serica's BKR acquisition limits the comparability of historical results. Moving forwards, forecasts for FY20 have been brought down but brokers anticipate a sharp rebound in FY21:
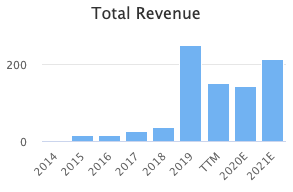
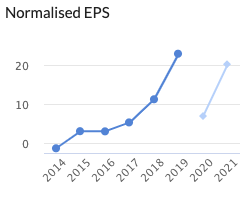
Serica has generated impressive earnings per share growth in recent years. FY20 is expected to be lower but we can again see the consensus is for a recovery in profitability in FY21.
What is the state of the balance sheet?
The balance sheet is strong with net cash of £62m. The F-Score of 6 is decent and the Z-Score of 2.72 is good.
Decommissioning liabilities are acceptable, with non-current provisions of £22.6m for the Bruce and Keith interests and no provision for Erskine.
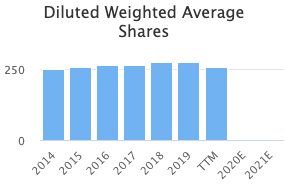
Shares in issue have also remained stable.
What is the ownership structure of the company and do management have stakes?
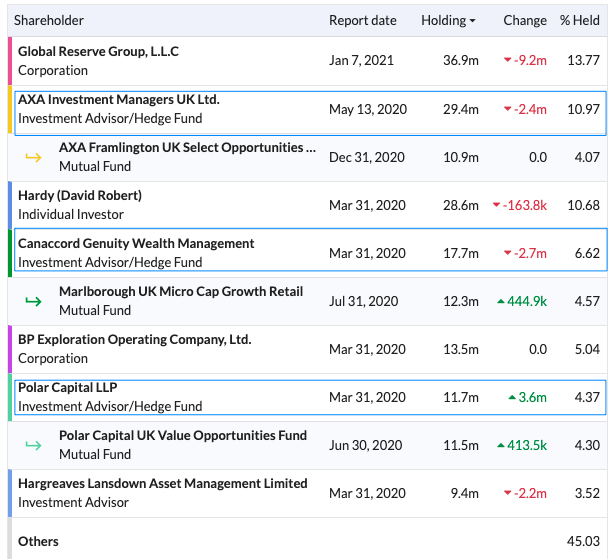
The shareholder base is good for a small cap oil & gas - a 58% free float and institutional holders like Polar Capital, AXA, Canaccord, and BP.
Valuation
Serica has a Value Rank of 84 and is in the top third of the oil & gas industry in terms of price to forecast earnings. The group's strong cash generation is highlighted in a price to TTM free cash flow multiple of just 5.7x.
Trends & Catalysts
Are there any catalysts could drive a rerating in the medium term?
Serica has several potential catalysts on the horizon
- North & South Eigg licenses - Serica acquired these in December 2019 and work is ongoing. 3D seismic data in the North suggest characteristics similar to Rhum.
- Skerryvore and Ruvaal - A drill or drop decision is expected by the end of the initial three-year term in September 2021.
- Rhum 3 well - Serica hopes to commission the R3 well for production in 2021.
- Columbus - First production from Columbus is planned for late 2021.
- Increasing BKR ownership - Serica’s share was 40% in 2018, was 50% in 2019, and was 60% in 2020. It will be 60% in 2021 and 100% from 1 January 2022.
- Recovery in gas and oil prices (but this can cut both ways).
- Dividend payments.
- Potential M&A.
Risks, Threats & Hurdles
What are the biggest risks, threats or hurdles that the business may face?
- Asset risk - several near term catalysts such as Rhum 3 and Columbus could be delayed. Producing assets could be disrupted.
- Exploration risks - there are no guarantees of striking black gold. Serica has recently relinquished its Rowallan Prospect, Frontier Exploration, and Columbus West licenses.
- Commodity price risk - oil and gas prices can go down as well as up.
- Downstream risk - continued operation may be adversely affected by interruptions to operations of fields and infrastructure downstream
Recent Trading & News
Summarise the most recent announcements, news and trading statements and market reaction to them
H1 20 results (September 2020)
We are looking forward to a very active second half of the year... We look forward to being able to commission the R3 well for production in early 2021. Planning for the Columbus development continues and a contract has also been signed for a Maersk rig which will drill the development well in 2021. First production from Columbus is planned for late 2021.
Although we are prepared for further market volatility, we expect oil and gas demand to recover as economies emerge from lock-down. With our strong cash balances, no debt, full-lifecycle operational capability and capacity to grow, Serica is positioned to play a leading role in the recovery.
Corporate update (January 2021)
We have entered 2021 with considerably improved gas prices though with notable volatility so will continue to carry downside protection at an appropriate level... We believe 2021 will bring new opportunities to grow through acquisition against a more confident industry backdrop. However, we will continue to screen all opportunities vigorously and prioritise delivering shareholder value over simple additions to scale.
Conclusion
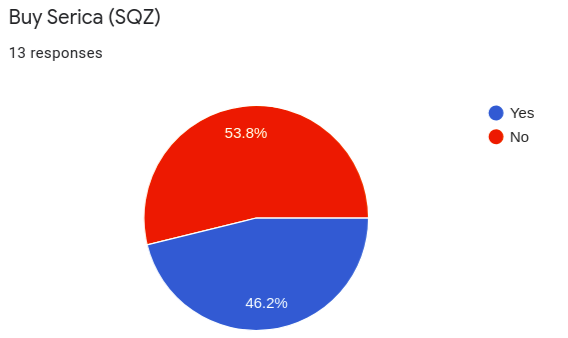
Serica Energy proved a divisive pitch for the Club, which narrowly voted not to buy shares.
The oil and gas industry is low quality and high risk, filled with highly speculative shares and an above average possibility of permanent loss of capital - but this does leave the Club with no Energy stocks at all.
With commodity prices rising and economies unlocking, the outlook is improving for oil and gas. Is now the time to increase exposure to the Energy sector, or is the SIC better off leaving this part of the market alone?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

24 comments
Morning Ray.
If you’re interested in speculative Oil & Gas developers (and I’m not suggesting Serica Energy (LON:SQZ) is one) ……. you’re probably in a very small minority on this site! It’s a sector I’ve probably bet too many chips in over the years and as many commentators warned me ahead of time most of them haven’t come off for one reason or another. And when they don’t come off they frequently result in 70%+ drawdowns in a very short space of time.
So with that warning in mind my current (and has been for a pretty roller coaster six years) peccadillo is a company called Pantheon Resources (LON:PANR) . At one point in 2016/7 it was on the cusp of a huge development project in Texas which for various reasons didn’t come off and resulted in a near death experience for the company (and its shareholders). I merrily watched the share price rise from an initial entry level of about 30p up to a peak in the 180p’s (wasn’t I smart) before not so merrily holding all the way back down again to single digit pennies (wasn’t I stupid) as massive dilution was needed to keep the lights on.
Wind the clock forward to 2020/21 and they’ve reinvented themselves as a prospector in the Alaskan North Slope area. Possibly more by luck than judgement (actually to be fair it’s probably judgement, my principal reason for being in this stock is that I’ve met and highly rate the CEO Jay Cheatham) they appear to have struck major pay dirt with a group of fields that prospectively contain well over one billion BOE very close to existing transport infrastructure. A lot of detail both in the company profile:-
http://pantheonresources.co.uk...
and a very detailed presentation from August this year reviewing the results of the early stage drilling and testing.
http://pantheonresources.co.uk...
The strategy is to drill, test, prove up the reserves and then sell the company to an oil major in a relatively short time frame (rather than become a long term producer themselves) - not least because most of the senior execs are close to if not we’ll beyond sensible retirement age. Share price has taken off recently which is either rampant speculation or a considered risk/reward view that if proven up the indicated reserves would justify an exit price of at least 400p a share. High risk and highly speculative IMO it’s either an 8-10x upside or a total wipe out.
Gus.
Yes one that got away but I assume some members are not keen on this sector.
With hindsight they should have increased their exposure to this sector, it is one of few that has performed well in the last few months.
I would be interested in an updated performance table and also a table for the rejects, it looks like some of those have done rather well, such as £WOSG.
With the current natural gas prices this looks very cheap. I have seen some conclude that they could generate around USD1.7m per day. Looking at the futures market, the prices look to be staying elevated for circa 6 months, which means this could generate something like half it's market cap (£200m) in cash in the next 6 months.
Confirmation of first gas and oil being taken from the Rhum 3 well this morning.
https://www.investegate.co.uk/...
Company is justifiably upbeat in their comments.
Gus.
Very positive flow test results announced on the Columbus development well this morning.
https://www.investegate.co.uk/....
Expected to come fully on stream in Q4 this year. Excellent result and further demonstrates Serica Energy (LON:SQZ) credentials as a well run quality O&G operator.
Gus.
Hi Gus...
As a LTH I'm very pleased with this news and the RHUM drill results too!
"Operations on R3 have proved more challenging than expected but the skill and dedication of our operational team has enabled us to achieve this welcome result. The volumes flowed during the test are equivalent to over 10K boe/d which demonstrates the quality of the Rhum asset". That is (5Kboe/d to Serica Energy (LON:SQZ)), but this was limited by the equipment so potentially more upside?
this alongside the Columbus result which is 7Kboe/d gross. another 3.5K? to Serica, meaning if I've understood it properly, we are adding 8500 boe/d equivalent, mostly in Gas and condensate, to our sales over the next 6 mnths.
Currently SQZ have reported in Mar this year..
· Average net production of 23,800 boe per day (2019: 30,000 boe per day) - reduction reflects 1H caisson repairs and other field maintenance work.
So these two results add considerable upside to their production. As you point out Gus, "Great results and credit to this well run O&G..."
As for the share price, it's finally moved off of £1.20 area which it seems to have been stuck at for the last few years... and is now paying a dividend...
I'm not sure the stocko ratings have digested this info into their ratings and figures on the company stock report FYI.... so potentially a buying opportunity..
Having tried and failed at a lot of oil investments... Serica has been one of my success stories and I will continue to hold for the foreseeable future.... (hope I haven't jinxed it now !!) and Serica is GAS rather than oil, so more in vogue for those of us who are carbon concerned.... and more politically palatable.
thanks Jack and Gus for your input on this
Patrick
I think there is a lot of uncertainty around Hydrocarbon stocks Jack. As you know markets hate uncertainty. Renewables/Hydrogen have done well suggesting the market believes we are generally moving away from this sector.
Thanks for this Jack. I've held Serica Energy (LON:SQZ) on and off over the last two years, with currently no holding. I think buying right now is a little bit of a punt on whether the R3 intervention issues can be addressed or will become a wider and more expensive issue. That's obviously a shorter term factor, but leaves me sitting on the sidelines till it is resolved either way. On a longer term view, I think Serica has some compelling characteristics that you have highlighted above. It would not surprise me at all if it was taken out this year as well.
Perhaps a lot of people don’t realise that there is more to oil and gas than meets the eye. Oil chemicals go in lots of things, fabrics and pharmaceuticals to name but 2. In addition gas goes into synthetic liquid fuel and is the feedstock for quorn!
So you don’t just get energy from them.....
Can you enlighten me how gas is a feedstock for Quorn?
The fermentation medium for Quorn contains various salts, glucose and ammonia. Most ammonia production is from natural gas. I think Quorn has a lower CO2 footprint than chicken but the difference is not huge.
"Soybean oil is currently a major feedstock for production of biodiesel"
I think you are confused. It does give off lots of gas. Quorn is just an american brand name.
I must be confused as I thought Quorn was a food produced by the fermentation of fungus. Are you saying Quorn is an American brand name for biodiesel?
No it is a food brand, meat substitute.
Agreed, everything is made with Oil and Gas. Even wind turbines and solar panels need absolutely shed loads of hydrocarbons to produce them. Hydrogen From water needs massive amounts of electricity to turn H20 into H2 and 02, personally the ESG issue might have the head wind and will be a recipient of Government handouts but without oil and gas non of it will happen.
Even the EEV (emission elsewhere vehicles) run on Electricity and not pixie dust.
As of Jan 21, 30 Terra watts out of approx 70 is produced by Gas in the UK
Really surprised by this outcome; and as you say you have no energy stocks in the club now. Energy and financials are probably the best bets for gains going forwards. Serica is probably the most well run and undervalued in the sector. BKR going to 100% next year and the stock is currently on a 12 month trailing PE of 6.1...wow! OFAC license renewal has already been granted, whoever mentioned that. Usually I always agree with the decisions but I think this one could be a bad decision.
Good call mblackstock8.
I have not been following this stock as I am focussed on ZPHR. Will follow now though as imo both show promise into a strong energy mkt. I thought you might like the following article as it goes a long way to explain the outlook for the energy sector and the bull case for nimble smaller cap gas/oil shares. Not sure it has posted entire link but if you type in Energy Matters Another Fine Mess article by Chris Sladen you should find it.
https://anzmex.org/energy-matt...
SQZ still a good fwd p/e!
Wentworth Resources (LON:WEN) ....?
I've owned Serica Energy (LON:SQZ) a couple of times, they popped up on the Jim Slater screen a couple of years ago so must be a well run outfit.
I sold out when I realised their is a US Sanctions waiver they have to apply for every few years, as 50% of the RHUM oil field is owned by an Iranian oil company, and I was worried, especially with the previous POTUS, he may go for anything with an Iranian connection.
I see they still have to apply for this waiver, current one runs till 2023, was this ever a concern or did I worry too much about it.
(Share price is practically identical to what I sold them for in 2019.)
ita renewed just recently, almost the first thing Biden did in his new administration.
Renewal was never in doubt. Serica provides 5% of the Uk's gas supply.
In theory Serica Energy (LON:SQZ) look a good bet, its just started paying dividends and there's no debt so what's not to like? The share price has been mediocre despite oil going from $40 to recently $70/b but since June 20 there's been no SP momentum whatsoever. I believe there are some production issues which were due to be fixed in Jan/Feb but also some growth opportunities in Q1 from R3 well and in Q4.
Compare Serica Energy (LON:SQZ) against £ENQ or £TLW and there's no question which has the better investment metrics but that's not where you're going to make the most money.
Interesting pitch Jack. On 9th Feb I took a small position in £BP 1% and Royal Dutch Shell (LON:RDSB) 3.2% and as I write I am up 20% and 14% respectively. We are going to need oil for a long time and I just felt at current prices it was a safe bet plus a decent Divi given that my Dividend income has been hit badly in the last 12 months. I do not often buy oil shares but I have never forgotten the great ad from many years ago "You can be sure of Shell"
Hi portugull,
They look like well timed buys, well done. Going for the majors could be a safer contrarian bet and it certainly looks like Royal Dutch Shell (LON:RDSB) at least is rerating - unfortunately it falls short of one of the Club's screening criteria (we only look at StockRanks above 75) so it doesn't turn up in our screens yet.
In terms of those currently with an SR > 75, SQZ appears to offer a good balance of potential upside when compared to jurisdiction risk, decommissioning liabilities, financial health and the rest of it. There are a couple of other candidates but with Yellow Cake (LON:YCA) and Serica both getting no votes recently, it seems like there's not much appetite for Energy stocks at the moment!
Best of luck