Stock Pitch - Wey Education (LON:WEY)

Wey Education (LON:WEY) was pitched to the Stockopedia Staff Investment Club on the 18th August and shares were purchased a day later at 24.45p. The shares were sold on 7th April at 46p after a recommended takeover bid. An 88% return.

TLDR;
Wey Education (LON:WEY) - a micro cap growth share benefiting from the accelerated shift to online education due to coronavirus and technology trends.
- Bull Points: covid beneficiary, significant cost advantage vs physical schools, clear growth opportunity in a fragmented segment of a large market.
- Bear Points: "it's just a school", no clear technology advantage, recent director sales, marketing execution risk, illiquid micro-cap, premium valuation.
Profile
-
About the Stock: Wey Education is listed in the Consumer Defensive sector, providing online education both in a B2C and B2B fashion. It trades at 26p per share, with an exchange market size (EMS) of 15k - it's very illiquid. This is a Micro Cap with a £36m market cap and is 'highly speculative' according to the RiskRatings. The StockRank is 77 - it's not cheap, but is profitable, growing and has a good Quality Rank of 84 and a strong Momentum Rank of 91.
-
Opportunity Type: In our Styles framework, this is a Highly Speculative, Micro Cap, High Flyer. It's a essentially a strong growth, low PEG share.

Business & Model
- Company History: Wey Education was founded in 2004. It provides 100% online education across 2 business units: InterHigh School and Academy21. The company states that it has been "providing a positive alternative to physical schooling since 2005." It has educated 12,762 learners since it was founded, and has 144 employees.
- Business Segments:
- Interhigh - this is the UK's largest online independent, fee paying school which the company says will have more than 2400 students by year end 2020.
- It provides fully synchronous, class based, online Primary, Secondary and Sixth Form Education and thus competes with physical schools rather than the on demand educational sector.
- Interhigh claims 73% Exam Pass Rates (A-C) for GCSEs. The Gov.uk website shows the new Grading system 1-9 for GCSEs and it's not clear if a C is Grade 5 of Grade 4. But for Maths & English at an 80% pass rate A-C : by my calculation that makes Interhigh a top 11% school. Their own marketing says they are in the top 15% of exam results versus schools nationally.
- NB - Online schools are not registered like normal schools but are considered part of the home schooling sector. This is under government review.
- Interhigh won "Educational Establishment of the Year’" at the Education Resoures Awards 2020.
- Academy21 - this is their "B2B" operation which was bolstered by an acquisition in 2017. It delivers services designed to help schools, local authorities and other public bodies such as children’s homes meet the challenge of delivering short, medium and long term provision for pupils with complex behavioural, medical and mental health issues. These are students not in the mainstream education system.
- Interhigh - this is the UK's largest online independent, fee paying school which the company says will have more than 2400 students by year end 2020.
- Business Model: Interhigh is effectively a private school, charging fees to each of its students. It generally gets paid fees in advance for the term or year - which creates an excellent cashflow situation akin to subscriptions- they receive cash well before paying the costs for delivering the service (e.g. paying teachers etc). Fees are low compared to physical private schools. Interhigh charges approximately £4k annually for Secondary/Sixth Form and £2k for Primary. Academy21 charges fees to councils and education authorities.
Market & Competition
- Market - Online education is a very large market in the UK but it’s very fragmented. There are 11.7 million students in education in the UK - with the State school market worth £36 billion.
- The UK independent schools market is estimated to be worth around £7.5 billion, with 2,000 schools attended by over 500,000 students. The 2018 Independent Schools Council Census stated that average independent school fees were £17,000 per annum, while boarding fees are now on average above £33,000. This compares to InterHigh’s current annual fee for secondary students of around £4,000.
- It is estimated that there are approximately 80,000 students in England who are currently home schooled as a matter of choice by their parents for various reasons. Home schooling has been growing quite quickly - see reports here, here and here and under the pandemic 87% of children were homeschooled. This is an obvious target market for expansion of the existing InterHigh Business.
- Competitors - aside from the obvious point that Interhigh competes with all the real world schools nationwide who are now all zooming, Interhigh's main direct competition is online educators. If you Google "Interhigh" you find only 2 competitors on Adwords. One of these is Harrow School Online.... whose strategy is mostly real world schools in the UK and Asia, but has diversified onto an online curriculum. They charge £15,000 annually (compare Wey at £4k). Eton and Harrow were mentioned in Wey's Admissions Document. Aside from these high end specialists - who can't be considered their real competitors - this is a pretty scrappy marketplace at the moment.
Strategy & Competitive Advantage
- Strategy:
- After the death of their chairman, the business refocused entirely on the UK domestic market with Interhigh & Academy21 as the core brands. Interhigh's stated goals are to sequentially:
- Become the size of the largest secondary school in the UK - i.e. 2400 students - within grasp this year in 2020.
- Become size of a multi-academy trust - i.e. in excess of 10,000 students.
- Previously they tried to set up an international wing focused on building operations in Nigeria and China, but they have now stopped the international expansion and took a write down to close these avenues. 25% of Interhigh's students are overseas students - the company is now focused on marketing to ex-pat communities & those who want a UK curriculum abroad.
- They are beefing up their leadership team - recently hiring a Head of pedagogy/education - Dr Sara de Freitas - future education strategy (3 pillars - improve engagement, raise education standard, robust & scalable systems) and a Head of Marketing.
- After the death of their chairman, the business refocused entirely on the UK domestic market with Interhigh & Academy21 as the core brands. Interhigh's stated goals are to sequentially:
- Competitive advantage
- It's an online only school - so is not hamstrung by trying to 'tack on' an online school to a physical school cost base. That makes it capital light. It's the physical cost base that is creating all kinds of problems for Covid hit physical schools.
- Something of a first mover in a large, and currently very scrappy market space.
- Any evidence of a durable competitive advantage? Using the typical moat framework - the only major advantage it has, versus the market, is its cost advantage. But that's purely due to niching into online schooling - which at this stage is rare for synchronous learning. One hopes that the business can develop the Interhigh brand, raise prices above inflation and continue to scale up. If it can then the ROCE and ROE could improve significantly.
Financials & Ownership
-
It has shown strong sales growth over a number of years: 156% CAGR of sales growth over the last 6 years. 30% sales growth expected this year (likely to beat), 44% last year, 59% year before. It may need new marketing channels to keep up the growth rate at these levels.
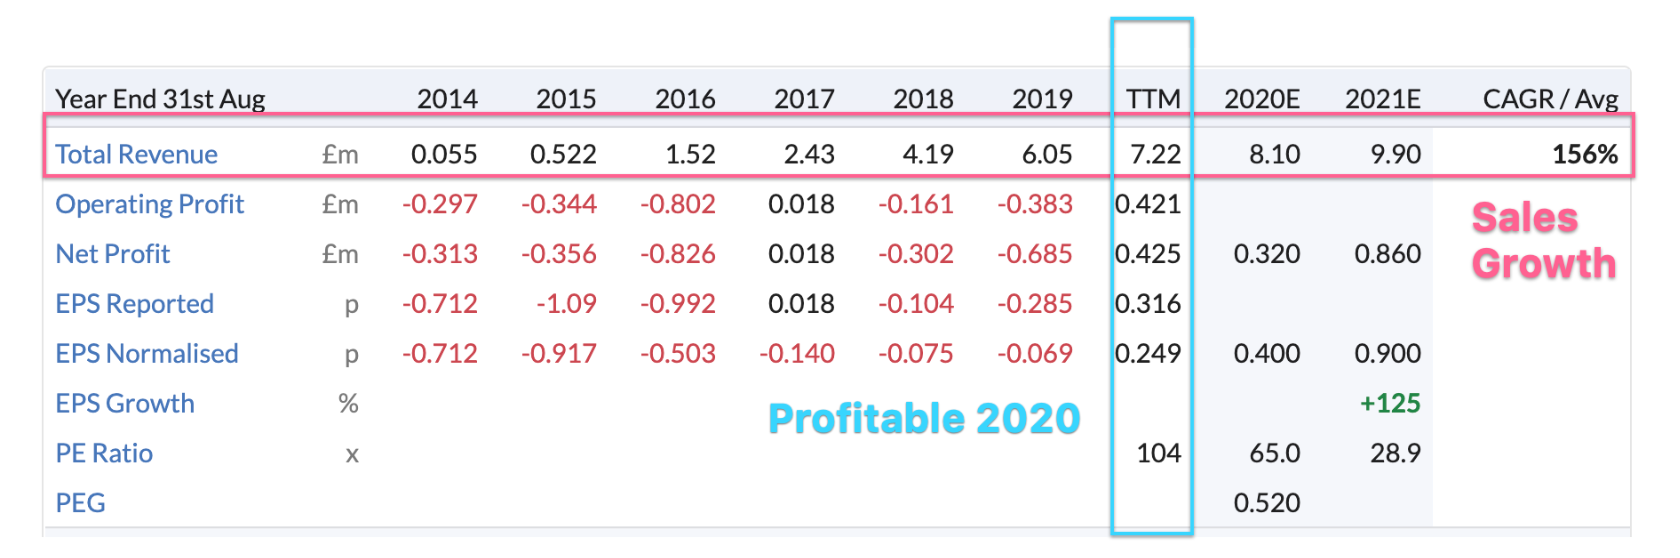
- It just turned profitable this year, and forecasts are for profits to grow strongly in the next year. But the current ROE, ROCE and operating margins are very weak. As a result, we can't yet find evidence of competitive strength in the financials yet, though this should change as the business grows. The house broker has previously spoken of the business reaching a 50% ROCE, but I'd be surprised if that happened soon as they'll need to invest heavily in marketing for growth, which could weigh down near term profits.
- Balance Sheet is very strong. It has no debt, and its financials are improving - the F-Score is good. The company has £6.6m in cash, which has grown over the last 12 months from 4.96m. The business model is very cash generative, though has been sitting on a lot of cash for the last 3 years after it floated.
- Share dilution... only really in 2016 and lastly 2018 when it raised £5m from institutions. It has been prudent, and still has most of the cash from that raise. I don't see it that it will need raise more soon - so the risk of further dilution is low.
- What is the ownership structure of the company, and do management or founders have significant stakes? See here
- Top 10 holders have 67% of the shares... it's fairly tightly held and liquidity is low - so retail investor demand may be the force that drives the price higher.
- David Massie Estate - founder/chairman - just died. He was instrumental and visionary in the company development. 25% stake has been partially divested to the Marlborough Nano-Cap fund.
- Jacqueline Daniell - she is the founder/CEO of Interhigh 7%
- Notably of the institutions who hold Premier Miton (Gervais Williams) is an owner. Though they reduced their stake in July.
- Top 10 holders have 67% of the shares... it's fairly tightly held and liquidity is low - so retail investor demand may be the force that drives the price higher.
Valuation
Relative Valuation
-
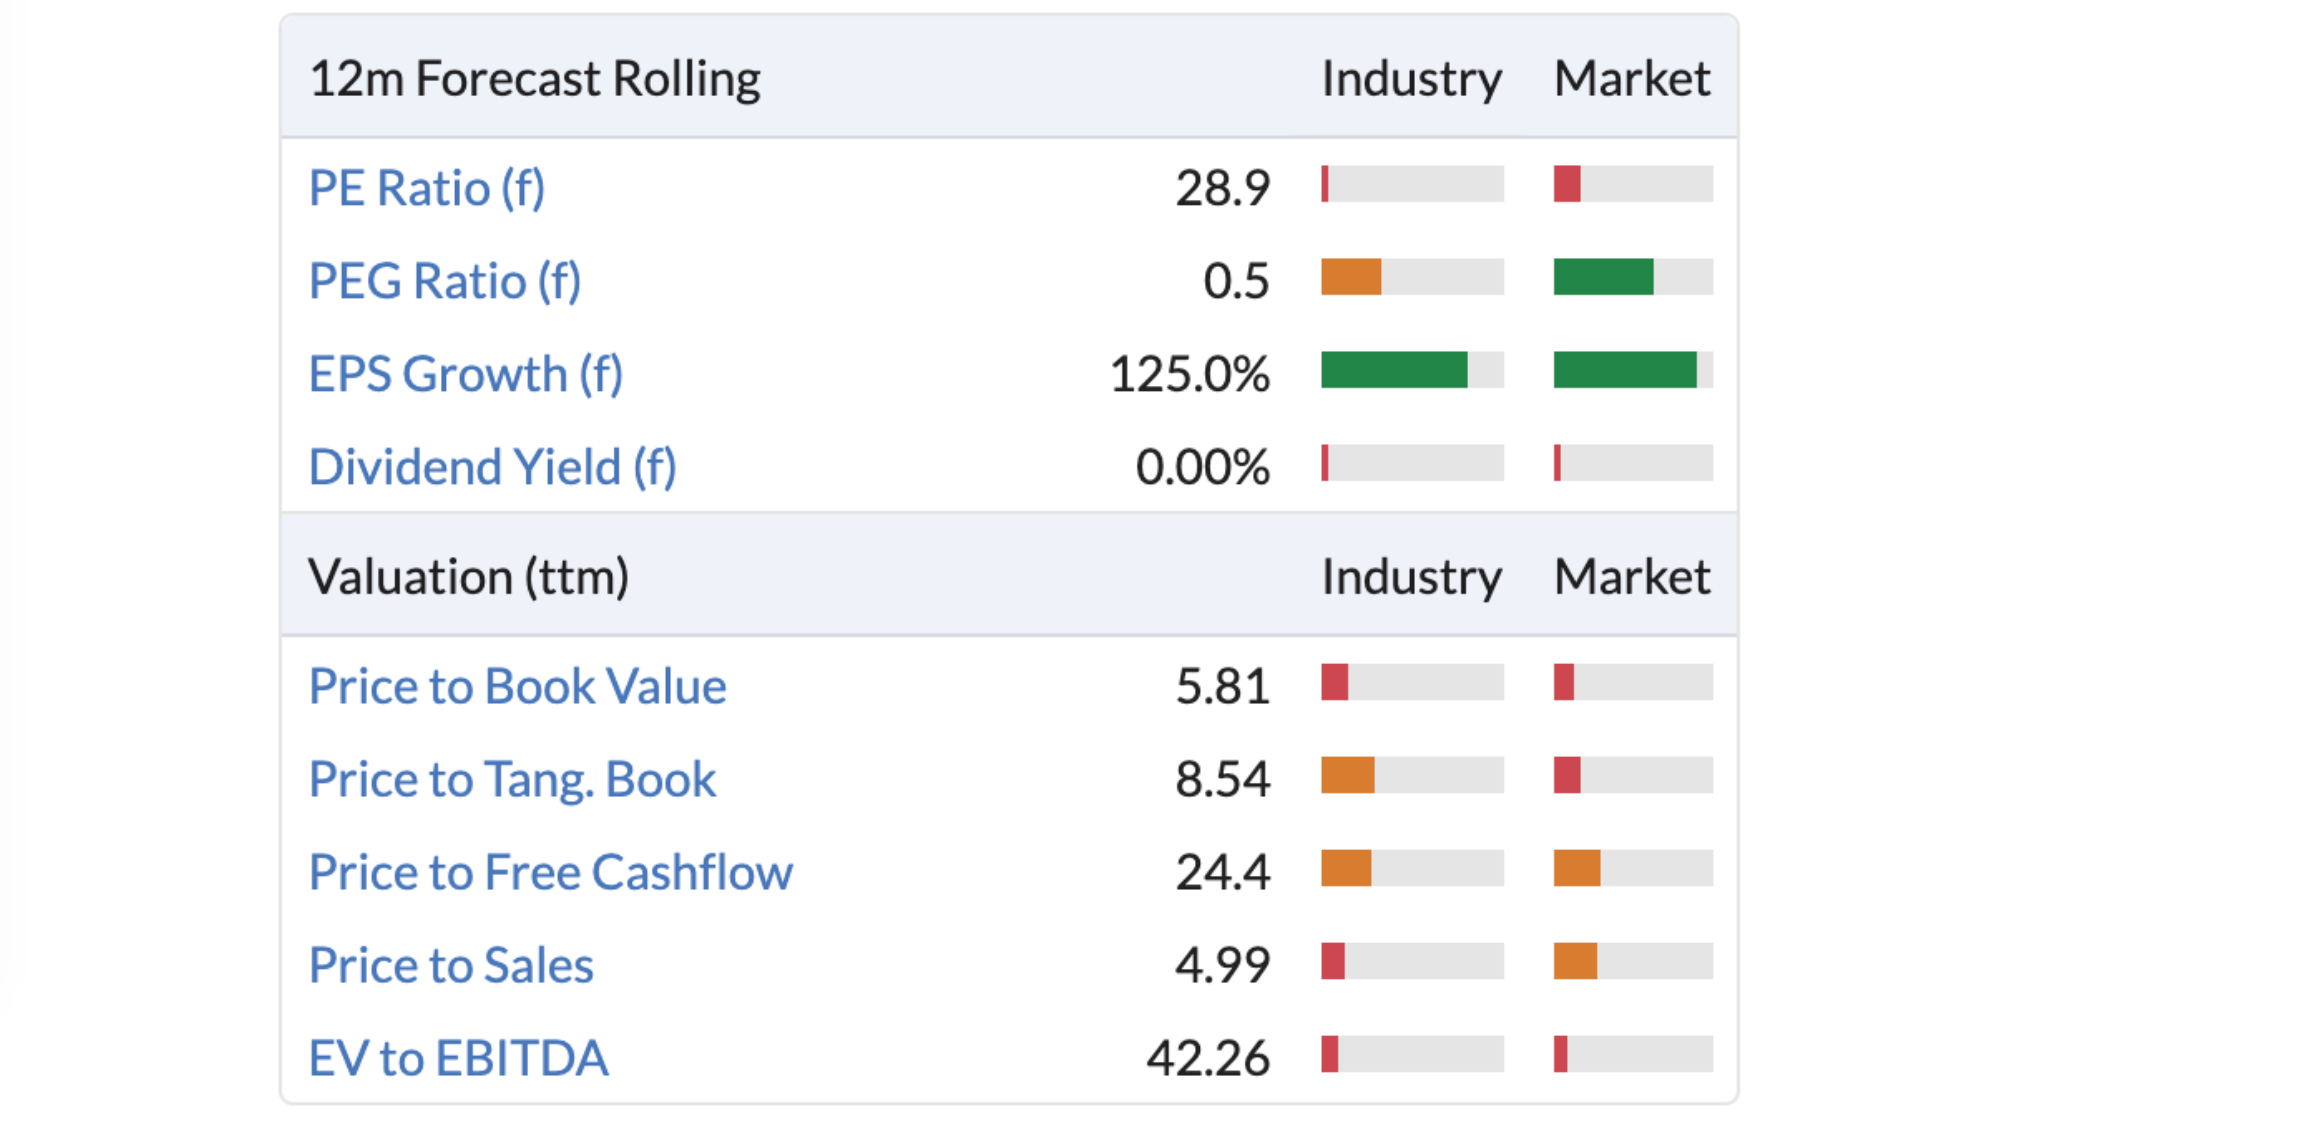
The company has a ValueRank of 16/100. This indicates it's currently expensive on historic data, though the growth and "high QM" nature of the stock is perhaps a justification for its premium rating.
-
The forecast PE Ratio 28.9x is expensive but it does have £6.6m in net cash. So the Enterprise value (removing the cash from the market cap) is only £29.6m - on which basis the PE ratio falls to 23.7x next year's earnings. If it beats estimates, it starts to look reasonably valued on a 1 year basis. If the company really can 4x its customer base as it is aiming to, then today's valuation will look good value in hindsight. The PEG Ratio is 0.5 which is a positive factor - i.e. growth at a reasonable price.
Intrinsic Valuation
- The house broker, WH Ireland's DCF valuation from the start of the year suggests a fair value for for Wey of 35p per share - which is 34% above the current share price. Read more broker notes on ResearchTree for more details.
Recent Trading
- The business has been performing strongly.
- 12th May 2020 - interim results "Turnover increased by 43% to £3.87m (2019: £2.70m)" Profit before and after tax of £215k. The house brokers raised their revenue forecast to £7.9m from £7.5m and raised their fair value assessment to 34p (was: 31p).
- Trading statement in July The company stated that group turnover is expected to be in excess of £8m for the financial year ending on August 31, 2020, an anticipated growth of in excess of 30% from the previous year. It is likely that the company will beat these numbers.
Trends & Catalysts
-
The recent trend in 2020 towards online learning is a big boost for Wey. The earnings and sales momentum has been strong and that should be expected to continue, given continuing lockdowns.
-
People's habits are changing and parental comfort with Zoom & online learning has made a big difference. We cannot underestimate how big an impact this may have on cultural behaviour going forwards.
-
There are a proportion of independent school parents who are extremely wary of paying excessively high fees for physical schools when they haven't been able to use them properly. Parents have had to cough up cheques over £5k(day)-10k(boarding) per term compared to Wey's £4k for a whole year. Meanwhile, many other parents are just plain scared of Coronavirus.
Breaking News Today are sharing a recent poll by Childcare.co.uk has revealed that 24.3% of parents are more likely to home school their children after the coronavirus pandemic is over.
-
-
There is a trend towards Government Accreditation and Regulation - Online Schools are currently unregulated as they are considered as home schooling. The Government recently consulted on an Online Schools Accreditation Scheme in 2019 in which Wey Education were highly involved. It's likely an inspection and accreditation program will be started, just like Ofsted. They want children, parents and local authorities to be assured of quality education and appropriate safeguarding arrangements.
- For providers, this would distinguish high quality providers from lower quality provision - which should be favourable for Interhigh.
- For parents, it would: provide reassurance about the quality of the curriculum and teaching, as well as safeguarding arrangements
Are there any catalysts could drive a rerating in the short or medium term?
-
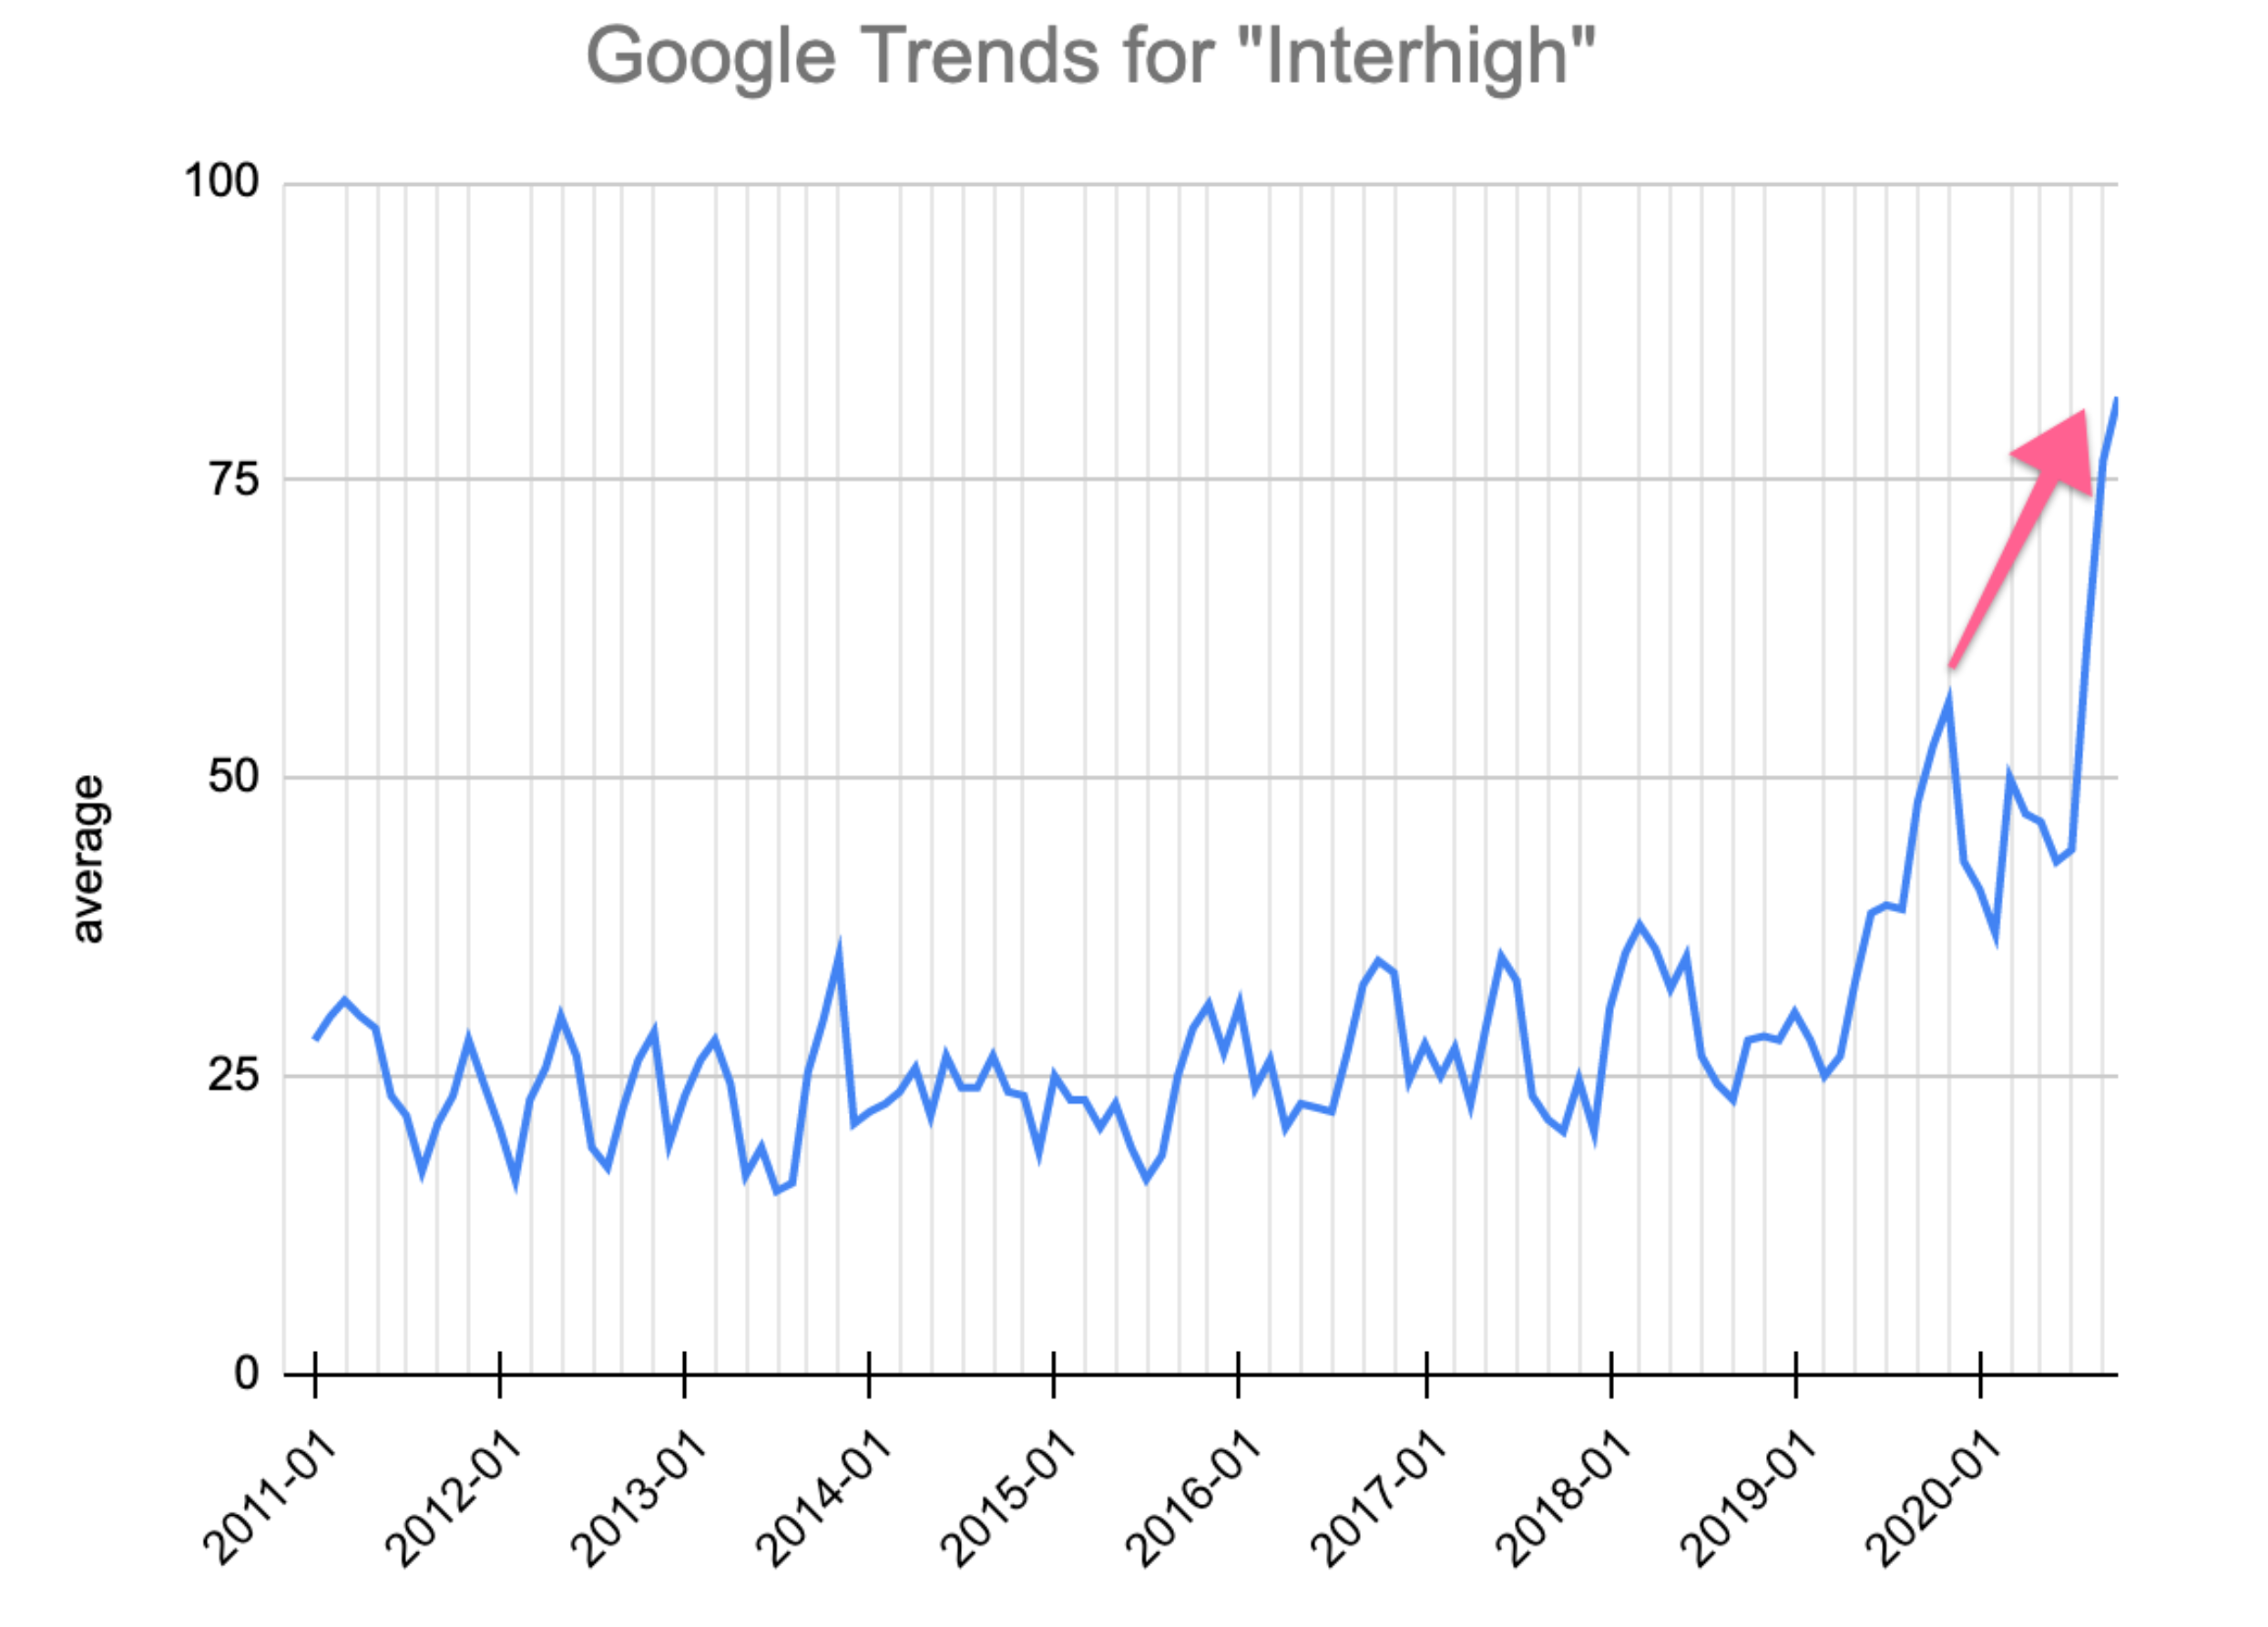
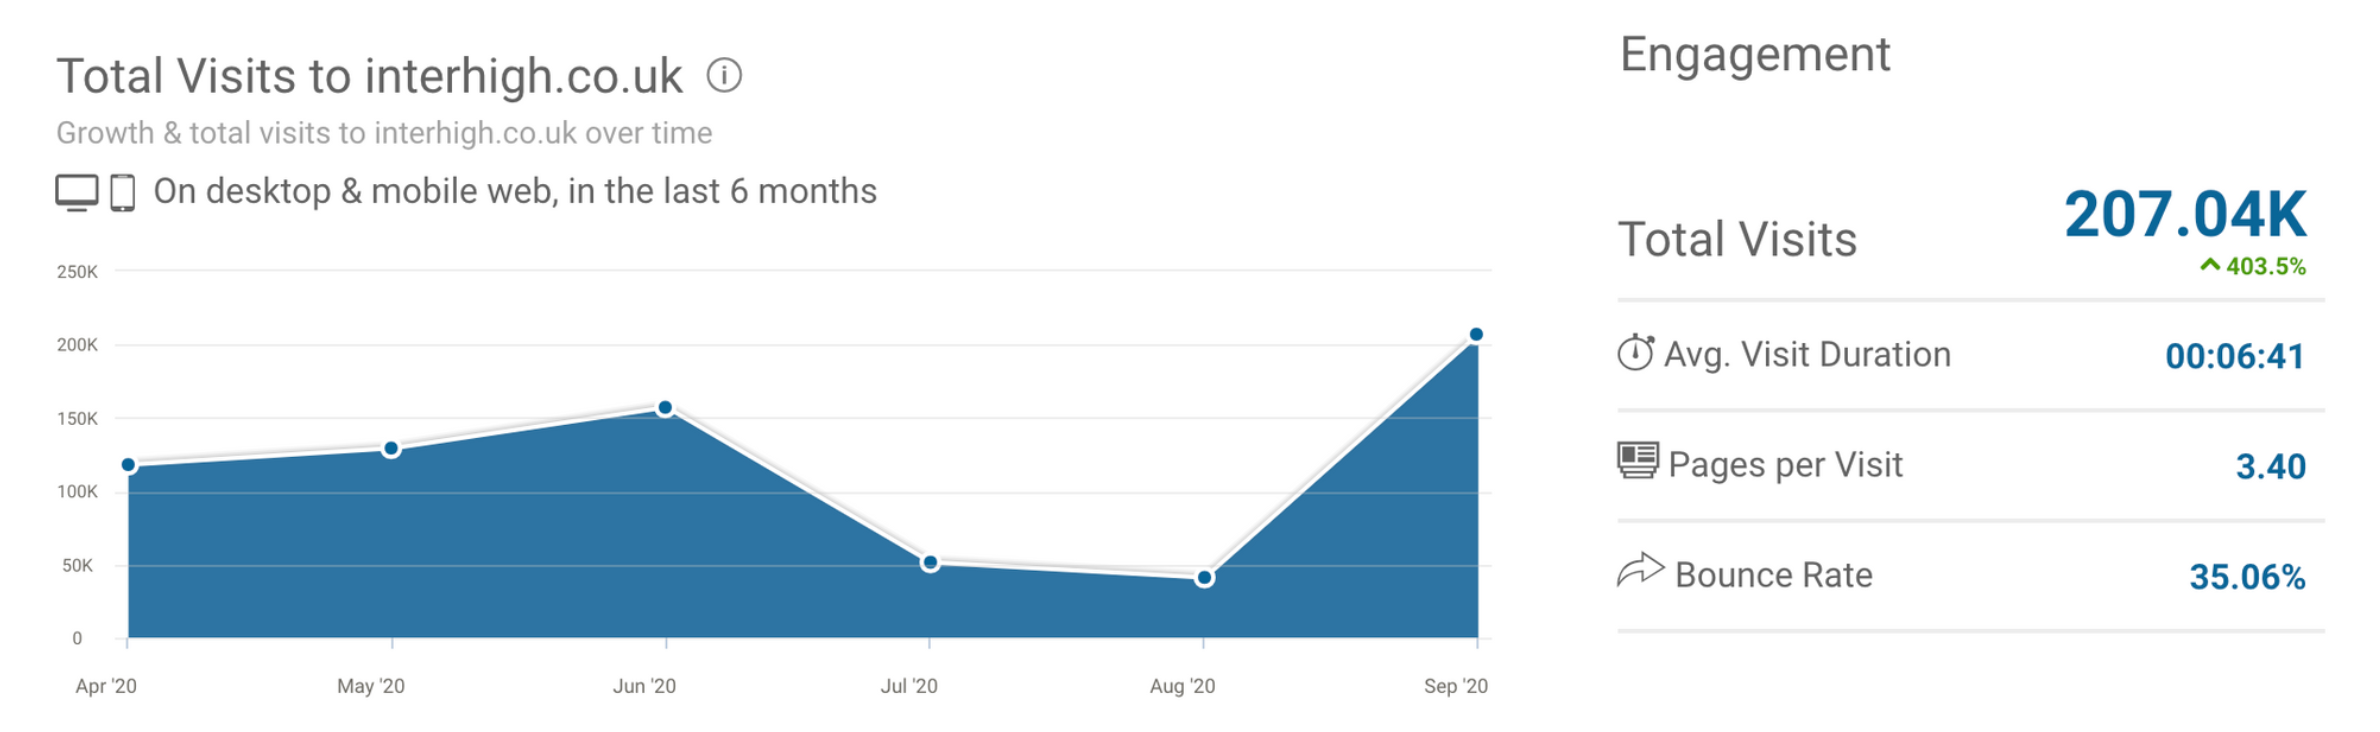
In recent months, the Investment Club has seen good results in backing up decisions by using alternative data sources to assess website traffic to small caps that have a significant online presence. There is evidence from Google Trends and SimilarWeb that website traffic for Interhigh has recently been on the increase. Even if this is overestimated, it does give backing to the view that recent sales momentum should continue into the next set of results.
The following chart is from SimilarWeb - the seasonal dip in the summer holidays is expected.
- It's possible this could be a takeover candidate for private equity or a larger group. I do think this company could benefit from expert guidance on how to seize the market opportunity faster.
What are the biggest risks?
- Valuation Risk - It is on a premium rating, and you could argue that this is just a school... so it shouldn't be so expensive. If it misses its growth targets, yes it likely will fall - possibly hard. Covid may prove to be a temporary boost rather than a secular change in trend. Brokers can be overoptimistic. Recent director sales don't inspire great confidence.
- Technology Risk - There doesn't seem to be any significant technology advantage here in spite of some "AI" noises which I am quite skeptical about. Everyone these days is on Zoom and there are plenty of virtual schooling tools out on the market.
- Market Risk - all schools now realise they can trade online, so serious competitors may emerge quickly. Other independent sector schools may start offering cheap online alternatives - although that does risk cannibalising their sales.
Sentiment
- WH Ireland is the only broker covering the stock and it’s research is sponsored and paid for by the company. As mentioned they have a 34p current fair valuation and you can find all their research on Research Tree. Their latest comment - 17th July 2020 stated "The business is trading ahead of expectations. Our raised forecast means that we expect H2-20E to continue the progress made in the very strong first half. "
- Private investor sentiment at the moment is a bit negative... due to some coordinated director selling early in the summer. Bulletin boards are full of private investors moaning about this and having half sold their stock. The academic research shows that director sales are far less predictive of future outcomes than open market director buys. There are always reasons why individuals need liquidity, and educational establishment operators are not know as excellent valuers of businesses.
- What would the person selling to us be thinking and who are they?
- Current sellers are profit takers who have doubled or more YTD... it’s got “too expensive”.
- Those who made losses in 2017 and have broken even - there is a lot of overhead supply as can be seen in the share price chart which could be creating resistance.
- There is a regime change under way where early investors get out and the shareholder base rearranges for the next leg.
From recent comments on the site, the community are quite skeptical about Wey Education. Please do add your voice to the debate if you have any good insights.
Disclosure of interest - I have held a personal position in Wey Education from 22p.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

29 comments
The Club today sold its position in Wey Education (LON:WEY) at 46p - an 88% return over 233 days.
Takeover... recommended cash offer. +40% today, and an 87% return for the club in just over 7 months.
Congratulations Edward. Is there a landing page for the Clubs investments? Thanks
Great result! Does the Investment Club have a policy for dealing with companies that are bid for?
We've a meeting on Tuesday to discuss this and new candidates. Our policy on sales is quite simple. We have 3 sell rules:
Good to see... "Wey Education announces that trading in the first four months of its financial year has been significantly ahead of budget and market expectations."
I have owned Wey personally for some time... and it's up about 60% since the Club bought too. I know how much pain parents are feeling at the moment.. and I think independent school fees are far too high for online learning. Wey continues to be well placed to pick up business - but I have to admit the valuation is looking punchy. I am a holder at these levels not a buyer.
Paul Scott has some cautionary comments re. VAT handling in the SCVR.
I don't really get Wey Education (LON:WEY) and particularly why it is should hold a high valuation as there seem to be a number of significant weaknesses that will either muddy growth path or create high costs to growth. I'm probably wrong and just can't see it (not uncommon!). I acknowledge that its a stock with a sweet narrative...too sweet IMO as it enjoys a bit of hype-ish support in the PI world and it appeals to the self-made self-motivated (dare I say occasionally egotistical and liking to broadcast) geek sorts that like to believe they can outsmart the market...or at least out trade the other suckers ;)
Counterpoints:
Instinctively to me Wey feels like a wrongun...just as you have 'tech' doesn't mean you 'disrupt' (and we all hate schools in some way and/or know teachers we think are a-holes so we can be very ready to believe the disrupt bit). I think I could keep on going with the above but I'll stop now.
There will be a durable market for a service like Wey and it will have some growth. But why would Wey 'uber' or 'facebook' this market? Its not really suitable to a dominant educational delivery platform (there could be dominant enabling tech of course for some). Wey are likely to face very stiff competition from better brands. Eton online if they chose to commercialise and scale would be able to charge at least 2x as much as Wey and still outpace them....if you go weird in education and have money you're going to go brand.
Sell Wey...you might not see the sidewinder coming and at its current price a doubt re model will take the price down hard and their ain't a lot of liquidity for anything but the smallest PIs. A stock like Rm (LON:RM.) is harder to like for a variety of reasons (inc the superb homegrown CEO moving on) but is much better structurally places to monetise innovation and change in education
(There's a lot I don't know re Wey and the above is a quick view rather than very informed)
Good insights @mojomoguz and welcomed.
As I mentioned in the piece...
WEY beat estimates, but not as much as holders would have wished for given the macro backdrop. As the valuation is at a premium, it's been marked down on very low volume.
I continue to hold. All stocks are speculative, DYOR etc.
It was a good note Ed....and I've just realised that any points were general rather than personal (I actually have Boros in mind as someone promoting it and I know the very nice and geekish Leo Investor is a fan).
I must admit I thought the stock was up 10% today and see it now down 20%! That's very surprising
I'll assume that's not intended as an insult, especially as you are more "geekish" than I :)
I wrote this today especially[1] for Stockopedia: https://www.stockopedia.com/co...
[1] until tomorrow.
Leo, I'm flattered to even by considered a geek...however I know that I fall short of such exulted status as I'm far too intellectually incoherent and lazy to attain such a status.
Whereas, you for me, are a top geek ;)
Ciao
@mojomoguz, I think I can answer all of the above:
On your last points, they don't claim to have tech and I've never heard anybody say there needs to be an Uber in this market - yes you need scale to compete effectively, but they have this and beyond that there is a very limited network effect. Liquidity is much better than many shares I own, and certainly adequate for full time investors - that is, people who have a portfolio and don't day-trade.
Thanks for your riposte...clearly much more informed than my fly by night negatives.
I'll think a bit. I have struggled with valuation versus what I can understand as the security and extendability of their franchise. My hunch remains (based on shallow analysis and thinking!) that they will need to iterate their business significantly in future to achieve greater scale. For example, hybrid physical and online. That said, maybe they don't need to worry about that until sales are significantly higher...more £50m than £20m though as limitations of £20m would be sensed fairly soon in market.
The receivables point was clarifying and reassuring
Very helpful scepticism, well argued and expressed. Thank you. Your views on Rm ( which I have held at times, would be greatly appreciated).
Wey Education (LON:WEY) has reported full year results. Sales up 38% to £8.4m and adj. profits before tax up 102% to £652k. It’s a strong beat vs forecasts... though not as much as I’d have liked. Cash has grown half a million too.
I wonder how a Covid vaccine will affect Wey Education (LON:WEY) forecasts, I note shares fell yesterday.
There's a very interesting "results preview" piece written by LeoInvestor (who is a subscriber) on his blog - about Wey Education (LON:WEY) - you can read up here - https://leoinvestoruk.home.blo...
This is a quote - my eyes nearly popped at the 3,000 figure for Interhigh - I'd be very surprised if the student numbers are that high - but we shall see.
" Judging by the level of staff recruitment, website activity and updated figures on home schooling, all indications are that InterHigh student numbers are exceptionally strong, with this article putting current numbers at 3,000, versus 1,700 disclosed in an open day in late January and my estimate of under 1500 this time last year.
However there are reasons to be cautious. Pupil numbers normally build throughout the first term before the flow becomes broadly evenly matched between joiners and leavers, but there is no guarantee the same pattern will continue this year. The COVID-19 health crisis may have driven parents to InterHigh out of desperation and these pupils may not stay as they have in the past. The new flexible Rolling Contracts available will also attract more temporary students, although pricing reflects this and in exam years the year-long commitment remains. An increase in fees of 10% (for a yearly contract) gives further confidence.
Accordingly I see InterHigh currently trading an exceptional 80% ahead of last year, with risk evenly balanced between the upside and downside."
Last year they reported around November 11th - so it's not far away. Those will be figures till the year end in August. I noted in my piece that the Interhigh web traffic numbers for September were very strong indeed.
Interesting but a couple of thoughts. I'm with #rogerphilp on this; they're having a reasonable run for obvious reasons, but when it gets (if it ever does) back to 'normal', what's their USP? That apart, you obviously don't think it's worth much (14 rank?), don't even take a stab at a figure and a momentum rank of 95 is baffling; it's not quite worth what it was in June. Where's the upside?
What would worry me here is the effect of a vaccine. If that pushes us all in the direction of health safety and feeling secure, why have the kids at home? For the next 3 months no worries. After that, not so sure.
Hi Ed,
I like the tone you bring to Stocko which is professional, informative, balanced and approachable. Personally, I don't like the style of SCVR ie Scott as it feels like a window for him to ramp holdings, where he declares them, and daily we see a barrage of abuse directed at anyone who says anything remotely opposing his view or simply to his disliking. Today he says he won't look at reader comments until his work is over basically bc it winds him up. Not exactly professional! SCVR is getting playground style. And even Twitter took action recently.
They're obviously trading very well at the moment. I'd be very surprised if they didn't smash that 2021 forecast. The level of operational gearing is the question here. Gross margins around 60% but how much additional marketing & IT spend will be needed for the extra volume?
I really like these write-ups, very interesting and a good learning curve on how to start to research companies looking to buy. I used to hold Wey Education (LON:WEY), however sold back in August for fear of it's toppy valuation. Good luck! Ed, is there somewhere we can see the SSIC portfolio?
Thx
An excellent piece, Ed.
It is interesting to reference a couple of points in your piece...firstly where you mention 2400 pupils at InterHigh, and also your thought that Forecasts could be beaten.
The InterHigh founder and CEO Jacqui Daniel was interviewed in June in an online Magazine called Muddy Stilettos (pasted below) and one eye catching quote was
"We’re always looking at new technologies and simulations! There are 3000 children taught by us at the moment and we expect 6000 by next year, so it’s a serious responsibility". https://muddystilettos.co.uk/k...
The 3000 number she quotes would also include their other business Academy21. Clearly if the Pupil numbers do increase at that level...even if it for Academic year 2021/2, then the group sales number could be at a different level altogether in a year to 18 months time. I also note from the Fees section of their website that Fees for the new Academic Year are +9.2% higher that last year...something you can usually only achieve from a position of strength with demand strong. If Sales were to outperform, the operational gearing is good...with Gross Margins rolling at c62%.
simso
I didn't realise they were targeting 6,000 next year. That would be quite a feat.
Good spot, thank you. And thank you for the article Ed. Wey Education (LON:WEY) has been on my watchlist for a while but I just feel the valuation is too high for a strategy which is about aiming to be merely the largest secondary school in the UK - and judging by the directors selling they may have thought that too! Academy21 might be picking up some nice business at the moment from local authorities to help children who have fallen behind, so that is worth watching. But for now I'll sit comfortably on my fence.
I am a parent of an autistic child. There is a very wide range in academic ability on the autistic spectrum from children that do not speak and communicate with difficulty, to those with low academic ability , to those with very high academic ability in the top 1% of children. There is a real issue in the provision of special needs education for autistic children in that many of the specialist schools do not provide for the academically able. I have given Interhigh as an option to several parents in parent forums looking for a good academic option for their autistic child(although I could not speak for the quality not having used them) I also think that local authorities might start to consider using Interhigh for certain special needs children as the £4000 price is compelling compared to the price for many specialist schools. It will have to be navigated carefully though as there might have to be some other specialist support provided onside but I am sure that this could be worked on with Interhigh. I am invested myself as I see this area as high growth and the price is very good value for a lot of parents who for many reasons look to see if there is an alternative to conventional schooling for their children
Hi Ed, one I been keeping an eye on for a while.
How did the staff voting go on this one?
I noticed that section included in the novacyt pitch but omitted here? Would be good if it was included as part of one of the sections...?
Yes of course... it wasn't clear cut.
Hi Ed, I am not an accountant so digging into accounts is what I do as my final check. Stockopedia is invaluable because of articles like this. However, if you want to find out how a company is doing ask their competitor. Who are their competitors and how are they doing? Turn that around and ask who would benefit from buying them if they are so good Rm (LON:RM.) but who else?