StockRank Movers - May 12th: The Maiden Dividend Anomaly

The American business magnate, John D. Rockefeller once said: 'Do you know the only thing that give me pleasure? It's to see my dividends coming in.' Dividends are of course cash payments that companies pay out to shareholders on an interim or annual basis. All other things being equal, a company that pays a dividend could, in theory, be more attractive to many investors. This week we explore whether investors can make money by investing in high StockRank stocks that pay maiden dividends.
The Maiden Dividend Anomaly
How does the market respond when companies announce maiden dividends? Research by academics Michaely, Thaler and Womack (1995) looked at the share price performances of companies that initiated - or omitted - the payment of cash dividend payments between 1964 and 1988. They found that:
- The returns for firms initiating dividends were 7.5% after 1 year and 25% after 3 years of the dividend announcement;
- The returns for firms omitting dividends were -11% after 1 year and -15% after 3 years of the dividend omission.
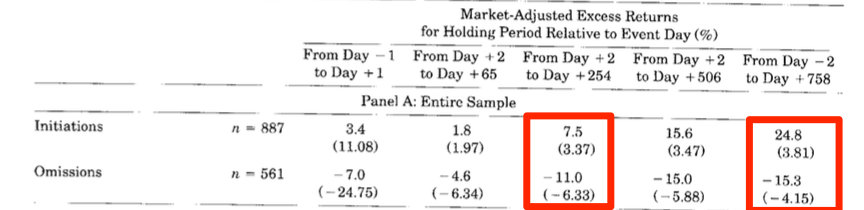
These trends may in part be down to something called the 'clientele effect' - the observation that investors tend to be attracted to different types of companies. A stock that introduces a dividend will naturally broaden its appeal to income investors. For example, institutions could have a preference, or even a requirement, to buy shares in dividend-paying companies
More anecdotal evidence suggests that companies with improving fundamentals may be better placed to support dividend payments. This has been particularly evident during the past five years in the housebuilding sector, with companies like Persimmon and Barratt Developments quick to respond to improving conditions by rewarding shareholders. Another construction firm that's set to notch up its third consecutive year of dividends is Redrow….
Redrow (RDW)
Redrow (RDW) is a relatively new dividend payer. 2015 is expected to be the third consecutive year that Redrow pays a dividend (6p per share). The company paid out 1p per share in 2013 and 3p per share in 2014. Redrow has notched up dividend payments as fundamentals have improved across the board. Over the last twelve months:
- Gross profit margins have risen from 19.8% to 22.5%;
- Operating profit margins have risen from 15.9% to 17.3%;
- The Return on Capital Employed has risen from 14.6% to 17.7%.
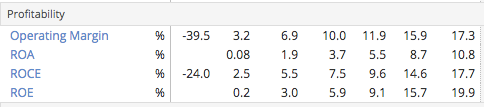
This has been supported by rising house prices. Redrow's recent financial papers reveal that although materials and labour costs have risen, this has been offset by house price inflation. Whilst overheads increased in absolute terms, they reduced as a percentage of revenues.
As Redrow became more profitable, the company's StockRank gradually drifted upwards (see chart below). Notice how the StockRank jumped in February 2014 and September 2014. The StockRank shot up as Redrow released:
- Annual results on 2 September, revealing that earnings had risen by 89% while revenues had risen by over 40%.
- Interim results on 27 February, showing that revenues had grown by 40%.
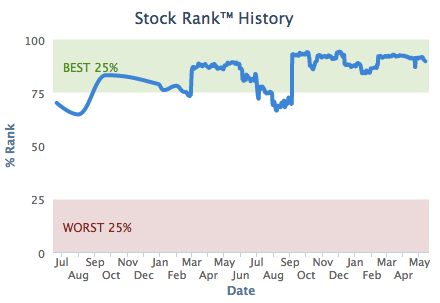
The market as well as analysts are becoming increasingly confident about this company. Redrow has beaten the market by 35% over the last twelve months. Over the same timeframe, the EPS estimates for this company have risen from 33.9p per share to 41.8p per share (see image below).
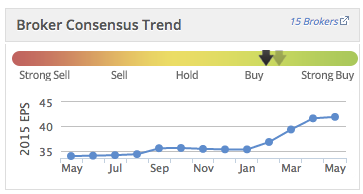
It is also interesting to note that the company's share price has risen by 7% since the general election last week. The Help to Buy scheme was introduced by the Conservative Government back in 2013. Redrow's annual report attributes much of its success over recent years to the Help to Buy scheme (see here). It is therefore most plausible that the market responded favourably to the Conservative Party's victory last week. More good news came on 11 May, when the Bank of England announced that it had kept interest rates at record low levels (0.5%).
Conclusions
So Redrow is an interesting case in point. Over recent years, the company has become more profitable, brokers are upping the numbers and the company has resumed dividend payments. Are there more opportunities out there? Investors who want to learn more about dividend investment strategies should check out our free ebook, How to Make Money in Dividend Stocks. Stockopedia subscribers can also screen the market for high dividend payers using our Income GuruScreen strategies, which can be found here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
7 comments
Hi,
Thanks for this.
Cisk: Interesting comment about interest rates. The BoE has suggested that interest rates will rise when the economy is stronger, so the headwinds created by rising rates may at least partially be offset by rising demand. The Conservative Government also seems to be committed to housebuilding projects (see image below - Cameron on the right. I think that might be Nick Clegg on the left). This might create additional tailwinds.
Also, the above paper suggests that maiden dividend payers outperform for two or three years after this first payment. Redrow falls within this timeframe, as 2015 would be the third year that company pays a dividend.
Best,
Alex
Hi Alex, the research about share price performance re: maiden and cutting dividends is very interesting, although the title of the post is somewhat misleading - Redrow, having reinstated their dividend 3 years ago, could hardly be called a maiden dividend payer now. Would be very interesting to see more recent examples of dividends being reinstated and abolished, and the impact on share price performance.
Personally I have little interest in buying shares in house builders, as my investing ethos steers me to buy shares in suppliers of the shovels than the miners themselves - so companies such as Travis Perkins (LON:TPK) and Headlam (LON:HEAD) are of far more interest to me, as I think there is a trickle-down lag which will positively impact these companies. Also I believe there are mounting headwinds against the housebuilders - a rise in interest rates being the most prevalent.
Those of us with memories going further back than the current 0.5% base rate realise what an anomaly the current situation is - although I've been thinking this for several years now!
Interesting article. How were you able to chart the historical stock rank? I would like to be able to do this for other stocks.
Regards
Peter
Have you checked directors remuneration? One director appears to have made over a million in one day's trading on 16 April.
Hi,
Thanks for the feedback.
paulr18827: Companies with improving fundamentals are of course better placed to support dividend payments, so your point brings us to a wider discussion: Is the Maiden Dividend anomaly merely a by-product of the Quality effect, whereby good, improving stocks beat deteriorating, junk stocks...? In the case of housebuilders, I agree that share prices can mainly be explained by improving fundamentals and growth. The dividends are merely a by-product of this growth.
Sully8786: You may want to check out these GuruScreens:
Earnings Upgrade Screen: http://bit.ly/1JmK3sn
Earnings Downgrade Screen: http://bit.ly/1E4XQ2u
I hope this helps? Do please let me know if not.
Alex
Hi Alex,
Nice article, thanks.
Are we able to screen for analysts earnings upgrading / downgrading?
Regards,
Sully.
Good article, but comparison should be with other house builders, such as persimmon, bellway, barratts etc, rather than general market although that too is important. i agree that with political parties on all sides promising housebuilding this company like others have reacted favourably. I do not think dividends in this case are the driver, just a welcome bonus.