Sylvania Platinum SLP. If I hold, there will trouble if I sell it will probably double.

Sylvania Platinum £SLP. If I hold, there will trouble if I sell it will probably double.
Sylvania Platinum (LON:SLP) has had a sharp increase in share price and becomes a large part of my portfolio (2nd largest holding). I have been contemplating if I should continue to hold or take some profit by selling at this point with Sylvania Platinum (LON:SLP), announcing its interim financial results for the six months ended 31 December 2020 tomorrow (22nd Feb 2021).
Buying Sylvania Platinum (LON:SLP) seems straightforward on valuation grounds at 37p in back July-2020 but selling seems more problematic as the valuation still looks attractive. I’ve done a bit more work to determine if I should sell and at what price to sell some of my stake in the company. Here some questions and thoughts on the matter.
1. Why has the share price and valuation risen?
The Sylvania Platinum (LON:SLP) Share price and valuation have risen hand in hand with PGM (Platinum Group Metal) and more specifically the explosion in Rhodium commodity pricing. Back in 2017, the Rhodium price was $900 TOz greater than $22000 per TOz today. Sylvania Platinum (LON:SLP) revenues attributable to Rhodium have increased from 12% in 2017 to an estimated 68% for FY2021. EPS in 2017 was 3.59p and my estimate suggests 27p for FY2021.
2. Is the raise in Rhodium price just a bubble or sustainable?
Well, what’s driving demand?
Rhodium price climb to above $22,000 an ounce is being driven by new regulation from the auto industry due to increasingly stringent emissions regulations globally. Car companies are using more rhodium to meet tougher clean-air legislation. There is a link and world map below related to the new regulation in different counties.

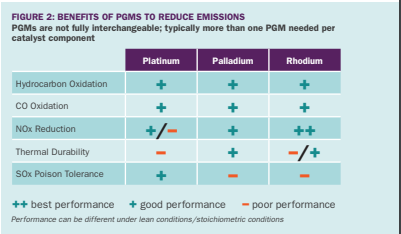
Rhodium has an important role to play in NOx reduction and an increasingly important requirement within upcoming world regulations for automotive manufacture. There is both a plus and a minus for platinum which is related to whether the vehicle is running lean burn, with a higher oxygen/fuel ratio in the outgas (diesel engines), versus stoichiometric burn, which we have in a typical gasoline engine. While in a diesel engine, platinum supports NOx reduction and is a key component, a gasoline engine running under stoichiometric conditions does not favour the use of platinum alone. Rhodium is by far the best performer in NOx reduction, which is why it will be a critical precious metal going forward. With new standards Rhodium content within catalytical converters in likely to increase by 50%. There is a useful link and table as how PGM is used in emissions reduction below.
http://www.lbma.org.uk/assets/Alchemist/Alchemist_92/Alch92Josey.pdf
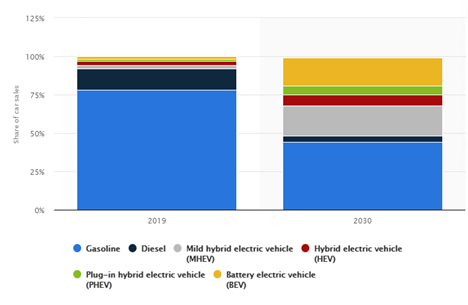
Gasoline and Hybrid XXEV automotive fuel types are set to dominate market requirements for the foreseeable future. Even by 2030 they still are 75% of the market. Rhodium content within catalytical converters is set to continue to rise with more stringent regulation. I included a link from Statisca data and their table showing the share of car sales by fuel type below.
https://www.statista.com/statistics/827460/global-car-sales-by-fuel-technology/
3. Won’t companies just mine more Rhodium?
The lack of primary rhodium mines will continue to be constrained and limit the potential for supply growth. Moreover, the current major PGM projects under development or investment consideration are all relatively low rhodium. It’s been suggested it might take some 5 years for new supply to come to market. (see link below for more information).
https://www.mining-technology.com/features/rhodium-on-the-rise/
Trading economics forecast suggest high Rhodium prices are set to continue for some considerable time. See link and graph below.
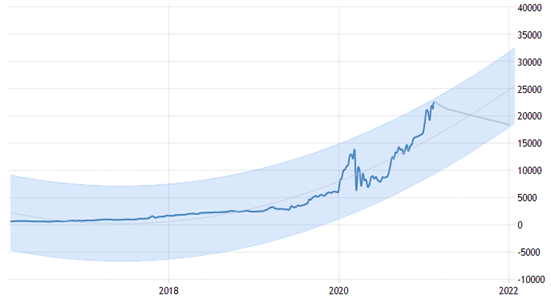
Graph : Rhodium pricing and Forecast from trading Economics
So Sylvania Platinum (LON:SLP) valuation for the next few years is very dependent on the Rhodium price and I’ve model 3 scenarios.
1. Rhodium prices are in a bubble and fall as quickly as they rose back to $1000
2. Rhodium prices stabilize at a new normal price of $15,000-$25,000
3. Rhodium prices continue to rise to $100000 as suggested by some commentators
1. Rhodium prices are in a bubble and fall as quickly as they rose back to below a $1000
Forecast assumptions for Rhodium prices, average basket price, and production are provided in the table below.

Valuation Forecast
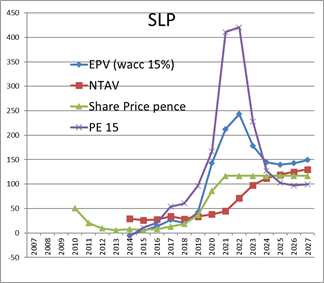
If this is what happens the fair value looks set for 140p by 2025.
2.Rhodium prices stabilize at the new normal price of $18,000
Forecast assumptions for Rhodium Prices, Average basket price, and Production are provided in the table below

Valuation forecast
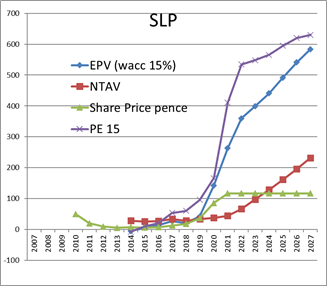
If this is what happens the fair value looks set for 500p by 2025.
3.Rhodium prices continue to rise to $100,000 as suggested by some commentators
Forecast assumptions for Rhodium Prices, Average basket price, and Production are provided in the table below.

Valuation forecast
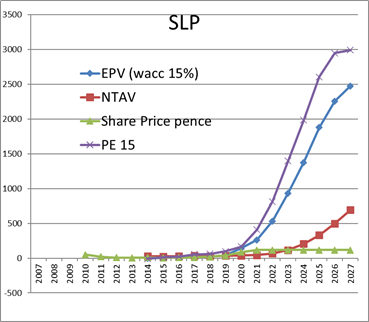
If this is what happens the fair value looks set for 2000p by 2025.
So what should will I do with my own Sylvania Platinum (LON:SLP) stake within my portfolio.
For now, it’s my second largest position and scores maximum points on my ranking system (ranks no 1 out 300 plus shares evaluated), so will continue to hold, as I believe scenarios 2 and 3 appear more likely than scenario 1.
I hope you find this useful and as always DYOR
BSV
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
49 comments
I invested £7,000 at £0.37.
I sold enough at £1.20 to repay my original investment. I will leave the rest to run for the time being.
SLP is very liquid upto £14K .Feel anybody who holds a sizeable stake above £14K in SLP should consider diversifing part of their holding into the very similiar Tharisa PLC
Excellent analysis - thank you. Like you the decision was easy at my entry point of 42p and the uplift now makes Sylvania Platinum (LON:SLP) my biggest holding in my portfolio. On all the standard metrics that I use such as ROCE, free cashflow, net debt, cash on the balance sheet etc, they all seem to be going in the right direction at the current metal prices. New mines take a long time to come on stream and as you say, demand is set to stay strong or grow in the near to medium term. A useful dividend completes my reason for holding for now.
Thanks again for your initial post BSV and everyone else’s input like most on here I have done very well out of this and it is my second biggest holding and I don’t have any plans to sell down yet with the squeeze In rhodium supply and a continuing deficit due to laws being imposed across the world on car emissions I honestly can’t see how the price of rhodium does not stay at these elevated levels there does not seem to be a lot of speculative price action it seems to be purely driven by demand does anyone see it differently?
Hi BSV,
I might be getting my excel cells backwards so can I check my basket price calc?
PRILL from their presentation is 63.3% Pt 23.7% Pd, 12.7% Rh and 0.2% Au
Using current prices of $1,129.75 /oz for Pt, $2,338.96 / oz for Pd, $29,200 / oz for Rh, and $1,700.91 / oz for Au then I get a current basket price of $4,981.27 / oz.
H1 value was $3,184 so H2 is going to be somewhere north of the $3,800 they expected. Not for the full 6 months but certainly for a good 50% of it assuming the price holds till June.
Thoughts?
(I hold btw)
Found my notes from the investor call:
2021 estimate for EBITDA is ~$120M based on a basket price of $3,807 with $1,169 /oz for Pt, $2,321 / oz for Pd, $20,000 / oz for Rh, and $1,828 / oz for Au.
According to their slides if the basket price rises by 10% then its more like ~$130M. If the Rh price keeps anywhere near current levels then something like $150M+ EBITDA if the Rh price holds (or grows) till June.
Liberum's estimate for EBITDA is $147m for 2021.
Thanks Slopsjon... nice my maths checked out.
Hi Will,
Your calculation is correct for the spot price.
My calculation is based on an average basket price of $2880 for FY2021 for Sylvania Platinum (LON:SLP) for scenario 2. Scenario 2 looks very conservative now and we are clearly in the realms of scenario 3 now.
BSV
What I thought too BSV... at this rate Rhodium might reach the heady prices of HP printer ink....
Seriously though, IC pushed the stock again on Friday with a raised target price of 180p. I am guessing that the trading update in July will mention stellar results so it'll keep on this upward trajectory until then with some pauses along the way. Then a final dividend to account for the surge in prices plus an expanded amount of CAPEX for their own mining operation.
Who knows how long the Rh price surge continues but lets hope it settles around $20K / oz for a while.
There is a very good relevant article in today's investor's chronicle (March 5). Simon Thompson rates SLP as a strong buy
Excellent, Simon seems to have an article on it in every other edition.
SLP currently qualifies for no less than 11 Long screens on the stocko report... so it must be doing something right. (I hold)
Yeah I couldn't find the edit on my post to correct this, I did post underneath it.
It's still a significant amount of money for the more modest vehicles.
I was wondering how there could possibly be £180,000 worth of Rhodium in a car retailing for £30,000.
I've just read an article about the increase in the theft of Catalytic Converters because of the ever rising price of PGM's, in older cars they were apparently used in greater amounts.
Today the price of Rhodium alone is £29,000/oz, I read that new cars typically have 2 to 6oz in the Cat Converter, how long can they go on using it when it adds such a huge amount to the raw materials of the car?
I understand that there is currently a deficit of Rhodium but with the ever increasing price will the manufacturers have any choice but to look for alternatives?
Rhodium is priced in $s, so it's $29,000 oz.
It's 2-6 grams in a catalytic convertor not ozs.
That's still about £750 per g - so £1500 - £4,500 for a convertor. That's a big part of the cost of most cars. Top end of that is more than my reliable and entirely suitable for my needs, 10 year old VW is worth.
More than my car is worth, so if someone nicks the cc it is a write off?
Just checked online and for my car it's about £180, so something does not tie up.
I do know someone who had his nicked last year.
£SLP
From what I've read the Rh content is about 0.3g and increases to 0.45g for the new regulation for automotive, that a 50% as new regulation becomes the legal requirement. As 80-90% of Rh use is expected for this automotive industry and mining can't increase production for 5 years there a real supply-demand imbalance that is only going to grow. There are no speculative markets or ETF's for investors to speculate on Rh so I see no bubble here or reserves that could be released into the market.
So my own thoughts are Rh price is being rerated higher and the new price is here to stay for some considerable time.
I could be wrong so as always DYOR and decide for yourself before investing.
All the best
BSV
I did come across this db Physical Rhodium etc ETF.
Good spot
BSV
Baird Gold sells physical rhodium bars for speculative purposes.
I worked 10 years ago in the IT section of the Honda factory in Swindon. I was told that the catalytic converter was by some distance the most expensive part that Honda bought in.
Great reply. Sounds like a promising hold.
Sorry 2-6g not ounce in the Cat converters! Damn how do i edit a post on my phone.
https://matthey.com/en/news/20...
Thanks, Bullhead,
Excellent report from J.M., Probably the most reliable source of information on PGM markets
BSV
https://www.investormeetcompan...
Thanks very much for your hard work BSV and all the other useful comments the presentation by the company confirms what you say a majorly of their earnings come from rhodium
Did any one else watch the presentation and question answering by CEO and financial officer on investormeetscompany today at 4pm was very interesting if you register it’s recorded on there
Also johnso Mattheys has some useful info on the continued deficit in rhodium due to demand from the autocatalyst market
I watched the Investor Meet Company presentation as well. I thought that the CEO & CFO both came across well. Good to see that they acknowledge the tail wind from metal prices but they have a good point that the company has been well positioned by the management team to benefit. The slides are also downloadable from the company website. Rhodium comprised 59.5% of the H1.21 revenue.
It was also interesting to hear that there is 8-10 years of profitable life left in the current operations and that there are further exploration activities underway to potentially extend further.
Yep totally agree was also informative what the CEO said about how they are improving their original extraction methods which means that material that wasn’t viable now should be which could extend the life of each site by another 2-3 years
Thank you BSV. One point I don't understand from the earnings this morning - no doubt my ignorance.
Average selling price is $3184
Amount produced: 36,355
Price*Amount = $115 Million but revenue only = $77 Million (plus a couple of extra bits)
This implies that they don't get the full price for what they produce - hedging? Allowing for further refining by the buyer (I note the price is "gross"?)
The difference is enough to make a difference for valuation purposes so does anyone know?
Many thanks.
Yes, that is correct actually revenues are 20% less than market rates x product. My model does take account of this with year-end revenues predicted for all 3 models. So my 2nd model implies a year-end revenue of $180M.
I not sure the reason why, but your understanding is correct.
BSV
Not sure if it applies in this case with Sylvania Platinum (LON:SLP) but it may be down to whether their sales are made FOB (free on board) or CIF (cost, insurance and freight) basis. In the former case the buyer basically takes the goods at point of sale, in the latter it is the seller that picks up the cost of insuring and shipping the goods to the buyer. The turnover figure could well be based on the gross price while the net revenue could be CIF. Freight and insurance can be quite high especially for goods travelling long distance or from inaccessible extraction points so it could well be the reason in this case.
Thanks both - I guess we are all still speculating then :-). I will ask the question at the call this evening if they don't answer it in the up front presentation. For the moment for valuation purposes I am going to assume $81 million ($77 million plus the by products) and same margin as in H1. For me, although it is very interesting to see the scenarios, the metals market moves so fast, I am not going to look beyond this year for valuation purposes right now. Gives an EPS of less than the current broker expectation on Stockopedia but still a very compelling hold for me.
Liberum: Sylvania have declared a one-off windfall dividend of c.5.2 cents pers share, 27% above our estimate of 4.1 cents. We expect a final dividend at the full year results of 4 cents, giving a combined yield of 6.4% in 2021. Sitting with $67m of cash and generating $155m of FCF at spot prices (35% FCF yield), with no major capex commitments, dividends look set to rise materially going forward. Basket prices hit a new record high today of c. R65,000/oz, and whilst this would normally make some investor nervous, we believe that the fundamentals for rhodium are solid on a three year view (see here). Top pick in mining." Target price 200p.
I was looking at rhodium price history, why did the price collapse in 2008? Price fell from $10k to $1k.
Not sure Tharisa (LON:THS) is much different from Sylvania Platinum (LON:SLP), I hold both but have sold some Sylvania Platinum (LON:SLP), I may buy back if price falls back, sold out of Jubilee Metals (LON:JLP).
You may want to look at Sylvania Platinum (LON:SLP) share price chart for around 1 year ago, it can double and halve in a short time.
I top-sliced before the results on Monday for reasons which you haven't mentioned in the article.
They have the ability to massively disappoint with the dividend, as they did last year. They mentioned, at the time, they are "considering" a metal price dividend payable in Q3 (super profits on Rh) but there were lots of vague words. Liberum have worked it out for them in recent notes - but we'll see if they follow through.
I think the PMG boom will continue, but I worry about the cash hoarding mentality here and I've switched some funds to Tharisa (LON:THS) .
Phil
(P.S. You make a very good point - Platinum and Paladium are essentially irrelevant at the moment to Sylvania Platinum (LON:SLP) , Tharisa (LON:THS) and Jubilee Metals (LON:JLP) ,Rhodium swamps them from a revenue perspective. I think Sylvania Platinum (LON:SLP) 's basket is now 70% Rhodium by revenue.)
Edit : GB crossed with me making a similar point.
I top sliced 15% last week @120, for two reasons, Sylvania Platinum (LON:SLP) is too large in my portfolio >35%, and if the special dividend disapoints which I think it will, the price is probably going to drop sub 110.
At that point, I'll probably buy them back, like you it's number 1 against my criteria by a huge margin, and cannot see the price of it's commodities going south any time soon.
Sylvania Platinum (LON:SLP) today's half-year results read well. A special dividend 3.75p. Also, share buybacks is the best return of capital to shareholders when the share price is low.
BSV
I don't understand the point re special dividend: they could either give it you or not: if they do, you have some more pounds in your pocket, if they don't, the money is in the share-price. No net gain/loss either way.
I think Special implies a one-off payment. If it was final or interim then there would be an expectation that it would be paid every year.
All the best
BSV
Here is the link to the event this Monday Sylvania will be featured on the MelloBash which starts at 8.45pm
https://www.stockopedia.com/content/mello-monday-featuring-stephen-english-jack-brumby-amp-graham-neary-766509/
Thanks for your efforts. Sylvania Platinum (LON:SLP) is being appraised at Mello's BASH (Buy, avoid, sell, hold) so I'd pay the £10 to get the opinion of the board. Have you looked at Tharisa (LON:THS)? Imo it offers more value and has its own ore so is not reliant on others. Maybe worth top slicing and taking a position in Tharisa? Although you would still be exposed to PGM spot prices and SA polital risk
Yes an excellent suggestion, I've looked at Tharisa (LON:THS) and added part to the portfolio also. I estimate 37% of FY21 revenues to be Rhodium, so the Rhodium upside is a little more limited, but the down-side is less risky as you've suggested. Still feel Sylvania Platinum (LON:SLP) is a cleaner bet on Rhodium price expectations
Tharisa (LON:THS) valuation forecast is provided below.
BSV
I did similar recently with £THS I also like the fact that it produces Chromium, which large miners are reducing the supply of. So potential for price increases with the reflation post Covid. It also has spare capacity in both Chromium and PGMs and plans to increase its annual production. This additional production is also at marginal cost now, as its big mine restructure and capital investments have already taken place.
Really good information thank you, Martin.
BSV