TBC Bank: move over Nu Holdings?

My investing strategy is nothing special – I look for signs of relative value and growth at a reasonable price and then, if everything goes to plan, sell into strength (hopefully not too soon).
UK-listed banks were a notable part of my portfolio until recently. Clearly oversold in the rate-hiking post-pandemic years, and especially during the non-existent Silicon Valley Bank “crisis” - I bought and then sold into the recovery.
One place I redeployed the proceeds was TBC Bank (LON:TBCG) , where the same value signals were flashing just as loudly. It’s got all the hallmarks of a stock that’s being overlooked.
I’ve often looked at TBC Bank as an alternative to Nu Holdings – the Latam bank leveraging digital technology to reach a huge, underserved population. The profitability metrics are comparable, but Nu trades at 20x forward earnings, and offers no dividend. And as much as I like the Nu Holdings narrative and the relative vastness of the Latam market, my developing world preference is in fast-growing Georgia.
The Pitch
TBC Bank Group is Georgia's leading digital bank, with a growing presence in Uzbekistan. The business was founded in 1992 – a year after Georgia gained independence from the Soviet Union – in Tbilisi with just $500 in initial capital. It was incorporated in the UK in 2016 and is now a component of the FTSE 250.
So, what makes this stock worth pitching? Well, it’s got a great track record of growing revenue at pace (CAGR 24.5%) in the post-pandemic period, and forecasts are highly compelling. It’s operating primarily in Georgia, a country which is continuing to experience rapid economic growth – forecasts point to 5.3-7.4% this year.
But even a great business is a bad investment at the wrong price. What continues to interest me is the valuation. It trades at just 5.2x forward earnings with a 7% dividend yield.
The Big Picture
Georgia isn’t on every investor’s radar, and that’s not surprising. However, investors who were willing to do their research and invest in any of the three Georgian companies listed on the London Stock Exchange would have likely been well-rewarded over the past five years.
Georgia is one of the fastest-growing economies in Europe (if you consider it Europe), and it keeps confounding the sceptics. Q1 2026 GDP growth came in at 9.1% -- well ahead of TBC Capital's own 7.4% full-year forecast – and the 2025 figure was 7.5%. Yet the stock trades as though the country is on the brink, weighed down by narratives that recent economic data have increasingly challenged.
- Political overhang: Georgia's foreign agent laws and post-election protests of 2024/25 spooked investors. The political noise has not gone away, but it has not derailed the economy either, with credit growth, exports, and remittances all remaining robust.
- Middle East in turmoil: The US-Iran conflict introduced more uncertainty in early 2026, briefly hitting tourism inflows and the Georgian Lari. The currency recovered quickly and the National Bank's gross international reserves (an important economic indicator) have hit historic highs of $6.7 billion.
- Duopoly dynamics: TBC and Lion Finance dominate the Georgian banking sector, leaving little room for meaningful competition. In a fast-growing economy, that structural position is a licence to compound.
- Uzbekistan is a sideshow: Operations and a regulatory reset in Uzbekistan have been weighing on the stock, perhaps unfairly. The business contributes a fraction of group profits.
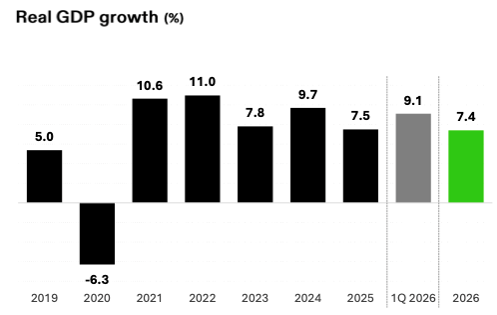
Georgia GDP growth: Source: TBC Capital
Going Deeper
The Q1 numbers were largely very strong. Georgia - GEL362 million in net profit versus Uzbekistan at GEL21 million - delivered net interest income growth of 24% year-on-year, on the back of 12% loan growth and a NIM that is expanding, not contracting (6.2% vs 5.5% in Q1 FY2025).
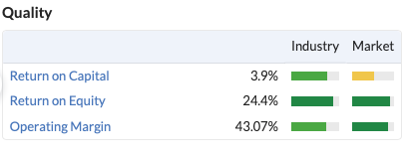
- Profitability that embarrasses Western peers: Group ROE came in at 23.4% in Q1 -- a figure that most UK and European bank CEOs would not dare put in a target letter. The Georgian business alone delivered 24.1%. For context, the average UK bank delivers half that return. You’ve got to look at companies like Nu Holdings for something similar, but that trades at 20x forward earnings with no dividend.
- A digital franchise: Nearly half of TBC's Georgian monthly users interact with the app every single day -- a 49% DAU/MAU ratio that most fintechs would envy. Over 200,000 new digital monthly users were added in the past year. This is a bank that is also a platform.
- Marketplace intent: In August 2025, TBC bought a majority stake in OLX Uzbekistan – a marketplace business. There’s a trend towards banks taking positions in marketplace businesses, and this marks an interesting signal of intent. After all, when people buy cars and homes, financing is very often a part of the equation.
Valuation
The stock has de-rated sharply in recent months – it’s down 15% from its 52-week high – and that doesn’t seem entirely fair.
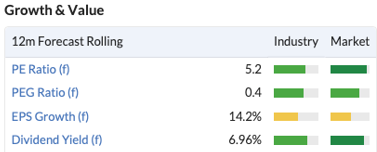
- Forward PE of 5.2x: With 14% EPS growth forecast for 2026, the PEG ratio sits at just 0.4. It’s a cyclical industry, but I’d suggest the drivers here are structural.
- Near-7% dividend yield: Covered 2.8x and growing. The income return is substantial even before any re-rating.
- Price-to-book of 1.37: That might sound expensive, but for a bank generating 23-24% ROE consistently, it’s not demanding. For context, the Nu Holdings P/B ratio is 5.02.
- The Stockopedia StockRank sits at 79, with a Value ranking of 82 and Momentum ranking of 71. I can see the latter shooting up as the value narrative regains traction.
What the Brokers Say
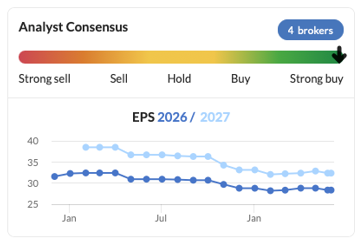
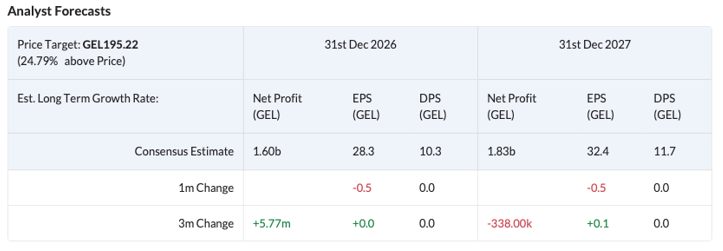
Coverage is thin but positive. Four brokers cover TBC, with the consensus very bullish (four Strong Buys) and a price target of GEL 195.22. This implies nearly 25% upside from the current price.
- Estimates nudging up: Net profit forecasts for 2026 have ticked higher over the past three months, a quiet but meaningful signal.
- Significant upside on offer: The consensus target of GEL 195.22 sits 25% above the current price -- and that's before a near-7% dividend yield is added to the total returns equation.
The Bear Case
The numbers beneath the headlines deserve scrutiny. Operating expenses rose 20% year-on-year, staff costs were up 27%, and the cost-to-income ratio climbed from 37.2% to 40.2%. Non-performing loans (NPL) rose 36% year-on-year. Meanwhile the Uzbekistan reset, framed by management as a deliberate regulatory recalibration, saw net income fall 4%, ROE fall to 10.9% - dragging the group number down - and the loan book contracted nearly 10% quarter-on-quarter (albeit up 6.9% over 12 months).
- Cost creep: A cost-to-income ratio moving in the wrong direction is a yellow flag for any bank. If revenue growth slows while costs keep rising, the profitability story changes quickly. Some of this could reflect the OLX acquisition.
- NPL (non-performing loans) deterioration: Corporate and Investment Banking NPLs in Georgia more than doubling in a year is not something to wave away.
- Geopolitical risk: Georgia's foreign agent laws and strained EU relations remain unresolved. A genuine political deterioration could hit the currency, credit growth, and sentiment simultaneously.
- Uzbekistan timeline: Management say the pipeline is improving, but the numbers aren't there yet.
The Bottom Line
TBC Bank is a high-returning, fast-growing business in one of Europe's most dynamic economies, trading at a valuation that implies something has gone badly wrong. It hasn't. The political noise is real, the Uzbekistan reset is a drag, and the rising costs and NPLs deserve monitoring -- but none of it has dented the core numbers from the Georgian franchise, which continues to compound at 23-24% ROE on double-digit growth. At 5.2x forward earnings and a near-7% yield, the market is offering a wide margin of safety.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

14 comments
Excellent write-up, James.
I particularly liked the focus on valuation rather than simply telling a growth story.
The anxiety in my investment case is that TBC feels like a country thesis disguised as a bank.
The operating metrics are undeniably attractive (24%+ ROE, double-digit growth, strong digital engagement), but the key question isn’t really whether TBC is a good bank – it appears to be. The question is whether Georgia deserves to trade at a persistent discount.
That’s where I find the comparison with Nu Holdings interesting.
Nu operates across Brazil, Mexico and Colombia, giving it a much larger TAM and a degree of geographic diversification.
TBC arguably has the stronger valuation case today, but it is also far more dependent on a single country’s political, regulatory and economic trajectory.
If the market remains uncomfortable with Georgia, the discount may persist regardless of operational performance.
The other comparison I find useful is MercadoLibre(MercadoLibre (NSQ:MELI) ), which isn’t discussed much in UK small-cap circles but has built a remarkable ecosystem across commerce, payments, logistics and credit throughout Latin America.
MELI trades on a much richer valuation, but it has largely escaped the “single-country risk” debate because its growth engine spans a continent and multiple business lines.
So for me the investment question isn’t whether TBC is cheap (it clearly is), nor whether it’s a high-quality franchise (it appears to be), but whether Georgia is relatively undiscovered or structurally deserving of a discount.
That’s probably where the entire bull and bear case converges.
BW
D
Thanks Dr. James. I've been aware of the Georgian bank offerings for a while, but have seen too much geopolitical risk to do further digging. But your analysis is impressive and systematic and we're it not for the aforementioned, I'd be interested, not least for the dividend. Do have a folio we can view to see your other ideas and thereby get a sense of your strategy and share universe? I find always it useful to see individual ideas in context. Thanks again for posting.
Thanks so much, Brucie5. Really appreciate your comments. I can definitely look at making that public.
I think the Nu group is trading at such high premium because of the anticipate mining boom in Latam driven by AI built up and electrification.
Excellent piece James. Bank of Georgia was listed here too - but split into Lion Finance (LON:BGEO) and Georgia Capital (LON:CGEO) . As you say, we've three Georgian banking & finance providers on LSE - all have been excellent performers.
Thank you, Ed. Really appreciate it :)
Good pitch and agree that TBC is good value but I'd contend that it's not Georgias leading digital bank. I think that's held by BGEO.
My pref in this space is BGEO which has just entered the FTSE100 and has much wider diversification. Not as high a dividend but I think its growth in Armenia and dominant position in Georgia will out run TBC and it is less prone to increasing bad debts. Still with high GDP in Georgia, an expanding economy and increasing living standards I wouldn't expect any material change in delinquency any time soon.
Have you been to Georgia? All those trucks on the Military road are carrying what to kill Ukranians? The Stalin house gets daily flowers from the UN? Life is not just about money Dr.
i was in Georgia last month and actually on the military road up to about 50km from the russian boarder. The road is steep, extremely potholed and hazardous. If you are thinking of military shipments from Iran to russia the road route via Azerbaijan or via ship on the Caspian is more likely - and currently the russian and Iranians are building a railway along the side of the Caspian to connect Iran to russia. (the Azerbaijan boarder is closed to all except freight trucks) Having said that the political risk in Georgia is not zero and pootin currently occupies 20% of Georgia.
Thanks for the comment, snowdrop. I have been many times, and I've seen the queue of trucks in Kazbegi. It's country I love to visit -- my daughter's godmother is even Georgian. You've highlighted a very important point, which I totally appreciate, but think it would take a seminar to voice my moral take. Yes, those trucks and that Stalin shrine/museum are uncomfortable truths -- Georgia's relationship with Russia is morally compromised in ways that matter. Broadly, I believe Georgians have been presented with two bad political choices in GD and UNM. Saakashvili showed us why Tbilisi can't play hardball with Moscow. Ivanishvili wouldn't dare.
Do you think Eds banks would get a listing even in Donald J,s USA?
Can you explain how Georgia's relationship with Russia is 'morally compromised ' when there is not even any diplomatic relations between the 2 countries?
I believe the assumption is Putin leverage over Ivanishvili, which partially explains Georgia’s stance.
Has*