The Pebble Group: a SuperStock making ripples in promotional products

My recent screen for cheap growing companies highlighted several familiar names, but its real value lies in identifying under-the-radar opportunities. When I find something I've not looked at before, our new briefer Stock Pitch format is perfect for getting to the heart of the investment case. This week, I'm looking at a Super Stock from the list: The Pebble Group.
Disclosure: At the time of publication, I do not hold a position in The Pebble Group.
The Pitch
Pebble (LON:PEBB) is an AIM-listed provider of technology, products and related services to the global promotional products industry. The group started as a management buyout of three businesses from within 4imprint in 2010. It expanded by the acquisition of a distinct but complementary SaaS business, Facilsgroup, in 2018, giving its current corporate structure:
- Brand Addition is a full-service branded merchandise business that designs, sources and delivers promotional products to corporate clients across many different sectors. It operates globally, generating revenues of £107.5m in FY25. The business has retained approximately 90% of its top clients since 2019 and has a typical ten-year relationship with its top 20 clients.
- Facilisgroup is a subscription-based B2B technology platform serving small and medium-sized promotional product distributors in North America. Its proprietary Syncore platform provides digital commerce tools, consolidated buying power, and a community network, with 96% of its revenue recurring in FY25. The platform processed $1.58 billion in Gross Merchandise Value (GMV) in FY25, representing an estimated 6% share of its addressable North American market. Management believes it can double the current partner base to 500 over time.
The company was listed on AIM in 2019, with the proceeds used to repay debt and satisfy obligations arising from the acquisition of Facilsnet, and to provide an exit for pre-IPO shareholders. Management retained around 9% of the shares, with CEO Christopher Lee now holding just over 4%, and CFO Claire Thompson at 2%.
Despite this slightly strange mix of a design and sourcing business, combined with a technology platform, the algorithms rate this as a high-quality stock with a Quality Rank of 95. Strong Value and Momentum Scores mean that this is a Super Stock with an impressive 98 ranking.
The group's FY25 results, released in March, showed revenue of £124.7m, flat on the prior year, but with an increased gross margin and free cash flow conversion of 91%. EPS came in at 3.9p, 4% ahead of the broker's estimate, showing that the company is executing well in difficult markets.
The Big Picture
Pebble Group has several characteristics that mark it out:
- Different businesses, complementary economics: Brand Addition generated an EBITDA of £11.4m in FY25 on revenue of £107.5m (a 10.6% margin), with a gross margin that has risen from around 29% in 2022 to 37% last year, reflecting a deliberate shift towards higher-value, multi-market client briefs. Facilisgroup is a much higher-margin business, delivering £7.2m of EBITDA on £17.2m of revenue last year. Its 42% adjusted EBITDA margin compares favourably to enterprise software peers, despite a margin dip in FY25 as the company deliberately invested $1m in additional sales capability to accelerate long-term partner growth.
- Capital returns: The group is a relatively capital-light business and is not shy about returning excess capital to shareholders. It paid out £3.0m in dividends in 2025 while also executing a £6.5m tender offer and repurchasing £2.2m of its shares on the market. Overall, this is equivalent to around 16% of the current market cap in a single year. A further £5m buyback was announced alongside the FY25 results, and the dividend was raised by 8.1% to 2.0p per share, representing a 4% yield.
- Net cash: Despite returning nearly £12m to shareholders in FY25, the group retained net cash of £9.6m at year-end, excluding lease liabilities. With a current ratio of 1.80 and an interest cover of nearly 25x, this is a financially strong business.
- Facilisgroup meets the Rule of 40: The "Rule of 40" is a benchmark for assessing the health of SaaS businesses. The idea is that the sum of revenue growth and EBITDA margin should exceed 40%. Panmure Liberum notes that Facilisgroup has consistently met the Rule of 40 over the last three years and expects it to do so increasingly comfortably over the 2026-2028 period as the growth investment pays off.
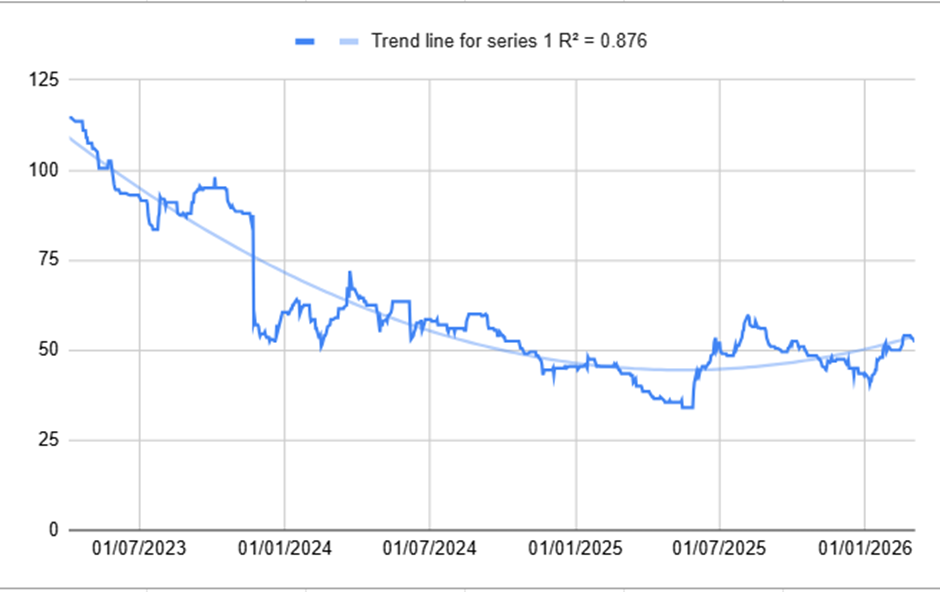
- A possible bowl: Investors will be familiar with the typical Momentum characteristics. Stock Prices tend to mean-revert over periods of three years or longer. Whereas over short time periods, they continue their previous trends. When both of these factors combine, the chart can form a bowl shape. Graphing Pebble's share price trajectory over the last three years reveals a strong fit to a pattern that many investors look for:
Going Deeper
Several factors suggest that the Pebble Group may be approaching an inflexion point:
- Facilisgroup's partner wins are accelerating: It won 30 new partners in FY25, up significantly from the 16 won in FY24, and retention improved from 96% to 97% on an underlying basis. Each new partner has an estimated lifetime value of around £0.5m, making recent sales investments particularly attractive. Management is targeting even more partner wins in FY26, with higher average revenue per partner. In the first weeks of 2026, the company reported improvements in the quality and size of new business it was attracting.
- Facilisgroup's capex cycle is normalising: After several years of heavy investment in its digital commerce platform, Facilisgroup's capex as a percentage of sales fell from an average of 30% in FY22-24 to approximately 20% in FY25. This means a growing share of EBITDA converts into free cash flow, and the Panmure Liberum model's operating cash conversion improves meaningfully through FY27 and FY28.
- Brand Addition's new client momentum: New client wins at Brand Addition jumped from 3 in FY24 to 8 in FY25, with the annualised revenue value of those new wins rising from £3.0m to £7.8m. H2 2025 saw year-on-year revenue growth of 3% at Brand Addition, and management has guided for +5% organic revenue growth in FY26 on stable profit margins, supported by a contract pipeline described as still strong despite the recent wins.
- AI as an opportunity, not a threat: Panmure Liberum specifically highlights AI as a positive for the group rather than a risk. Facilisgroup is using AI to interpret the vast data it holds across its partner and preferred supplier network, adding value to clients. Brand Addition is deploying AI to take costs out of customer servicing workflows. The community and buying group aspects of Facilisgroup's model are hard for AI to disintermediate and provide a structural moat.
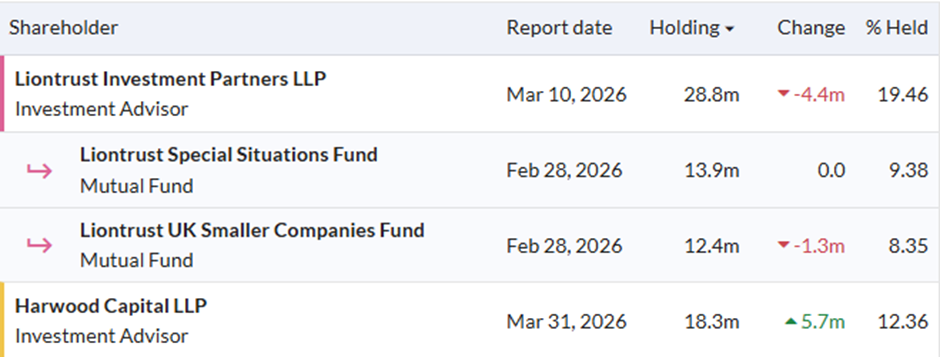
- Harwood stake-building: The largest shareholder, Liontrust, has been reducing their holding (presumably due to fund AUM outflows). However, Harwood has been adding to their stake and this well-regarded fund manager is more likely to be active in taking steps to close any perceived value anomaly:
What The Brokers Say
Panmure Liberum is the research provider and, perhaps unsurprisingly, maintains a BUY rating on its client, with a 95p price target, almost double the current share price. Their recent note, released following the FY25 results, makes four key points to back this up:
- Facilisgroup is already meeting the rule of 40, but revenue growth and margins still have further to go.
- A previously flagged shift from capex to opex will weigh on near-time margins but deliver better growth and cash conversion beyond FY 26;
- Market indicators are mixed and uncertainty is high, but Pebble is partially protected by sector and geographic diversification; and
- Pebble delivered £11.7m of shareholder returns in FY 25, with a further £5m buyback announced for FY 26
They value the group on a sum-of-the-parts basis, applying an EV/EBITDA of 10.3x to Facilisgroup and 7.4x to Brand Addition. Both of these multiples are at a discount to larger peers such as Oracle or 4imprint.
$2m of additional opex being deployed in FY26 to grow Facilisgroup's partner base, and this constrains EPS growth in the near term. However, this investment should generate revenue from FY27, with forecasts for EPS to rise by 36% in FY27 and by a further 19% in FY28. The FY28 forecast free cash flow yield is approaching 20%, demonstrating the business's cash-generating potential.
The Bear Case
The investment case is not without its risks:
- Economic cycle: Promotional products are a discretionary corporate spend, and demand fluctuates with GDP, making this the primary financial risk. North America is Pebble's largest single market exposure, and US business confidence indicators have been mixed. Small business optimism remains elevated, but so does the uncertainty index, and US businesses' advertising spend was trending down most of 2025. A US recession would be a material headwind to both divisions.
- Tariff and geopolitical risk: While product substitution is relatively easy for customers adapting to changed tariff environments, the second-order impacts, such as a decline in business confidence, are hard to hedge. Freight rates have normalised since the spikes a few years ago, but remain an ongoing risk in the current geopolitical environment.
- Customer Concentration at Brand Addition: The top 10 clients at Brand Addition represented approximately 50% of group revenue in FY25. While client retention is high and relationships are long-standing, the loss of even one or two major accounts would have a material impact on group profitability.
- Investment execution risk at Facilisgroup: The forecast FY26 earnings dip is due to a planned $2m increase in opex. If the anticipated acceleration in partner wins does not translate into higher revenue in FY27 and FY28 due to a longer-than-expected ramp-up or customer churn, consensus estimates will face downgrades.
The Bottom Line
The Pebble Group is a slightly strange business, combining both a global provider of promotional products and a SaaS platform business serving the industry in North America. However, both businesses have sticky customers and are highly cash generative. The outlook is mixed, with general economic malaise impacting their products, which are a discretionary spend for many customers. However, the company is doing the right thing in this environment: managing costs carefully, expanding gross margins, accelerating new business wins, and generating cash. It is this ability to generate cash, and both return it to shareholders and invest in future growth, that makes this an attractive proposition.
The key question for 2026 and beyond is whether Facilisgroup's growth investment pays off. The historical ratio of lifetime value to customer acquistion costs suggests they generate a 7x return on each partner acquired. The 88% jump in new partner wins in FY25, along with early positive signals from 2026, suggest the sales machine is working. If it continues, the forecast rise in EPS would make the forward rating compelling.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

1 comment
Good article. I'm surprised by the high quality rating given it barley made a 10% ROCE. Is this actually creating shareholder value? Looking at the historical stock price, you wouldn't think so...