The Week Ahead (18-22 May): takeover frenzy, macro uncertainty

For anyone doubting the value on offer in UK markets, this week’s takeover frenzy might provide pause for thought.
The boards of FTSE 100 testing and certification company Intertek (LON:ITRK) and FTSE 250 healthcare group Spire Healthcare (LON:SPI) both indicated that they would recommend recent takeover offers if they were made firm.
On Thursday, ingredients specialist Tate & Lyle (LON:TATE) received a cash offer from US-based trade rival Ingredion (NYQ:INGR). Although Tate’s board has not yet said whether it would support the deal, I suspect they might do.
Also on Thursday, the Financial Times published a detailed article suggesting Legal & General (LON:LGEN) could become a bid target for US asset management giants.
In each of the first three cases these offers appeared to provide an attractive premium to the undisturbed price prior to the bids becoming public:
Intertek’s board would be prepared to support a £60 offer from Swedish private equity group EQT (59% premium)
Spire Healthcare’s board has indicated they would support a 250p per share offer from long-time shareholder Toscafund, even though Toscafund opposed a 250p offer back in 2021! (67% premium)
Tate & Lyle: the former sugar firm’s board has not yet commented on the 595p per share offer from US rival Ingredion, but the two companies are in discussions (59% premium)
But a broader look at the share price charts for each company suggests an element of opportunistic timing:
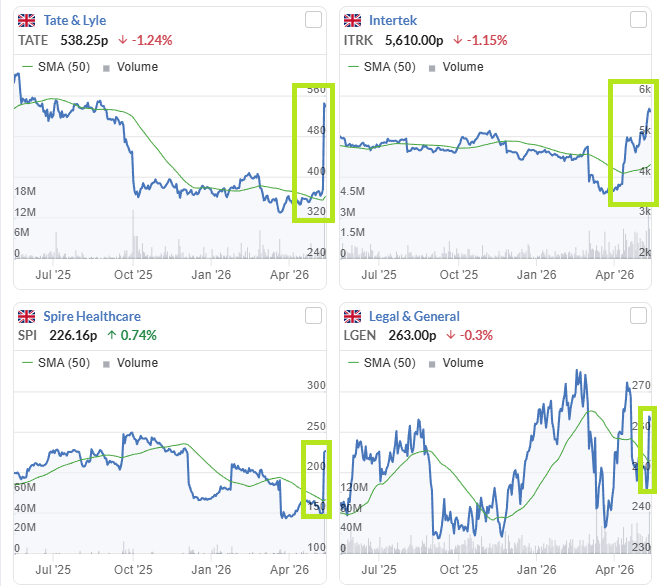
Will we see more takeover offers over the coming weeks? I wouldn’t bet against it. With UK investors seemingly reluctant to back domestic businesses, private buyers will inevitably step in where they see value and opportunity.
Geopolitical uncertainty doesn’t seem to be deterring investors from deploying fresh powder. That’s probably just as well, because the macro situation remains uncertain both at home and in the Middle East.
Here in the UK, Labour rivals to Prime Minister Keir Starmer continue to manoeuvre against him, with the focus currently on Manchester mayor Andy Burnham.
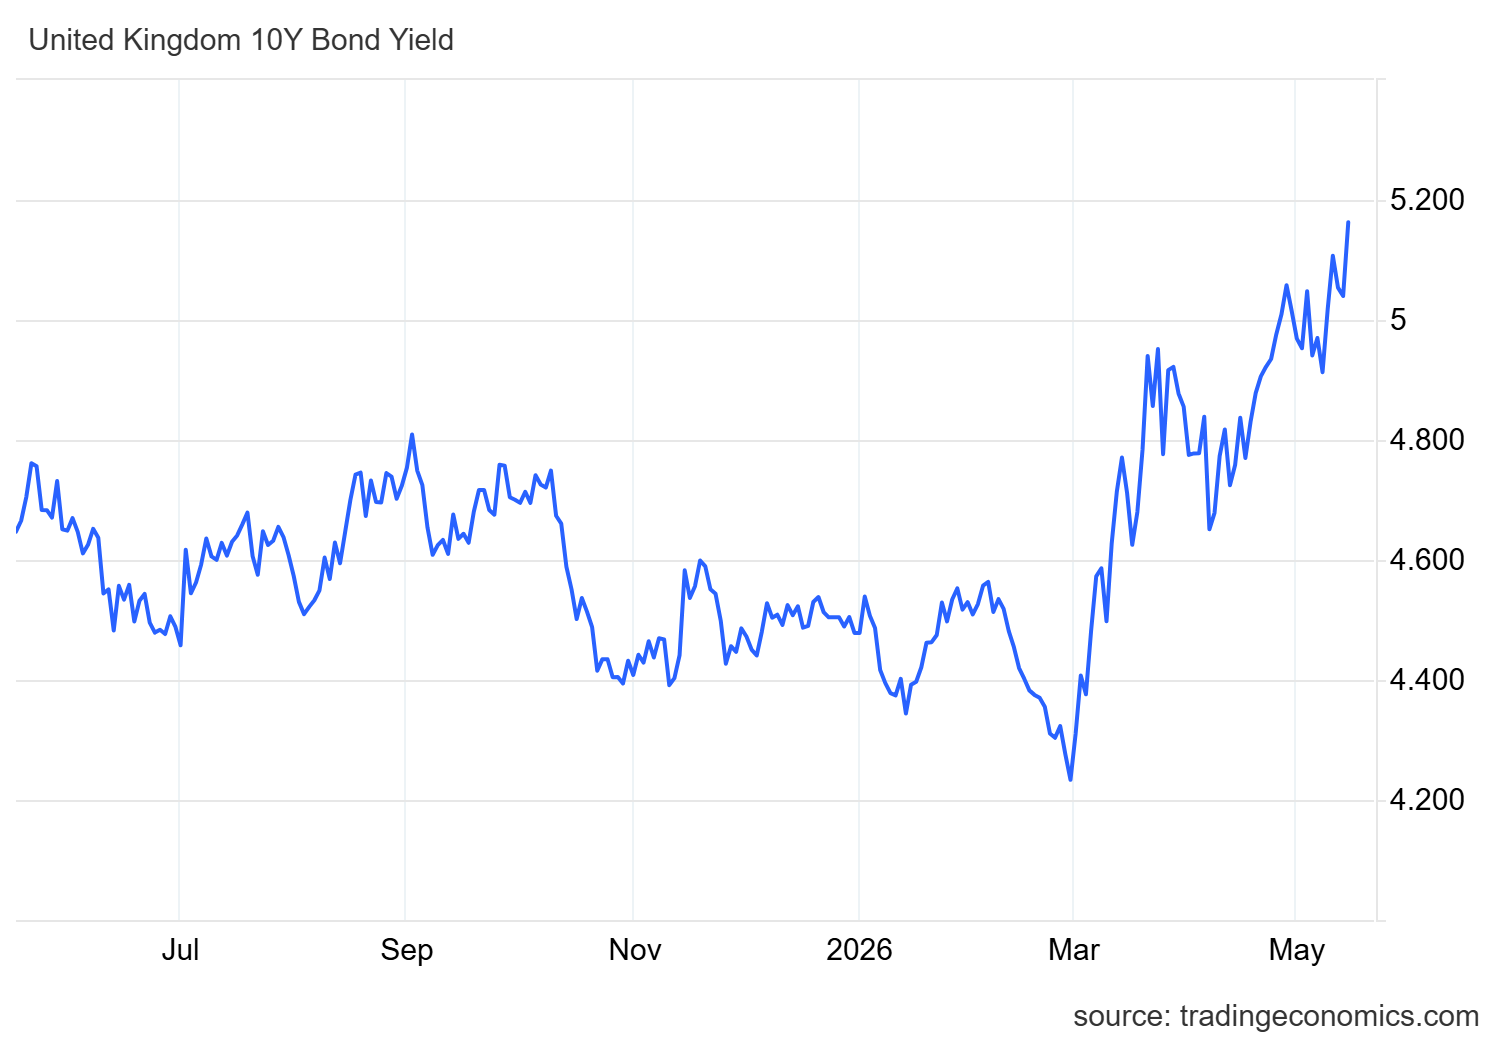
However, bond investors view Starmer and Chancellor Rachel Reeves as more disciplined on spending than Burnham. As a result, they’ve pushed up UK government borrowing costs in recent days, with the 10-year gilt yield now (un)comfortably above 5%:
Elsewhere, news from the Middle East tailed off somewhat during President Trump’s trip to China. While he was there, China’s Xi Jinping is thought to have stressed the importance of achieving a peaceful settlement and reopening the Strait of Hormuz.
The commercial implications of failing to resolve the conflict could be significant for China and the US. The cost to the US public purse of continuing the war could also be high; we learned this week that the war is thought to have cost the US $29bn so far. That’s about $83 for every person in the USA.
Economic News
Data points on the UK calendar next week include unemployment, inflation and house prices. Over the pond, it’s a similar story with housing market data and unemployment both set to hit the wires.
Other points of interest may include the latest oil and gas storage levels in the US, together with the latest rig count from US fossil fuel producers who have so far remained stubbornly (wisely?) unwilling to splash the cash on ramping up production.
This strategy has been very profitable for producers, but global stockpiles are coming under pressure. It will be interesting to see if US inventories are starting to show any sign of weakness ahead of the summer driving season.
Company news
Next week may see some results of interest from UK big caps. Several high-profile victims of the AI/SaaS sell-off – Experian, Sage and Autotrade – are due to report results. Elsewhere, Irish energy and distribution group DCC is also due to report.
Moving down in size, results from publisher Bloomsbury Publishing are likely to be a popular choice for coverage in the Daily Report, following the company’s upgrade to guidance earlier this year. Concerns remain (for me, at least) that this business is overly dependent on two or three authors, but there’s no doubt it has achieved much in recent years and has some attractive qualities.
Scheduled news from US companies is limited next week, but AI chip giant Nvidia is due to report Q1 earnings on Wednesday.
Enjoy the weekend!
Here’s a summary of what’s expected next week.
Economic Calendar
Date / Time (BST) | Country | Event |
18 May | ||
00:01 | UK | Rightmove House Price index |
03:00 | China | Industrial Production |
19 May | ||
07:00 | UK | Unemployment data |
10:00 | EU | Balance of Trade |
13:15 | US | ADP Weekly Employment Change |
15:00 | US | Pending Home Sales |
21:30 | US | API Weekly Crude Oil Stocks |
20 May | ||
07:00 | UK | Inflation |
10:00 | EU | Inflation |
12:00 | US | MBA 30-Year Mortgage Rate |
15:30 | US | EIA Crude Oil Stocks Change |
15:30 | US | EIA Gasoline Stocks Change |
19:00 | US | FOMC Minutes |
21 May | ||
08:30 | Germany | S&P Global Manufacturing PMI Flash |
09:30 | UK | S&P Global Manufacturing PMI Flash |
13:30 | US | Housing Starts |
13:30 | US | Building Permits |
13:30 | US | Initial Jobless Claims |
14:45 | US | Manufacturing & Services PMI |
15:30 | US | Natural Gas Storage |
22 May | ||
00:01 | UK | GfK Consumer Confidence |
07:00 | UK | Retail Sales |
18:00 | US | Baker Hughes Oil Rig Count |
Companies Reporting
Date | UK Trading Updates and AGMS | UK Financial Results | International Financial Results |
Monday 18 May | Big Yellow (LON:BYG) Central Asia Metals (LON:CAML) Harworth (LON:HWG) Riverstone Energy (LON:RSE) Social Housing REIT (LON:SOHO) Synectics (LON:SNX) | Kainos (LON:KNOS) | Baidu (NSQ:BIDU) |
| Tuesday 19 May | Arbuthnot Banking (LON:ARBB) Artisanal Spirits (LON:ART) Cirata (LON:CRTA) Computacenter (LON:CCC) Currys (LON:CURY) EKF Diagnostics Holdings (LON:EKF) Fintel (LON:FNTL) Fresnillo (LON:FRES) Greencoat UK Wind (LON:UKW) Hilton Food (LON:HFG) IG group (LON:IGG) Integrated Diagnostics Holdings (LON:IDHC) International Workplace (LON:IWG) Luceco (LON:LUCE) Regional REIT (LON:RGL) Shell (LON:SHEL) TBC Bank (LON:TBCG) Trustpilot (LON:TRST) Videndum (LON:VID) | Avacta (LON:AVCT) C&C (LON:CCR) Caledonia Investments (LON:CLDN) Cranswick (LON:CWK) DCC (LON:DCC) Diploma (LON:DPLM) IXICO (LON:IXI) Jadestone Energy (LON:JSE) SSP (LON:SSPG) Topps Tiles (LON:TPT) | Home Depot (NYQ:HD) Keystone Law (LON:KEYS) Toll Brothers (NYQ:TOL) |
| Wednesday 20 May | Capital (LON:CAPD) Coats (LON:COA) Energean (LON:ENOG) 4imprint (LON:FOUR) Intertek (LON:ITRK) Judges Scientific (LON:JDG) Keller (LON:KLR) Mortgage Advice Bureau (Holdings) (LON:MAB1) Petards (LON:PEG) Playtech (LON:PTEC) Real Estate Investors (LON:RLE) Science (LON:SAG) Stelrad (LON:SRAD) | Bloomsbury Publishing (LON:BMY) British Land (LON:BLND) Chesterfield Special Cylinders Holdings (LON:CSC) Experian (LON:EXPN) Impax Asset Management (LON:IPX) Integrafin Holdings (LON:IHP) Marks and Spencer (LON:MKS) RS (LON:RS1) Severn Trent (LON:SVT) | Analog Devices (NSQ:ADI) Hasbro (NSQ:HAS) Intuit (NSQ:INTU) Lowes Companies (NYQ:LOW) NVIDIA (NSQ:NVDA) Target (NYQ:TGT) TJX Companies (NYQ:TJX) |
| Thursday 21 May | Henry Boot (LON:BOOT) Cambridge Cognition Holdings (LON:COG) Capricorn Energy (LON:CNE) Comptoir (LON:COM) ConvaTec (LON:CTEC) Distribution Finance Capital Holdings (LON:DFCH) Endeavour Mining (LON:EDV) Everplay (LON:EVPL) FDM (Holdings) (LON:FDM) Hill and Smith (LON:HILS) Ibstock (LON:IBST) JTC (LON:JTC) Legal & General (LON:LGEN) Michelmersh Brick Holdings (LON:MBH) Next (LON:NXT) Niox (LON:NIOX) Pharos Energy (LON:PHAR) Savannah Resources (LON:SAV) Shawbrook (LON:SHAW) Serica Energy (LON:SQZ) Travis Perkins (LON:TPK) Yu (LON:YU.). | AJ Bell (LON:AJB) Autotrader (LON:AUTO) Braemar (LON:BMS) BT (LON:BT.A).A easyJet (LON:EZJ) Great Portland Estates (LON:GPE) Investec (LON:INVP) Londonmetric Property (LON:LMP) Sage (LON:SGE) Tate & Lyle (LON:TATE) Young & Cos Brewery (LON:YNGA) | Deere & Co (NYQ:DE) Deckers Outdoor (NYQ:DECK) ITC (NSI:ITC) Ralph Lauren (NYQ:RL) Walmart (NSQ:WMT) |
| Friday 22 May | A G Barr (LON:BAG) Checkit (LON:CKT) Enquest (LON:ENQ) Genuit (LON:GEN) Lion Finance (LON:BGEO) Nexteq (LON:NXQ) | Helio SA (WAR:HEL) | Meituan (HKG:3690) Booz Allen Hamilton Holding (NYQ:BAH) |
Disclosure: Roland owned shares in Sage and DCC at the time of publication.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

10 comments
On Friday afternoon Alternative Income REIT (LON:AIRE) received another takeover bid, this time from their main shareholder, after the previous bid by Aew UK Reit (LON:AEWU) fell through. (I hold AIRE).
Nice summary Roland. Thank you.
The USD/GBP ratio looks set to continue increasing which will make UK companies look an even better deal if you are based in the US.
Magnum Ice Cream NV (LON:MICC) also today a possible bid target. The strength of the US market is killing the UK market.
Tbf they’re really an Amsterdam listed business
But I agree in principle…all our good co’s getting picked off! No doubt Andy’ s first action as PM will be to ban takeovers of UK stocks! Meaning we have no hope of making any money!
Where is the bid of the week, Cordel (LON:CRDL) at 104% premium?
Dates to add;
Tue, 19
Victorian Plumbing (LON:VIC) - AGM
Thur, 21
Ashtead Technology Holdings (LON:AT.) - AGM
Ondine Biomedical (LON:OBI) - FY
Yu (LON:YU.) - AGM
And nows theres Hiscox (LON:HSX) to add to the watch list - who's next?
"But a broader look at the share price charts for each company suggests an element of opportunistic timing"
You're nae wrang, as they say in Scotland. Add Gamma Communications (LON:GAMA) to the list, which is involved in a takeover situation. It's not a done deal by any means, but look at it this way, it's got a fwd PE of 9.7. 9.7! Revenues have been growing by 10% pa over the last 5 years. It has 22% ROCE. I always treat talk of takeovers sceptically, but I think this one will go through. I hope it doesn't (I own shares), but I don't see why an acquirer would back down.
Good point Mark, I forgot about Gamma Communications (LON:GAMA) - although I did cover it in Wednesday's DSMR!
Cheers,
Roland
Thanks Sabre Insurance (LON:SBRE) agm/ts on Thursday lovely yield