The Week Ahead (27 Apr – 1 May): Interest Rates, UK House Prices, Mag 5, Sanderson Design

A strong week for the S&P 500 and weakness elsewhere mean this still leads the pack over the last month:
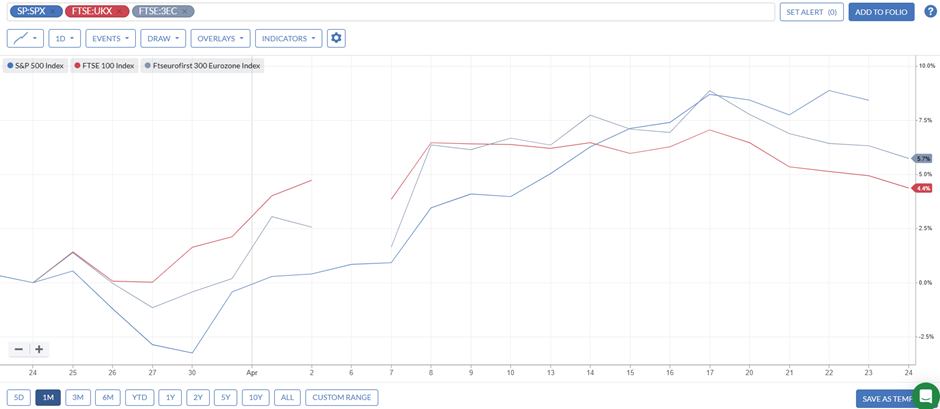
US markets appear to have largely shrugged off the ongoing impacts of the Iran war, which may add to the risks of a correction if tensions in the Middle East start to rise again.
Here's what we can look forward to next week:
Economic Calendar
Monday 27 Apr |
||
07:00 |
Germany |
GFK Consumer Confidence |
Tuesday 28 Apr |
||
04:00 |
Japan |
BoJ Interest Rate |
15:00 |
United States |
Consumer Confidence |
21:30 |
United States |
API Crude Stocks |
Wednesday 29 Apr |
||
10:00 |
Euro Area |
Economic Sentiment |
12:00 |
United States |
MBA Mortgage Rate |
13:00 |
Germany |
Inflation |
13:00 |
United States |
Building Permits Housing Starts |
15:30 |
United States |
Crude Oil Inventories |
19:00 |
United States |
Fed Interest Rate |
Thursday 30 Apr |
||
02:30 |
China |
Manufacturing PMI |
06:00 |
Japan |
Consumer Confidence |
07:00 |
UK |
Nationwide House Price Index |
09:00 |
Germany |
GDP |
10:00 |
Euro Area |
GDP Inflation Unemployment |
12:00 |
UK |
BoE Interest Rate |
13:15 |
Euro Area |
ECB Interest Rate |
13:30 |
United States |
Continuing Claims Initial Jobless Claims Personal Consumption Personal Income |
13:45 |
Euro Area |
ECB Press Conference |
Friday 1 May |
||
09:30 |
UK |
Consumer Credit Mortgage Approvals |
Interest Rates
It is a big week for interest rates with the BoJ, Fed, ECB and Bank of England all publishing their decisions within a few days. The BoJ kick us off on Tuesday, with the Fed announcing on Wednesday evening, the BoE at midday on Thursday and the ECB shortly afterwards.
The consensus is for all four central banks to hold rates steady. However, the inflationary spike caused by the Iran war is complicating matters, and this may be the first real chance we get to see how these events are shaping monetary policies. All central banks, apart from the BoJ, were in a rate-easing cycle prior to recent global events. However, the consensus has shifted from further easing to rates remaining higher for longer, and even edging back towards hikes in Europe and the UK:
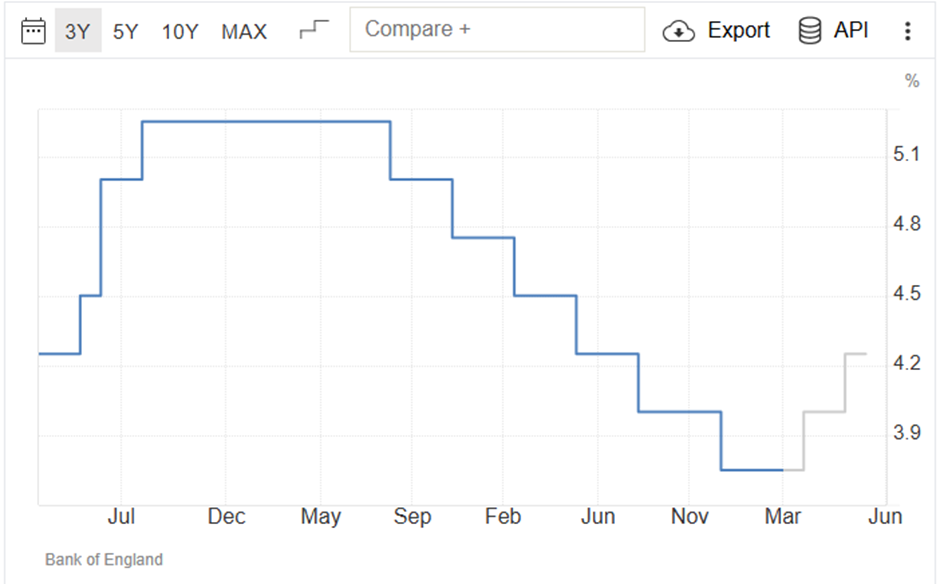
[All charts in this section: Trading Economics]
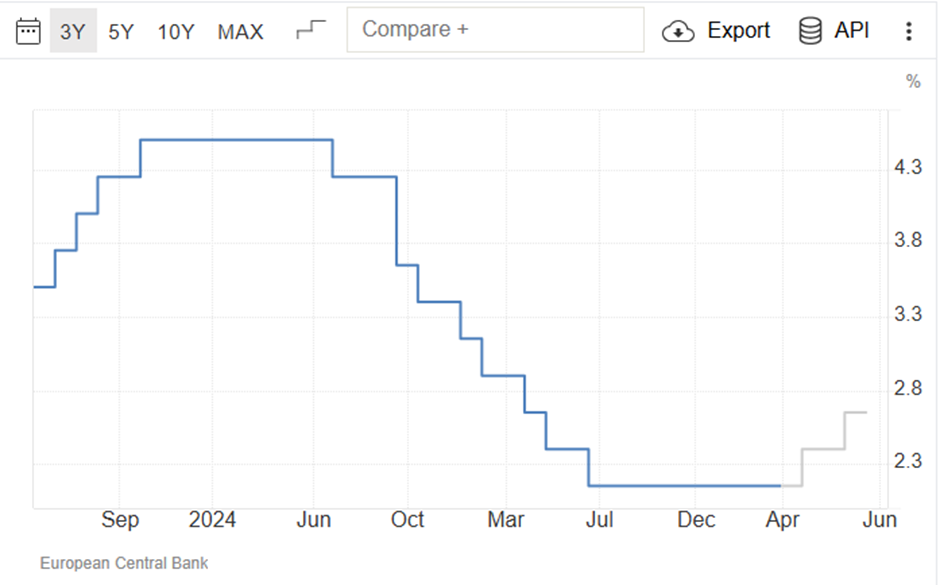
The forward guidance from all four will matter more than the decision. As will any splits in how the BoE members are voting.
UK House Prices
Apart from the BoE interest rate decision, the main UK economic news will be the Nationwide House Price data released on Thursday. While house prices certainly haven't been going great guns recently, with sub-inflation rises, they have beaten expectations over the last few months. The rate of increase is expected to be larger over the next year, too:
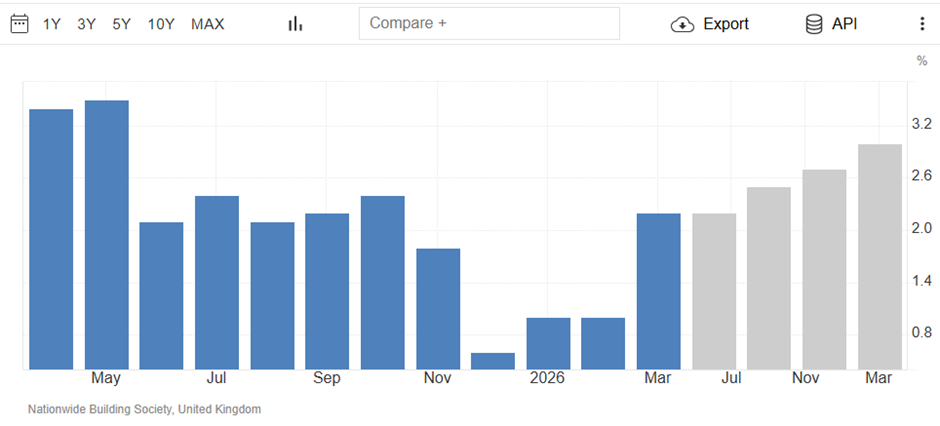
However, there is undoubtedly a mismatch between these house price figures and what the stock market is pricing for the major housebuilders and related businesses. It is this dislocation that makes data points like this have an outsized impact on investor sentiment.
Companies Reporting
| Date | UK Trading Updates & AGMS | UK Financial Results | International Financial Results |
|---|---|---|---|
Monday 27 Apr |
Bango (LON:BGO) (Finals) Christie (LON:CTG) (Finals) Nostrum Oil & Gas (LON:NOG) (Finals) Power Probe (LON:PWR) (Finals) |
Cadence Design Systems (NSQ:CDNS) |
|
Tuesday 28 Apr |
Aiq (LON:AIQ) (AGM) Coca-Cola Europacific Partners (LON:CCEP) (TS) CT Healthcare Trust (LON:CTHT) (AGM) CVC Income & Growth (LON:CVCE) (AGM) GlobalData (LON:DATA) (AGM) Guaranty Trust Holding (LON:GTCO) (AGM) Howden Joinery (LON:HWDN) (TS) Maven Income and Growth VCT 5 (LON:MIG5) (AGM) Natwest (LON:NWG) (AGM) Ocado (LON:OCDO) (AGM) Oriole Resources (LON:ORR) (AGM) Tradeweb Markets (NSQ:TW). (TS) Tradeweb Markets (NSQ:TW). (AGM) WPP (LON:WPP) (TS) Zoyo (LON:ZOYO) (AGM) |
Anglo American (LON:AAL) (Q1) Barclays (LON:BARC) (Q1) BP (LON:BP.). (Q1) Card Factory (LON:CARD) (Finals) Eleco (LON:ELCO) (Finals) Georgia Capital (LON:CGEO) (Q1) Likewise (LON:LIKE) (Finals) Tracsis (LON:TRCS) (Interims) Tullow Oil (LON:TLW) (Finals) |
C3.ai (NYQ:AI) (France) |
Wednesday 29 Apr |
Aberdeen (LON:ABDN) (AGM) Admiral (LON:ADM) (AGM) Alliance Witan (LON:ALW) (AGM) Anglo American (LON:AAL) (AGM) Elementis (LON:ELM) (AGM) Breedon (LON:BREE) (AGM) Endeavour Mining (LON:EDV) (AGM) Entain (LON:ENT) (AGM) Glanbia (LON:GLB) (AGM) HALEON (LON:HLN) (AGM) Halfords (LON:HFD) (TS) Ingersoll Rand (NYQ:IR)ON (AGM) Lancashire Holdings (LON:LRE) (AGM) Lloyds Banking (LON:LLOY) (TS) ME International (LON:MEGP) (AGM) Mincon (LON:MCON) (AGM) Oakley Capital Investments (LON:OCI) (TS) PPHE Hotel (LON:PPH) (TS) Primary Health Properties (LON:PHP) (AGM) SThree (LON:STEM) (AGM) Symphony International Holdings (LON:SIHL) (AGM) Pebble (LON:PEBB) (AGM) J D Wetherspoon (LON:JDW) (TS) |
Aston Martin Lagonda Global Holdings (LON:AML) (Q1) AstraZeneca (LON:AZN) (Q1) Banco Santander SA (LON:BNC) (Q1) Chapel Down (LON:CDGP) (Finals) Evoke (LON:EVOK) (Finals) Futura Medical (LON:FUM) (Finals) GSK (LON:GSK) (Q1) HALEON (LON:HLN) (Q1) Keystone Law (LON:KEYS) (Finals) Northcoders (LON:CODE) (Finals) Prudential (LON:PRU) (Q1) Puretech Health (LON:PRTC) (Finals) Sanderson Design (LON:SDG) (Finals) St Jamess Place (LON:STJ) (Q1) Warpaint London (LON:W7L) (Finals) |
Abbvie (NYQ:ABBV) Ford Motor Co (NYQ:F) |
Thursday 30 Apr |
C3.ai (NYQ:AI)BG (AGM) Alfa Financial Software Holdings (LON:ALFA) (AGM) ASA International (LON:ASAI) (TS) Cairn Homes (LON:CRN) (AGM) Develop North (LON:DVNO) (AGM) Drax (LON:DRX) (AGM) Edinburgh Worldwide Investment Trust (LON:EWI) (AGM) Ford Motor Co (NYQ:F)RAN (AGM) Glencore (LON:GLEN) (TS) Hammerson (LON:HMSO) (AGM) Helix Exploration (LON:HEX) (AGM) Inchcape (LON:INCH) (TS) International Personal Finance (LON:IPF) (TS) International Personal Finance (LON:IPF) (AGM) Kerry (LON:KYGA) (AGM) Lancashire Holdings (LON:LRE) (TS) M&G (LON:MNG) (AGM) Maven Income and Growth VCT 3 (LON:MIG3) (AGM) MONY (LON:MONY) (AGM) Net Zero Infrastructure (LON:NZI) (AGM) Osb (LON:OSB) (TS) Persimmon (LON:PSN) (TS) Persimmon (LON:PSN) (AGM) Richmond Hill Resources (LON:RHR) (AGM) RIT Capital Partners (LON:RCP) (AGM) Robert Walters (LON:RWA) (AGM) Richtech Robotics (NAQ:RR). (AGM) SIG (LON:SHI) (AGM) Sigmaroc (LON:SRC) (AGM) Unilever (LON:ULVR) (TS) |
Beazley (LON:BEZ) (Q1) Endeavour Mining (LON:EDV) (Q1) International Paper Co (LON:IPC) (Q1) Novacyt SA (LON:NCYT) (Finals) Smurfit WestRock (LON:SWR) (Q1) Standard Chartered (LON:STAN) (Q1) Titon Holdings (LON:TON) (Interims) Weir (LON:WEIR) (Q1) Whitbread (LON:WTB) (Finals) |
Apple (NSQ:AAPL) MasterCard (NYQ:MA) Marks Electrical (LON:MRK) |
Friday 1 May |
MJ GLEESON (LON:GLE) (TS) |
Aon (NYQ:AON) |
We are well into AGM season, with a phenomenal number of UK companies holding their AGMs this week.
As usual, let us know via the comments if you think we've missed anything of note.
Mag 5
Five of the biggest companies in the US are reporting next week: Alphabet, Amazon, and Meta report Q1 results after the market close on Wednesday, and Microsoft releases Q3 results at the same time. Apple reports its Q2 results after the market close on Thursday.
With varying AI strategies but phenomenal capex spending across the sector, returns on AI investment will be a key focus for all of them.
Alphabet (NSQ:GOOG)
Google has been consistently beating quarterly expectations by some margin recently:
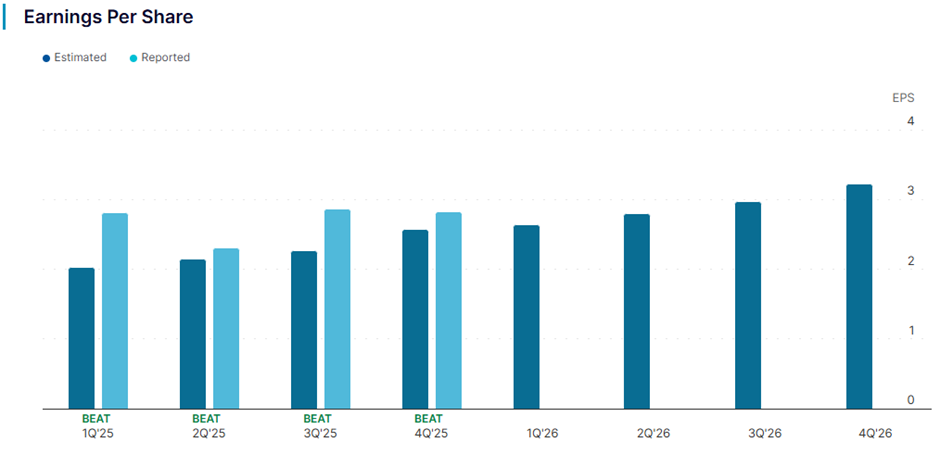
[Charts in this section: NASDAQ]
Here are some things to look out for:
- Google Cloud: growth is projected to exceed 50%; this will be a key metric for this quarter.
- Search: Investors will watch for any signs of AI alternatives eroding core Search revenue, which is estimated at roughly $59B.
- Capex: The company has guided for a massive $175B–$185B in 2026 capex, which could compress near-term margins. Investors will be looking for signs that they are generating returns on this investment.
Amazon.com (NSQ:AMZN)
Q4 earnings were weak and missed expectations. Investors will be hoping for this to be a one-off:
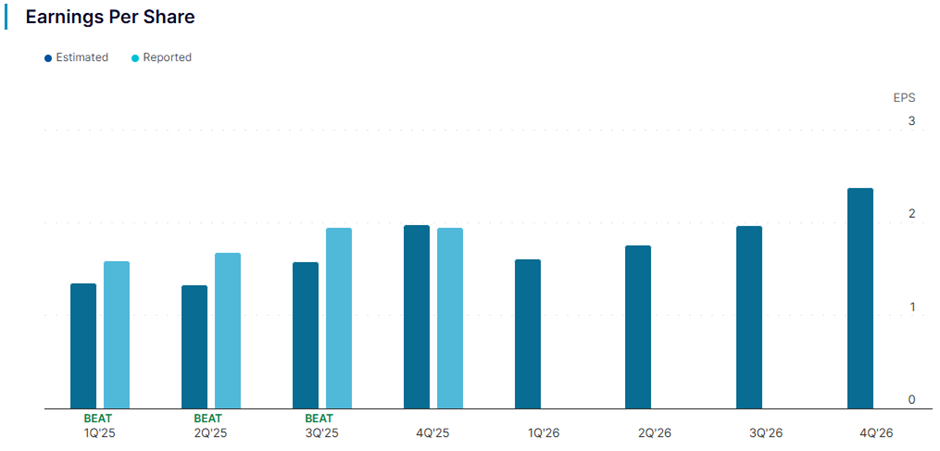
Here are some things to look out for:
- AWS Rebound: AWS revenue is estimated to grow by 25% YoY, buoyed by the Anthropic partnership and custom AI chips.
- Retail Margins: Can logistics efficiencies offset rising energy costs and potential tariff impacts?
- Advertising: Now a core profit engine, can this deliver meaningful growth and profits?
Apple (NSQ:AAPL)
Apple has recently beaten quarterly estimates, but not by much. Q1 is a seasonally weak quarter, so absolute earnings may matter less than the general trend:
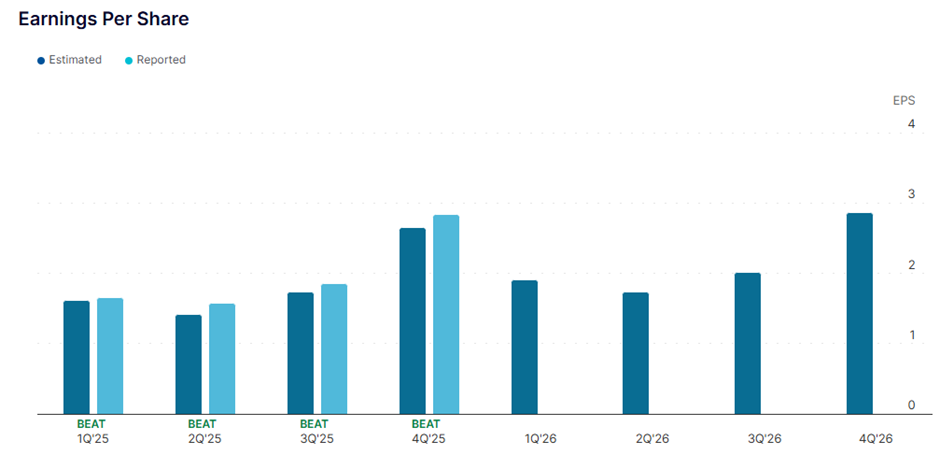
Here are some things to look out for:
- Services: These are high-margin and projected to grow 14%. Any variance in growth rate could have a material impact, either way.
- China/India: Can resilient iPhone demand in India offset competition and regulatory headwinds in China?
- Transition: There is talk of leadership succession and a pivot back to a hardware-first AI strategy. Look out for any big announcements on this front.
Meta Platforms (NSQ:META)
Again, a consistent beater of expectations recently:
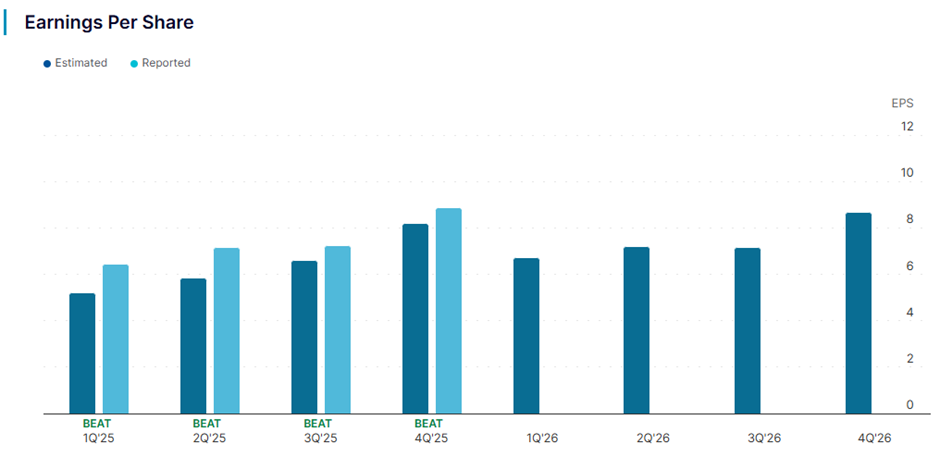
Here are some things to look out for:
- Ad Dominance: Can AI-powered tools like Advantage+ deliver high ad growth?
- Superintelligence: Zuckerberg's pivot to "personal superintelligence" involves heavy capex ($115B–$135B). In light of this, investors will focus on margin resilience.
- Engagement: Watch for monetisation progress for Threads and Reels compared to TikTok and X.
Microsoft (NSQ:MSFT)
Another consistent beater of quarterly expectations:
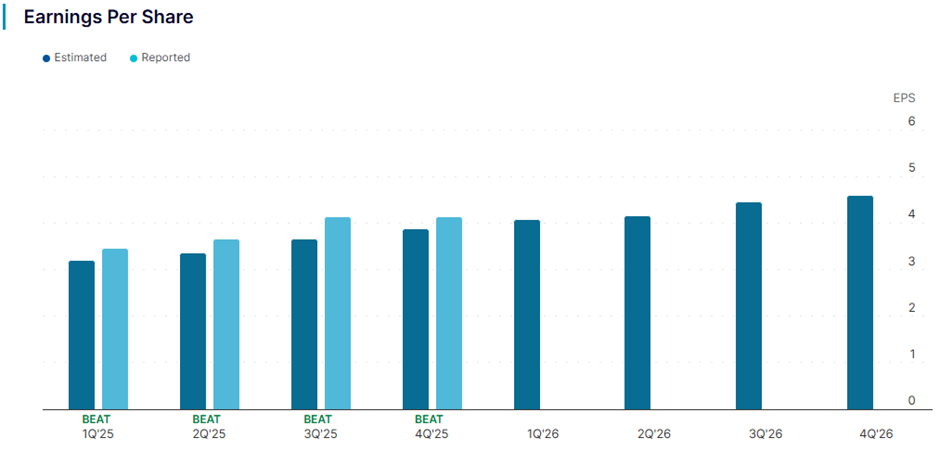
However, this hasn't stopped the market worrying about their strategy:
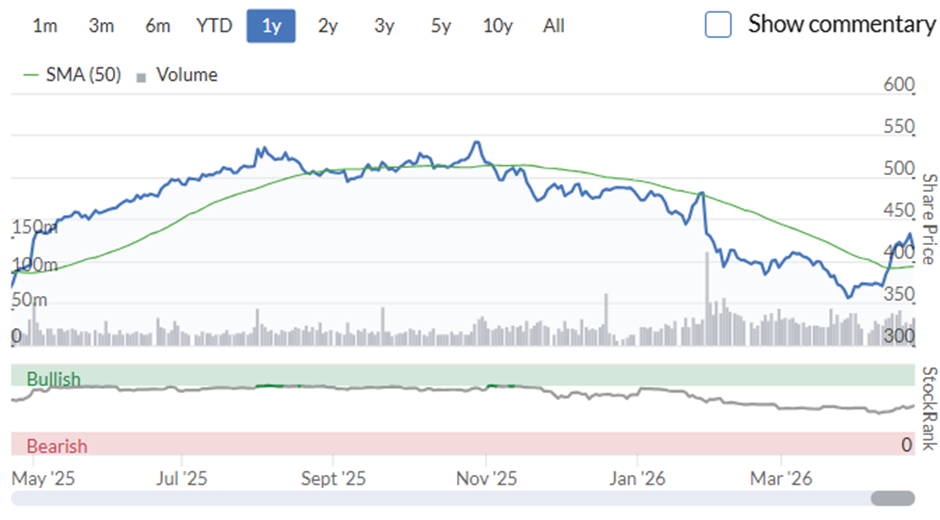
Here are some things to look out for:
- Azure Growth: The market will watch the Azure numbers very closely. This is expected to grow 37–38%, and growth here will be one of the key metrics.
- AI Returns: Investors will look for proof that Copilot adoption is converting into material revenue, especially after heavy 2026 capex guidance.
Sanderson Design (LON:SDG)
Personally, I will be following Sanderson Design's results very closely. One of the attractions to value investors, such as myself, is the discount to Book Value, here:
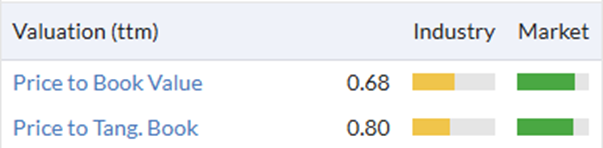
This is a case where the intangible assets definitely have value, as their design catalogue generates ongoing high-margin licensing revenue. However, the broker consensus recently has not exactly been encouraging:
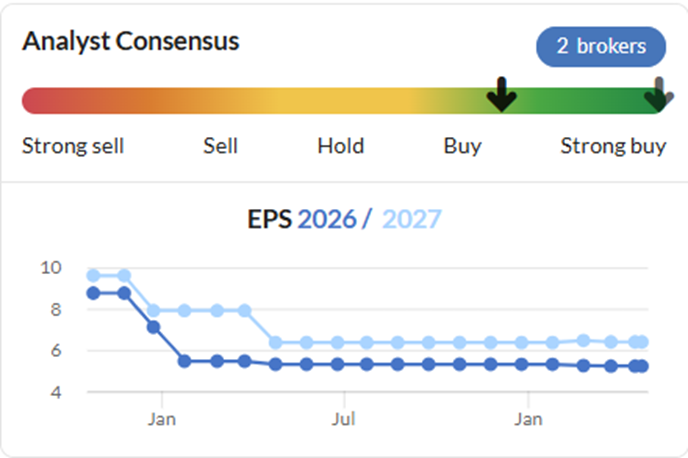
My theory (and I reiterate that this is a personal theory and has not been confirmed by the company) is that they were caught a bit off guard by the downturn in their end markets. Their customers are exactly the sort of people who have school fees to pay, so when VAT was added to these costs, they had less spending power. With net cash and the valuable ongoing licensing stream generating strong cash flow, they were slow to react to these events, preferring a wait-and-see approach. It was only when it became clear that this demand was not going to bounce back immediately that they took the necessary action to cut costs, and we are now seeing the benefits of that action. Their trading update released in February was well-received by the market:
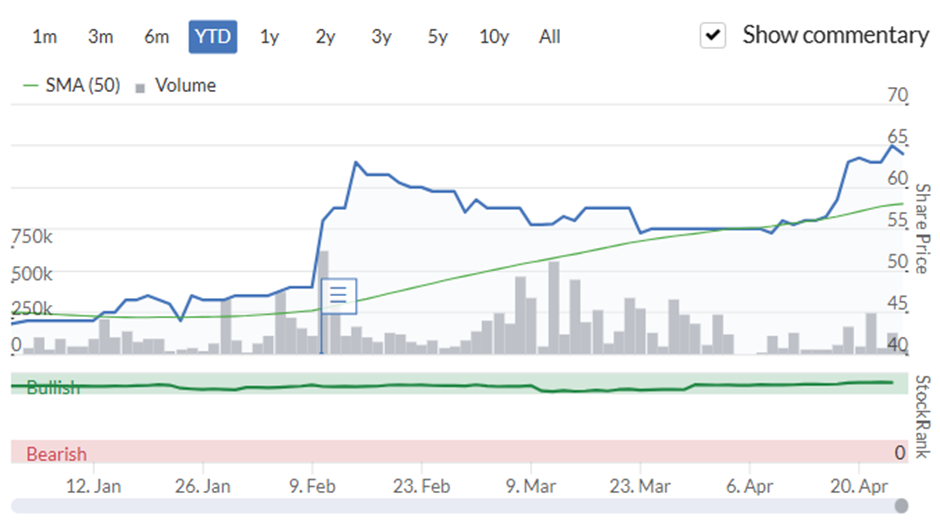
The commentary on US sales said they were experiencing "increasing momentum", which gives some hope of recovery. They are no longer as cheap as they were prior to this update:
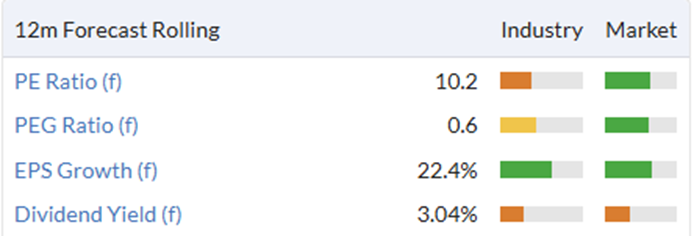
However, rising sales against a backdrop of improved margins could deliver a sharp profit recovery and lead to a further re-rating. They are also presenting at the Mello investing conference in June for the first time in several years, suggesting they feel they have a story to tell again.
However, there is no denying that they are operating in difficult markets in the UK, and the recent rise in share price runs counter to the trend among other companies exposed to UK consumer sentiment. It is this dynamic that will make these results and any accompanying commentary worth reading in detail.
[Disclosure: Mark owns shares in Sanderson Design (LON:SDG)]
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

10 comments
Using Co-pilot in Chat mode to do some spreadsheet analysis/commentary for in house accounts, it keeps hallucinating some of the figures, and can't be trusted without going through everything oneself, somewhat undoing the basis I was using it for.
As an untrained AI virgin I was a bit surprised. This may not be the best way of using the tool, but it somewhat deflated my expectations.
News from several portfolio companies expected this week
ZIGUP (LON:ZIG) Halfords (LON:HFD) Pebble Beach Systems (LON:PEB) ME International (LON:MEGP) and Oakley Capital Investments (LON:OCI)
I expect touchwood reasonable updates from all, although the current share prices do not necessarily reflect my expectations.
Oakley Capital Investments (LON:OCI) share price has been dented I suspect by the AI bruha given that it invests to a large extent in European digitally enabled companies.
Halfords (LON:HFD) is the largest bike retailer in the UK and hopefully the strong showing form Tandem (LON:TND) in terms of bike sales will read across. On top of which the Tour de France Grand Depart (men and women) is coming to the UK next year, which should boost sales. It will be interesting to see how the Fusion Garages roll out is progressing. For Joe public Halfords (LON:HFD) I would suggest is the go to retailer for generic motoring bits and pieces. Hopefully the new CEO Henry Birch has started to turn the ship around despite the headwinds faced by UK retailers!
Pebble Beach Systems (LON:PEB) Positive trading update in January. Expects to be in a net cash position by the end of FY26.
I note that Laurence Hulse, manager of Onward Opportunities (LON:ONWD) as good as doubled his holding to 10% around the current price, following the recent contract win announced on 16 February.
"Pebble, the global software company providing specialist automation solutions for the broadcast and streaming markets, is pleased to announce a new contract win, worth an initial £1.3 million over its five-year term, in support of a Tier 1, US-based streaming company. The new agreement has scope for significant further revenues as the relationship grows and extends."
ZIGUP (LON:ZIG) Perennially cheap and underappreciated in my view,
I bought at the interims last December around 385p, the share price has started to tick up of late. Hopefully the recent fuel price rise as a result of Donad's daft antics hasn't derailed the positive outlook from the interims.
"The positive outlook for the remainder of the year gives us confidence that underlying PBT will be at least at the top of the range of analysts' expectations. This view is underpinned by the strength of Spanish rental performance and continued investment in fleet growth. UK&I rental demand remains robust, and we expect rental margin to be within the 15-16% target range for the full year. Claims & Services volumes are expected to grow as new contracts and service extensions start to contribute during the busier second half, with EBIT margin moving closer to the 5% medium-term target."
ME International (LON:MEGP) Bought after re-listing and fortunate to add at 130p. Just looked too cheap for a quality business.
The above are just my view and the post is mainly for my own benefit to remind me why I invested in the companies mentioned
I note the narratives from ShoeShineBoy and timarr and without wishing to make them blush, they are in my view two of the more considered contributors on Stockopedia. I share their views regarding the under valuation of UK equities, especially small and mid-caps, but as always patience is required, which at times is difficult.
All the best
ZIGUP (LON:ZIG) 30/4/26
Sylvania Platinum (LON:SLP) 28/4/26
Woodward (NSQ:WWD) 29/4/26
On a quiet Sunday, the following was an interesting read from the free weekly email from Stephen Clapham's substack:
The Market Everyone Has Given Up On
Behind the Balance Sheet | Stephen Clapham | Substack
The UK is one of the cheapest and least loved markets in the world and may finally be approaching a turning point.
I attended a conference this week where, notably, two New York hedge fund managers flew in to pitch UK ideas, alongside respected global value investor Richard Oldfield and a group of UK managers. That alone suggests sentiment may be shifting at the margin.
UK equities haven’t just underperformed, they’ve been abandoned. Ten consecutive years of outflows tells you this is no longer about performance, but positioning....
SSB: the Brexit vote in 2016 is often put forward as the main reason why foreign investors have sold the UK market. But why was 2024 such a big year of outflows ? Does the above take into account takeovers ? I don't think so. Views welcome.
On a quiet Sunday, the following was an interesting read from the free weekly email from Stephen Clapham's substack:
London Value Investor Conference I think.
Without direct access you can't get info on the stocks analysed but from what I can gather the following were on the agenda:
The general view is that the UK market is just too cheap and pension funds can't sell any more stocks because they've none left to sell. With just a bit of sanity in the world then the UK market really ought to do OK.
EDIT: and Camellia (LON:CAM) was also discussed, I think. It's a weird one, but looks very cheap. I hold a few.
timarr
Another useful chart from the free weekly Pension Craft email....
fwiw, Michael Burry has been reported as taking a new position in Microsoft (NSQ:MSFT).
Burry recently announced in a post that he has taken a new position in Microsoft, one of the largest stocks in the world by market cap. Burry said he sees an opportunity in "bombed out software and payment stocks" and is concerned about parts of the artificial intelligence sector.
While Microsoft is undoubtedly expected to be a beneficiary of AI, the stock seems to be facing headwinds driven by AI-related concerns and also how software will be impacted. In the first quarter of the year, the stock fell 23%, its worst performance since the Great Recession.
The purchase of Microsoft follows recent software-sector purchases by Burry, including PayPal, MSCI, and Salesforce.
While I don't have direct access to Burry's Substack, we know from previous reporting that Burry believes software has struggled due to what he calls a "reflexive positive feedback loop" between declining software stock prices and the stress on software debt associated with these companies. However, Burry does not believe this dynamic can continue for much longer.
While Burry did acknowledge that AI will have serious impacts on several software companies, he is not worried about the stocks he has chosen after conducting a forensic analysis.
https://tinyurl.com/8c4arrh3
SRT Marine update on Wed 29th at 0830
Wed, 29
Breedon (LON:BREE) , AGM
Hargreaves Services (LON:HSP) , GM to ratify tender offer
Warpaint London (LON:W7L), FY
Hi Mark
Please can you add
Likewise (LON:LIKE) Final Results for the year ending 31 December 2025 will be announced on 28 April 2026