Trading the Trend - Is this a sell-off?

It never ceases to amaze me how quickly things can change. Sentiment can change overnight, and the Dow Jones Industrial Average falling sharply has caused many to sound the alarm bells.
If we put this into context, yesterday the Dow Jones erased two days’ worth of gains in one day. This is hardly cause for concern.
The S&P 500 also had its biggest one day drop since June. That’s three months ago. It’s almost as if people have forgotten what proper falls were like, when everything was in freefall back in March.
Pullbacks are a part of any market. Nothing goes up in a straight line. And as you should have either physical stop losses set, or alarms and mental stops in place to get out at certain point, you shouldn’t need to worry.
It is becoming clearer to me every week (to me, at least) that Covid-19 is not the killer pandemic that we originally all feared. Or if it is, then it is being significantly weakened by social distancing, masks, and a focus on hygiene and cleanliness.
It often surprises me how many men don’t wash their hands after visiting the bathroom in restaurants. This is disgusting, but I’d bet that many of those non-washers have become converts.
Whereas previously people completely disregarded the virus pre-lockdown, in the post-lockdown phase people, in general, are more careful.
What does this mean for the market? Well, Revolution Bars Group announced a Trading Update yesterday that Paul covered in the Small Cap Value Report.
I don’t believe that sales down by 22.5% in the last four weeks to 29 August 2020 is terrible. It’s certainly not great, but the base case expected was 55% of prior year sales with only marginal improvement in September and October. So long as a second wave doesn’t come and kill us all, I would expect things to gradually get back to normal. It’s hard to believe that we spent several months in lockdown, with no access to restaurants or anything but Tesco. And yet it was only six months ago. People have short memories.
I am long Revolution Bars (LON:RBG) from the placing but I am not tempted to add. Rather, I see the Trading Update as evidence that things will slowly but surely return to a sense of normality. Covid-19 has been a catalyst in driving working from home, and so things won’t be the same, but I assume people will do normal things like spend money and go out. But I can always be wrong!
At the moment, I don’t see anything to worry about in this pullback. But if markets to start to fall sharply, then I’ll spend time looking for short trades and then hit them as my entries are triggered. Don’t make the mistake of being overly bullish or bearish as I did in March, expecting things to fall further after a sharp rally. Rather, let the charts tell you what to do.
Eve Sleep
I hold eve Sleep (eve Sleep (LON:EVE)), and the company announced an update yesterday that it would be ahead of expectations. At the current price of 6p, the market cap is just under £17 million. It also had over £9.1m of cash as of 30 June 2020. It’s therefore logical to assume that in the good trading conditions the company has seen this increase. But going on those figures, this gives the company an Enterprise Value of £7.9 million.
This makes it a tiddler, but I believe the stock represents a multibagger opportunity. The company has changed strategy from chasing growth at all costs, and now has a positive marketing contribution. It’s also building cash, and so there is zero chance of it going bust anytime soon.
Note the commentary from chief executive Cheryl Calverley in yesterday’s update. “Whilst economic uncertainty is likely to remain for some time, we are starting to look beyond our rebuild strategy to the next stage of growth”.
The company has a H2 weighting and so the company has scope to even beat its revised guidance. But even if it didn’t, in my view the reward still far outweighs the risk here. I’m currently 100% up from my first buys, but I will review the position on the results that are due mid-September. It’s one for the watchlist at least.
Let’s look at the chart.
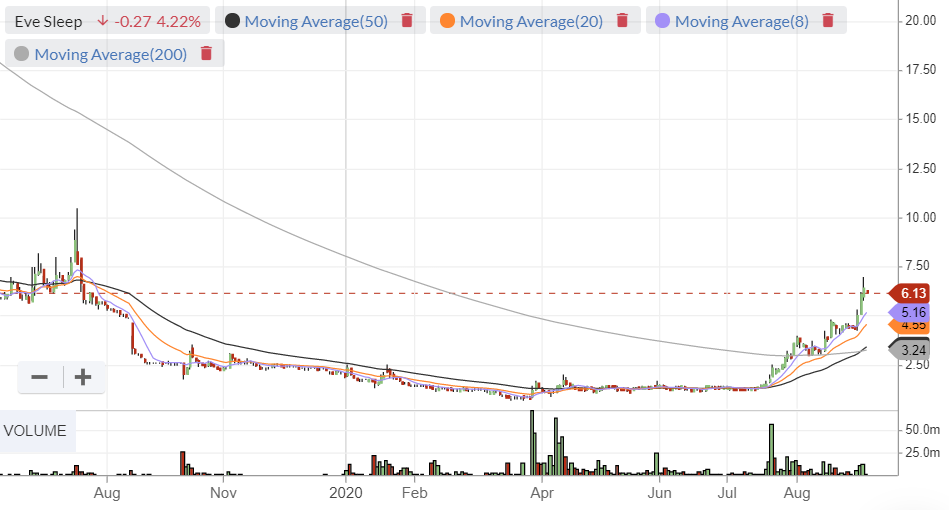
We can see a long drawn out base play out between April and mid-July, when the stock started rising on increasing volume. To me, this looks like it could be an early stage 2 stock, and it’s backed by strengthening fundamentals. I’m not an investing expert and I’ve only looked at the basics, but the price and the cash flow are now pointing in the right direction.
I do intend to add to this position at some point, although at the moment the price is looking extended. Rather, I’d like to see the stock build another base and let some profit takers out, and new traders and investors in, and then break out of a range and continue.
Shanta Gold
I have been looking at Shanta Gold (LON:SHG) recently, as I feel it could be building a stage 2 base.
Here is the chart:
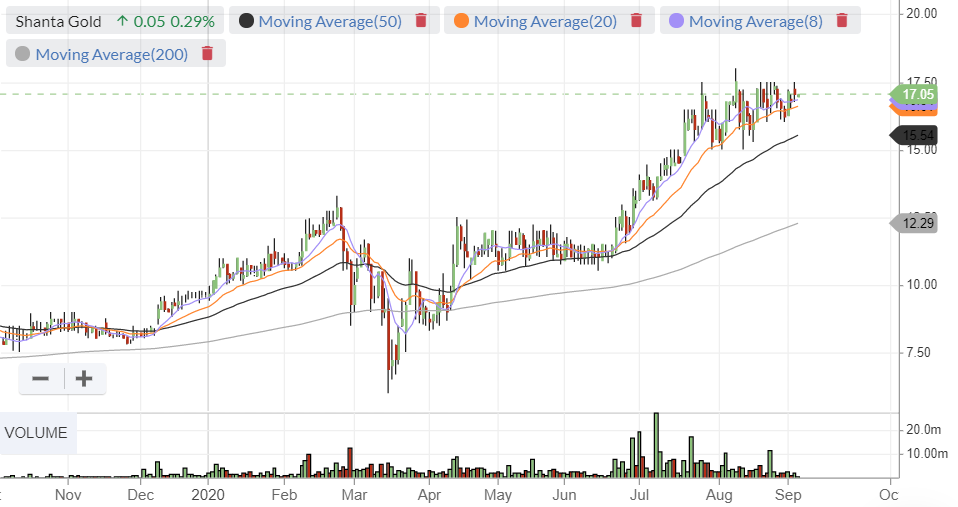
We can see the brutal sell off, only for the stock to sharply recover.
From the end of June we can see a strong uptick in volume and the price appreciation.
Volatility and volume also seem to be declining in the last few weeks, which is a sign of consolidation. This is ideally what I’d like to see in eve Sleep. Looking closer at Shanta’s (£SHG) consolidation, we can see an ascending wedge. I’ve drawn this on.
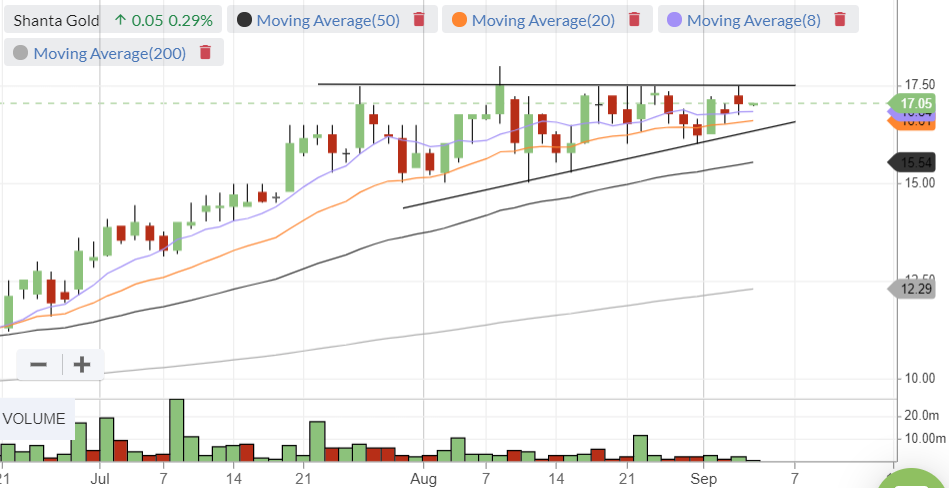
If the price can break through 17.5p I’ve got an alert to take a long position. I’d likely put my stop underneath the wedge, outside of the stop loss liquidity that will be around on the wedge’s line.
You can download your copies of Michael’s books at www.shiftingshares.com
Twitter: @shiftingshares
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
21 comments
Hey, Michael, perhaps you need to get some new friends if your homeboys don't wash their hands after using the facilities. We're not all filthy pigs.
You're assuming that I frequent male toilets with my friends and that I believe "all" men are non-hand washers. Those assumptions are both wrong!
I see Eve’s premium mattress is Which’s top best buy and their original is also highly rated. Good, free, marketing.
Yes Peter - I saw that. EVE is a marketing company imo not a mattress company, or a 'sleep-wellness' company as the company calls itself.
However, it definitely helps if you have a good product to market.
Moving hastily on from the endlessly intriguing subject of hygiene in public toilets, my main concern with Eve Sleep (LON:EVE) is the spread of 3.3% - that in effect means that your trade is down 3.3% at least from the start: which must increase the risk and eat substantially into the profit margin. Do you factor in spreads when you make a trade?
I do factor spreads when making a trade. This isn't an intraday trade though.
With something like GAW yesterday, I was in at the auction and selling within the hour. It's liquid, and a very tight spread.
With EVE, my first buy was 3.2p, and I'm not looking to scalp this. It's a longer-term swing trade.
Traders should always consider the spread as trying to make 10% on a stock with a spread of 10% really means we need to make 20% just to give half of that back in spread.
Interesting stuff as ever Michael.
I feel a bit embarrassed therefore to offer a response of zero real value.
However, in my defence I am in the middle of a horrible bit of data reconciliation, rendered much more difficult than it should be by the LSE, so serious contemplation escapes me. Plus its the weekend!
I saw an interesting observation on this point back in March, when the prevalence was perhaps at its height (I have amended the quote slightly in the interests of public decency).
"There is more chance of there being coronavirus on the taps in a public toilet, than on my [ahem] 'John Thomas!"
Perhaps though this went beyond witty, into profundity. I was in a Dunelm store cafe today and the offer hand sanitiser outside of the toilets. Wash and wash again, you know it makes sense!
Gromley:
"There is more chance of there being coronavirus on the taps in a public toilet, than on my [ahem] 'John Thomas!"
The taps in public toilets are reservoirs of infection and should, in my opinion, never be touched unless you have good reason to believe that they are cleaner than your hands (or other parts).
That's a fair point. But logistically, one could use a good dollop of soap, wash thoroughly, then turn the tap off with the back of one's hand? Many taps come on automatically these days.
There is, of course, then the problem of opening the door if it has a handle. If everyone has washed their hands, then this should be fine, but we know many don't wash their hands.
I opt to try to grab the handle at the bottom, which is where nobody else is likely to grab it.. Unless they are using the same logic as me, in which case it's likely that many are grabbing it.
Washing hands in toilets does present a series of conundrums. That much is clear.
Is this a sell-off? Well, yes. It certainly felt like a sell-off to me.
The FT has led with articles about SoftBank's use of Call Options:
"SoftBank unmasked as ‘Nasdaq whale’ that stoked tech rally": https://www.ft.com/content/755...
"SoftBank up $4bn on founder’s aggressive US stock options bet": https://www.ft.com/content/53a...
I must confess that I really don't know what to make of this. SoftBank was already 'long' on Technology through it's holdings. To take out call options that gives them upside potential while limiting their downside exposure on such a large scale seems to have forced other to cover their exposure and go 'short' Technology. But the strategy seems to have worked for them because they made the bet earliest.
What does it mean for ordinary private investors? I suspect ... Hold On for Dear Life? ... Famous last words!
Hi would you mind explaining how call and put options work from my basic knowledge you buy a call if you think an asset is going up put if its going down, you put down a small percentage up front compared to buying the physical asset and have a set time period to decide to stump up the full price to fund the true cost of buying the asset or selling the asset is that it in a nutshell thanks.
Yes, I think you have it in a nutshell. As usual Investopedia have a detailed explainer: https://www.investopedia.com/t...
What I dont understand is why. SoftBank were already heavily long technology. This makes them massively long - and forces the option sellers to bet against them to hedge their potential losses - hence the ramp up followed by a snap back down.
It's a risky strategy, but then it could be argued that Softbank has acted in a risky manner previously.
There was an FT article recently that posited that Softbank has been one of the reasons the S&P had risen so highly.
A quick look at at the 2019 results for eve Sleep (LON:EVE) show that for a revenue of £23.8m, the company had cost of sales of £11.2m, marketing costs of £12.1m and distribution expenses of £2.7m (when you add in the admin cost of £9.9m, its total loses for the year were £12.1m).
So for every £1 of sales, it spend c50p on cost of sales, c50p on marketing and 10p on distribution. It is basically losing money every time it makes a sale!
Why are the marketing cost so high?, the company would argue that this is due to it trying to create "brand awareness", another explanation could be that it is basically trying to sell very expensive mattresses (why suffer the hassle of going to a shop to buy a £500 mattress, when you can enjoy the comfort of ordering a £800 Eve Sleep mattress online!).
It is unclear why the mattresses are so expensive, when they have eliminated the cost of expensive showrooms (also do they really need to spend £9.9m on admin costs?).
Eve Sleep was a favourite of Woodford, as he saw it as a 'market distruptor', this might be true, unfortunately this market distruptor approach is easy to copy. After I searched for Eve Sleep through google, my facebook feed has now been inundated with adverts for mattresses from Simba, Nectarsleep, Rem-fit, Emma Mattress and Otty (but crucial not from Eve sleep).
Ofcourse there might be a small chance that this company can becomes a multibagger (maybe the charts shows something I can't see) and maybe the six month result on sept 15th will be even better than expected, however the chances of this are likely to be very slim given the very poor fundamentals the company faces.
You make some good points smegster. I would never purchase a mattress online. It seems a rather silly idea. Who can be bothered with the hassle of returning it and jumping through all the hoops necessary?
You are right that eve Sleep has been a terrible company, and terribly run. It has a complete dog.
However, you are looking at the 2019 results. I have only taken an interest based on RNSs from recent trading and the chart.
Whether it can turn around properly and profitably remains to be seen, but for now the price action is very strong and there appears to be a fundamental catalyst in play.
Once again a great example of how you read the charts Michael, which is really appreciated, Your future possible position is very helpful and has been noted too. I hope to see lots more chart analysis like this as I always learn from it and your visual approach to investment decision making. Many thanks. Chris
Thank you Chris. I've included lots on charts in my books available from my website too.
However, I'm not an investor! These positions are all trades. If they start to move downwards and trigger my sell points then I will sell. I don't average down.
Thank you, Michael. Another interesting write-up.
Eve Sleep (LON:EVE) has a surprisingly low Altman score at -9.19 . Year end cash would suggest that the risk of bankruptcy is likely to be very low. No doubt the P&L a/c has weighed heavily upon the score.
Thanks for your comments and especially on Shanta Gold (LON:SHG) which I hold too.
finnCap's note on EVE's trading update issued yesterday says they expect year end cash to be £5.0m (raised from £4.2m). Good, but much lower than the £9m the company talk of. Not sure why the disparity.
Me neither Terry. That seems a rather large disparity. Above my pay grade though as the chart takes priority!