Trading the trend - three stocks to avoid amid Coronavirus disruption

The market has been all over the place this week, with the Dow screaming around like a runaway mine train.
Before we look at three stocks I think should be avoided – let’s look at the three stocks that I thought had been unfairly sold off and could have presented some trading opportunities first.
Reach
Reach’s share price is almost flat. Further downside was seen only for the stock to snap back upwards. In a week where the market tanked I see this as further evidence that this is a strong stock, and so it stays on the watchlist to trade long.

GAN plc
With GAN, the hammer identified last week was the signal for a strong surge this week with the price tagging 165p. Hammers on heavy volume are a good reversal indicator, and with the market rising on Monday GAN also saw the benefit.
Volume shows interest in the stock, as for every seller there must be a buyer, and so heavy volume hammers are candles I keep an eye out for.

Sylvania Platinum
The positive market also saw a boost for Sylvania Platinum. It’s nicely above the price published last week, almost tagging 60p.

There are many stocks that didn’t see a positive week, and so it seems (at least in this limited small sample) that my trading ideas were good ideas. It’s impossible to know what will happen next week but I’ll continue to monitor these three stocks closely.
Being able to generate ideas to trade is important, because without ideas you don’t have any trades. Sometimes thinking about the bigger picture and what it means can throw up several opportunities.
Three stocks to avoid if Coronavirus hits
Coronavirus is a tetchy topic these days. Everyone has an opinion, and people have fallen out with each other and are getting themselves increasingly bent out of shape.
What (I hope) we can agree on: Coronavirus, or Covid-19, will hit local economies globally. The significance of this is debatable. An anecdote I heard from a friend (with no vested interest in lying) is that he knows a taxi driver, who is usually fully booked with airport and cruise runs. But now he has had 30 cancellations in seven days. It has cost him thousands, and as a result sees him making cutbacks for his own family.
The economy is just a machine of transactions. A reduction in transactions naturally affects other transactions too.
We can also agree that humans are not rational. Currently, there are people who don’t quite have all their mugs in the cupboard stocking up and clearing shelves of toilet roll. If we are to be swamped by hordes of Coronavirus infested zombies, toilet roll would not be my priority.
A company director told me on Friday that they cannot buy hand sanitiser anywhere. In just two weeks, when global equities were not pricing in any downturn in the economy at all, we are now at the stage where people have lost their marbles.
So what else will be hit? If people are scared, then logically they’ll avoid crowded places. And that surely means the High Street.
Marks & Spencer
I’m no fan of Marks & Spencer. The chart is in massive decline, and its clothing and home offering is uncompetitive (evidenced by declines in like-for-likes). The company also has a big JV gamble with Ocado. Marks & Spencer has a large amount of debt at £4.13bn (not a problem just yet) and razor thin profit margins.
But what I see is the chart.
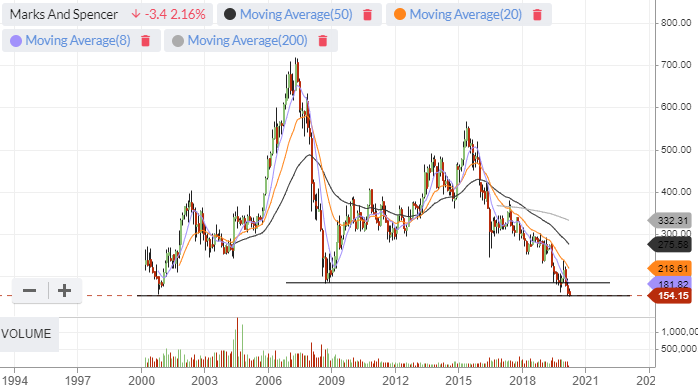
The price is below the 2008 support, and through the all time low printed back in September 2000.
Every downtick in revenue seriously hurts pre-tax profit. I don’t have precise figures for the age demographics of M&S’s customers, but this a shop I associate more with the elderly – those who are going to be most affected by Coronavirus.
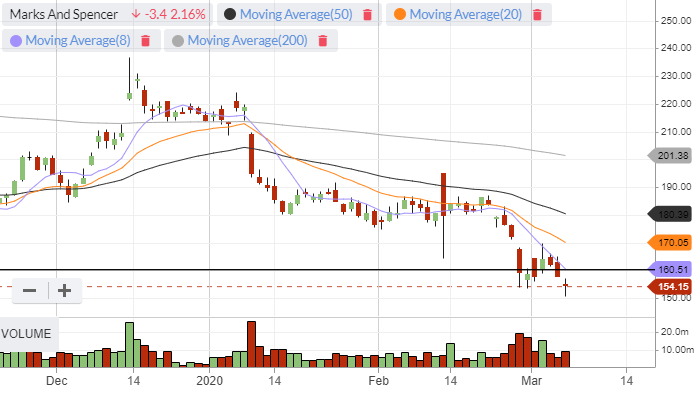
So whilst the chart alone tells me to short Marks & Spencer because it’s through two significant support zones, I also think any pandemonium is not likely to have any positive effects on the business.
Card Factory (CARD)
I have identified CARD as a short in the past as my generation doesn’t bother with cards. Longer term, I think this is a dying business model, and that any decline in like-for-likes will be difficult to reverse. The company issued a multi-year profit warning in January and a ‘review of strategy’.
Looking at the chart, it too is breaking down through all time lows soon.
Card Factory relies on heavy volume. Many of its units are in extremely high footfall areas, and I think it’s fair to say that a decline in unit revenues won’t necessarily see a matching increase in online revenues.
Restaurant Group (RTN)
Restaurant Group is a collection of fatigued brands that struggle and will (at least in my opinion) continue to do so unless it does something drastic. Frankie & Benny’s is an Italian-American chain that has created discount addicts who will no longer pay full price. I like Italian food. And I like American food. But nobody I know likes this fairground of refuse.
Alongside Chiquito (marginally better) and Wagamama, which the company bought in order to turn itself around, these three brands make up the majority of its units.
The chart says more than I ever could.
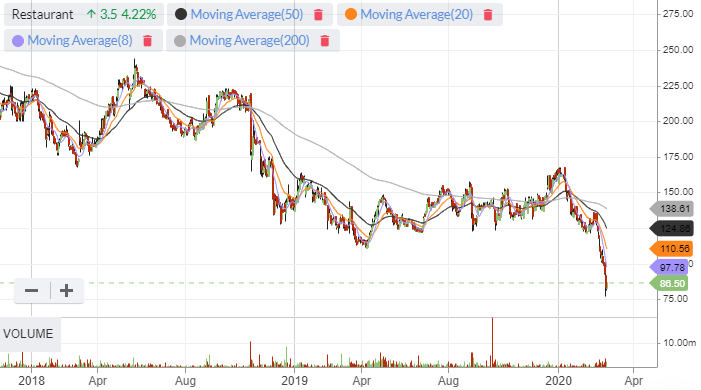
Since the end of 2018, the price has fallen off a cliff, and has halved from its peak already in 2020.
If we look closer, the price has capitulated in recent weeks. I wouldn’t short this now, even if the price takes out the all time lows, because I think the move has happened. The time to be short has been the last few years, and we would be coming late to this trade where the risk/reward is no longer in our favour.
It’s better to be at the start of a move than be the liquidity for shorters who will be covering. One could argue that MKS has been declining for years, but the market cap is a lot higher, and the stock is now breaking through significant support. Perhaps I’m wrong, and there could be a lot more in Restaurant Group’s share price to fall. The company did mention that like-for-like sales are up 5.3% for the first six weeks of 2020, but a reduction in footfall could see the future figures damaged.
StockRanks Out of interest, here are the StockRanks for MKS, CARD, and RTN.
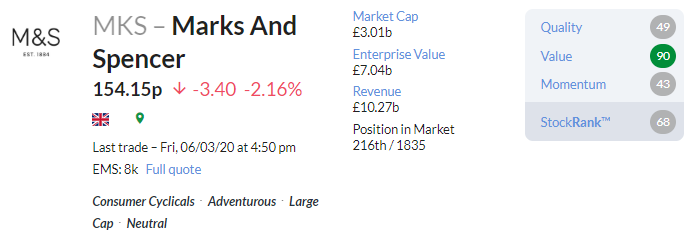
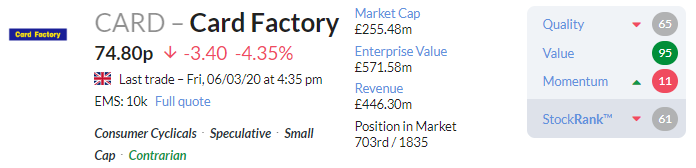
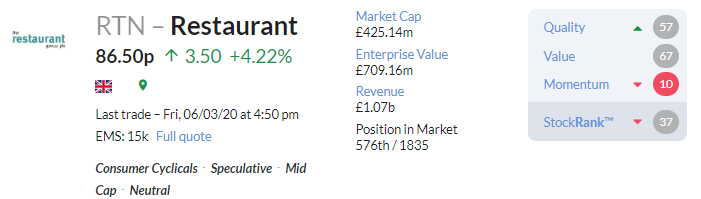
Value appears to be a consistent theme here. That surprises me, but I admit that fundamental analysis is not a quality of mine. These are potential trades ideas only, and I’m not interested in the long term here.
Takeaways
Marks & Spencer has broken through all time lows – watch for any rally to trade the breakdown short
Card Factory may offer a short trade through the all time low – but the spread is wide here, therefore position size should be reduced.
Restaurant Group is no longer a short as we’d be coming to the trade late, but I definitely would not want to be long
You can download Michael’s free trading handbook which covers position sizing and risk management from his website at www.shiftingshares.com
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
9 comments
I am now short RTN despite saying I wouldn't short it. However, it's only a short term trade for me. When stocks are falling as fast as they have been you can't short them quick enough!
I agree, didn't buy them, wouldn't buy them.
Only three stocks to avoid? How about everything except Gold for the next few months until the Covid-19 infected numbers start to decline?
Fair point, Derrick. However "Avoid all stocks" wouldn't have made much for an article!
There will be lots buying With Sympathy cards before long.
And they have quite a well established online business
I agree with you with regards to cards, as I don’t like cards either, however the local one to me is always busy. It would be interesting to see if other Card Factory shops are busy as well. I am interested in investing in Card Factory (LON:CARD) though, I will keep it on the watchlist.
Reading branch is always heaving - only ever go during the week but always a queue of 5-6 people
Card Factory (LON:CARD). I dropped into one of their shops in Ware and then in Welwyn on the same Saturday a couple of months ago and found them both to be very busy. Have had similar anecdotal reports elsewhere so always surprised at their results