Travis Perkins gets Britain building

Travis Perkins is Britain's largest builders' merchant and is benefiting from a recovery in market activity. General election uncertainty hit the sector in April but the market is now set to pickup. Travis Perkins is therefore well placed to see further sales momentum and improve its return on capital.
One way to gauge the strength of a economy is to count the number of construction cranes in major cities. In the UK another test is to count the number of green Travis Perkins trucks whizzing along to building sites.
Travis Perkins plc is the largest supplier of building materials in the UK and has a “unique breadth". This includes consumer brands like Wickes and general merchanting brands like Travis Perkins and Benchmarx Kitchens and Joinery.
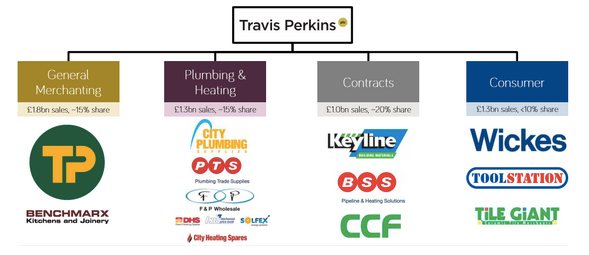
Travis Perkins can supply it all: division brands, sales & market share
Source: Travis Perkins investor presentation
The most important division is General Merchanting which generated £183m adjusted EBITA in 2014 – 47.6% of the group total. This area has the highest EBITA margin at 9.85 and achieves a lease adjusted ROCE of 16%.
The Consumer division generated £77m of adjusted EBITA in 2014 with a margin of 6% and a lease adjusted ROCE of 7%. Contracts came in at £72m of adjusted EBITA in 2014 with a 6.7% margin and a 13% lease adjusted return on capital.
Plumbing & Heating division came in at £65m EBITA at a 4.8% margin and a 9% lease adjusted return on capital. Clearly the three smaller divisions have some way to go to catch-up with the returns on General Merchanting.
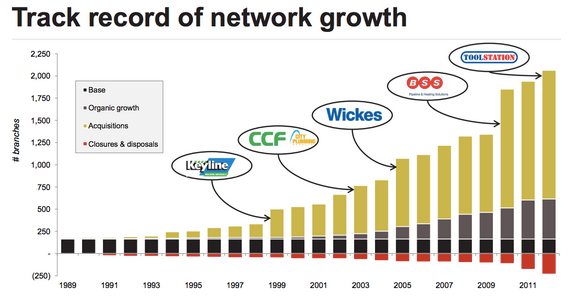
Travis Perkins' strategy is to exploit its “scale advantage", develop new customer propositions and expand its network. Organic growth and acquisitions saw the branch network increase from around 200 in 1989 to nearly 2,000 in 2013.
Source: Travis Perkins investor presentation
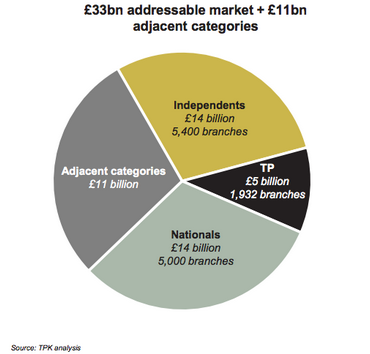
At a Capital Markets day in December 2013 the group estimated the addressable market at £33bn (£26bn in trade and £7bn in retail). The builders' merchant sector is fragmented with over 3,000 independent firms with 5,400 branches.
There is also scope to move into £11bn of adjacent market categories with acquisitions previously having been the key drive of growth. The last major purchase was Toolstation while Wickes was bought in 2005.
Market view: Significant structural opportunities for growth
Source: Capital Markets day presentation
In terms of guidance and Travis Perkins is aiming to continue to outperform the majority of its markets. General Merchanting has sector leading operating margins and the aim is to boost margins at the other three divisions.
The group is also aiming to lift its lease adjusted return on capital by 2-3% over the medium-term. In 2013 the figure was 10% and in 2014 it increased to 10.4% which suggests further scope for expansion.
Turning to profits and Travis Perkins is targeting “sustainable double-digit EBITA growth per annum." In 2014 Adjusted EBITA increased by 10.3% to £384m which outstripped the 8.4% growth in revenue to £5.58bn.
Market backdrop and trading
The uncertainty surrounding the general election in the UK has hit construction growth. April saw the weakest construction PMI since June 2013 at 54.2 which was a significant drop on the 57.8 reading in March (above 50 means growth).
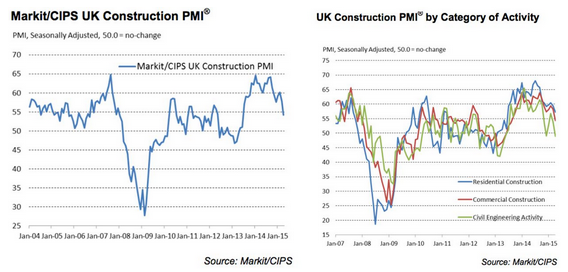
However, activity should now bounce back given that the Labour Party, with its recent anti-business rhetoric, failed to win power. The Conservative Party, by contrast, is looking to boost construction in order to lift UK economic growth.
Looking at the group's first quarter update (22nd April) and Travis Perkins appears to be optimistic. This was as Q1 like-for-like sales increased by an impressive 5.1% and total sales rose by 7.2% on a year ago.
By way of context there was a 7.3% jump in like-for-like sales in 2014 and a 5% increase in 2013. Some of the momentum is due to a recovery in house building which looks set to continue given that demand outstrips supply.
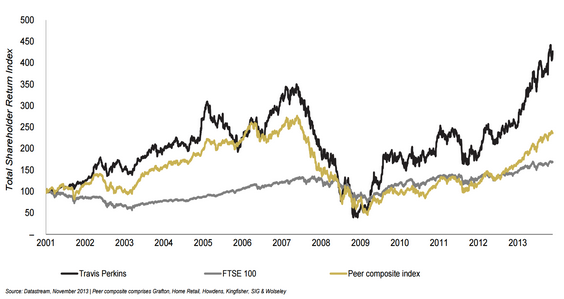
Travis Perkins has beaten the market and its peer group
Source: Travis Perkins investor presentation
Summary and valuation
Travis Perkins has a broad offering covering general Merchanting and the consumer space with brands like Wickes, Toolstation and Tile Giant. This diversification allows the group to offset weakness in any one area.
The leading market position of Travis Perkins will also allow it to generate higher returns than peers. Despite a strong track record of growth there remains scope to continue to expand given the fragmented market backdrop.
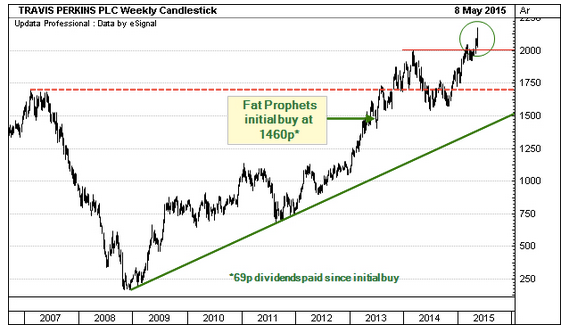
Turning to the risk profile and the shares fell from £16.5 in 2007 to around £2 at the end of 2008 as the financial crisis took hold. This underlines how negative investor sentiment can savage the valuations of cyclical businesses.
However, the share price has more than recovered to around £21 today and is underpinned by the UK recovery. The balance sheet risk profile has also started to fall with lease adjusted net debt flat in 2014 as profits jumped.
In terms of the price to earnings (P/E) metrics and the forecast for 2015 is 16.2X which falls to 14.5X in 2016. Looking further out to 2017 and the forecast P/E is 13X which falls to a relatively modest 11.3X in 2018.
Net debt is expected to fall to a marginal level by 2017 while the dividend yield is expected to increase from 2% in 2015 to 3.5% by 2018. There may be scope for special dividends, in our view, if market conditions remain strong.
Given the market leading position of Travis Perkins and scope for growth the shares offer long-term value. The sector is cyclical but the group bounced back from the financial crisis and is set to reduce its balance sheet risk profile.
This report was produced by Fat Prophets Senior Research Analyst, Andrew Latto.Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?