UK Value Investor model portfolio: 2013 half year review

I started the UKVI model portfolio back in March 2011 to show that the UKVI stock screen and investment strategy work, and also as a way of teaching investors how to use them to pick stocks in the real world. Since then the portfolio has grown from zero to 26 holdings, with a total of 32 buy decisions, 6 sell decisions and 89 dividend payments.
The portfolio began with £50,000 of virtual money and tracks every buy and sell decision, including any associated stamp duty and trading commissions. Each trading decision is announced before a trade is made, and the process behind that decision is fully documented.
Because I think this is a sensible way to invest, I have the vast majority of my own pension funds invested in all the stocks in the model portfolio. So although this is a model portfolio I take it as seriously as I would my own money, because it effectively is.
Basic goals of the portfolio
These are relatively simple:
- High Yield – The portfolio should always have a yield higher than the FTSE All-Share.
- High Dividend Growth – The portfolio should grow its total dividend faster than the FTSE All-Share, whether dividends are withdrawn or not.
- High Capital Growth – The portfolio should grow its capital value faster than the FTSE All-Share, whether dividends are withdrawn or not.
- Low Risk – The dividend income stream and capital value of the portfolio should be not be significantly more volatile than those of the FTSE All-Share, and each company in the portfolio should be a relatively “low risk” business.
- Low Effort – The portfolio should be easy to manage, taking no more than a few hours each month to make any trading decisions.
- Fully Transparent – Everything about the portfolio should be open and transparent, from the stock screen to the investment checklist and more.
A defensive value investing strategy
The portfolio follows a defensive value investing strategy, which means that it follows the guidelines for defensive investors laid down by Ben Graham, who was Warren Buffett’s mentor.
Graham said that the defensive investor should focus on companies that are large, prominent and conservatively financed, with a long record of dividend payments. He also said these companies should be bought when the share price was reasonable in relation to the company’s average earnings over previous years. Finally, he said that shares of growing companies were preferable to others, if purchased at a suitable price.
In summary then, the approach is to look for reasonably large, profitable, dividend paying companies that are growing consistently, and to buy them when the price is low relative to historic earnings and dividends.
Benchmarks and target returns
I think it’s important for an investor’s portfolio to have a benchmark, otherwise how do you know if you’re doing a good job managing your money?
There are lots of alternative benchmarks and the portfolio targets several of them:
Low target (Aberdeen UK Tracker Trust minus 6% per year) – Pete Comley produced a detailed review of active, private investor performance in his book, Monkey with a Pin. Pete found that active, private investors were losing anything up to 6% per year when compared to market indices.
Therefore, the portfolio’s first target is to beat most active investors, which in this case means having better annualised returns than 6% less than the Aberdeen UK Tracker Trust, which tracks the FTSE All-Share.
Medium target (Aberdeen UK Tracker Trust) – An idealised passive investor of UK stocks might well decide to invest in the Aberdeen UK Tracker Trust as it tracks the whole FTSE index. They would buy it and hold it forever and therefore get exactly the returns from this trust. Most investors don’t even meet this target, and academia generally implies that it can’t be beating without luck or taking more risk. I disagree, so this is the portfolio’s second target.
High target (Aberdeen UK Tracker Trust plus 3% per year) – This is the target that I think is reasonably achievable over time. Why 3%? It’s somewhat arbitrary, but investment returns come from three sources: dividends, earnings growth and changes to valuation ratios like the PE ratio. I think that over time the UKVI model portfolio can achieve an additional 1% each from higher dividend yields, higher earnings growth rates and from buying low and selling high in order to capture positive changes to valuation ratios.
Note that Neil Woodford, the much celebrated fund manager, has achieved 12.6% compound total returns over the past 25 years with his Invesco Perpetual High Income Fund, compared to 8.9% from the FTSE All-Share. That’s a 3.7% annual outperformance for 25 years, after fees of course. So 3% outperformance for the UKVI model portfolio seems like a difficult, but achievable target.
Reviewing long-term progress
The portfolio has been running now for 28 months. One of the biggest problems that many investors have is getting their heads around the idea that investing is a long-term activity, and that it can only sensibly be measured over periods of many years.
Generally 5 years is seen as the minimum period for review, but realistically it should be closer to 10.
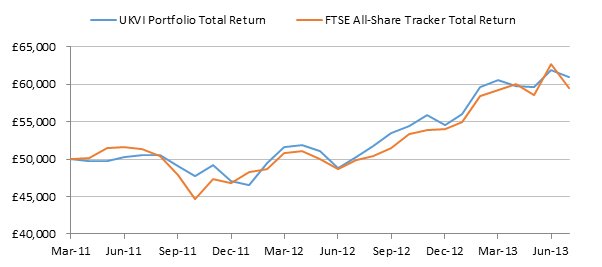
However, not everybody wants to wait 10 years before comparing themselves to their benchmark, and so you can see the total return results below.
The easiest thing to measure in the short-term is dividend yield. Currently this is 4.6% for the model portfolio compared to 3.2% from the index tracker. This is in line with the main target of beating the market yield by 1%.
Dividend growthAnother useful feature to measure in any portfolio is dividend growth, because dividend growth ultimately drives capital growth.
In this case, with dividends reinvested (which boost growth of future dividends), the model portfolio has grown annual dividends by 24.6% in the past 11 months, while the index tracker has grown dividends by 10.3%.
Total returnTotal return from a portfolio is another easy thing to measure, but it is hard to draw conclusions from total returns in the short-term. Woodford’s record is so impressive precisely because it is so long at 25 years.
However, in the two-and-a-bit years that the model portfolio has been running it has matched, remarkably well, the FTSE All-Share, despite holding less than 30 stocks compared to the 600 or so in the index.
To date the total returns are 22% compared to 19.1% from the index, which is an annualised return of 8.9% and 7.8% respectively.
So far then the model portfolio has beaten the market index, which is good. But in all honesty, it’s over such a short period of time that random share price volatility will still be the dominant factor. Still, it’s good to be a long way clear of Pete Comley’s “minus 6%” benchmark.
Low riskIn terms of volatility the portfolio appears to be no more “risky” than the FTSE All-Share. Relatively low volatility is important because the fear caused by excessive volatility is one of the major reasons why most private investors underperform the market so badly.
What to expect for the future?
Unfortunately there is no way of knowing exactly how the markets or any given portfolio will perform in the future, but there may be a hint in the performance of past trades. Ultimately a portfolio’s performance must approximately match the annualised performance of the stocks that have been bought, held and sold over the years.
On that note, here are the results from all of the investments sold so far, not including one that’s being sold this week, which I’ll announce next week:
- Reckitt Benckiser – annualised return of 21%
- N Brown –annualised return over 100%
- UK Mail Group –annualised return of 34%
- UTV Media – annualised return of 90%
- Robert Wiseman Dairies – annualised return of 38%
These stocks were mostly sold when valuations were no longer attractive, and over time the average holding period is expected to be around five years.
Conclusion
When you’re reviewing your portfolio it’s critical that your portfolio has goals and targets, and that you have realistic and appropriately long-term expectations for both your performance and your portfolio’s performance. It’s also important to build a portfolio which is appropriate to you in terms of income, growth, risk and the effort required to maintain it.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?