VNT - Ventia: At your service

Ventia Services (ASX:VNT) is one of Australia’s largest essential services providers. You will likely never notice them much, but from putting fuel into an aeroplane through to mopping hospital floors, this large services business has an extensive presence with their over 35,000 workforce, servicing Tier 1 clients, crossing the sectors of defence, social infrastructure, mining, energy, telecommunications and transport. In summary, they play a key role in our nation ticking over.
Its history is storied. Without going into onerous detail, Ventia was the coming together of Leighton Contractors, Thiess Services and Visionstream. The company acquired Brookfield (formerly Transfield Services) in 2021 which formed the catalyst for the IPO later in 2021.
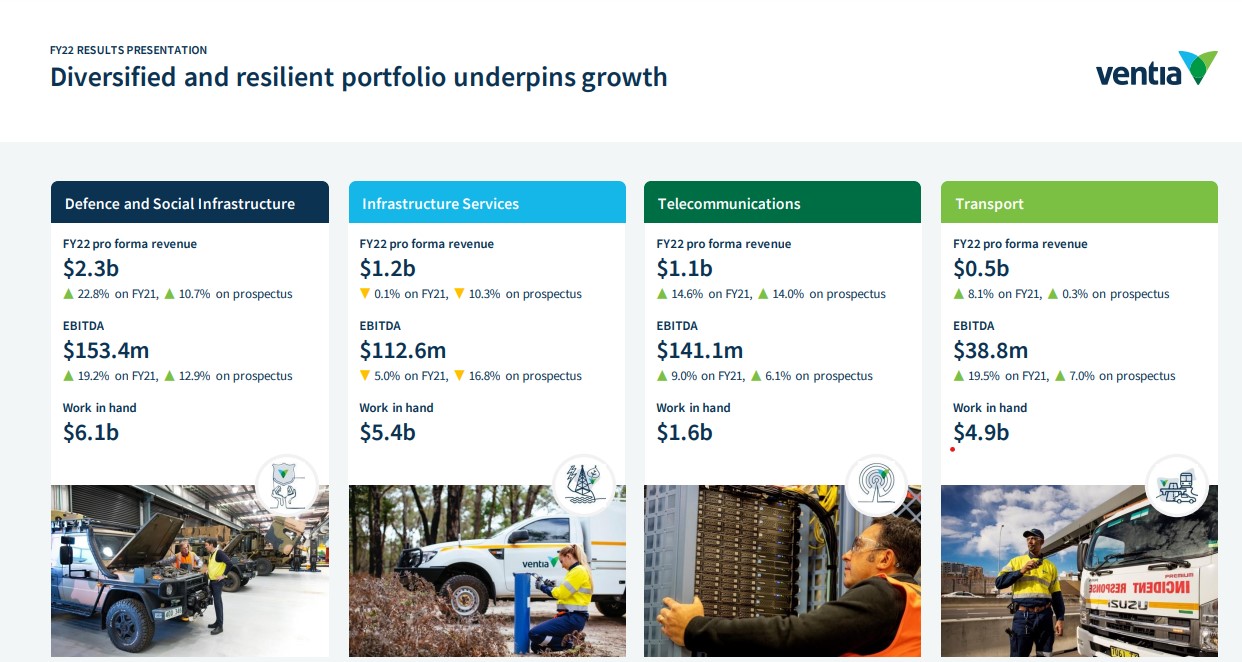
The company’s largest division by revenue is Defence and Social Infrastructure, however its most profitable in terms of Margins is the Telecommunications division where it manages some 1.5m assets across Australia and New Zealand.
The IPO
The company’s path to listing was far from smooth. Prior to listing in 2021, both CIMIC and US based private equity firm Apollo owned 65% of the business jointly. Initial plans had been that the offer be at $2.75-$3.15. But in a desperate bid to get the deal over the line, that price was slashed to $1.70. At such a bargain price the raising was quickly snapped up and opened at $2.10. However this stoked the fear of the ‘pump and dump’ narrative as the stock initially rose and subsequently fell over the next year.
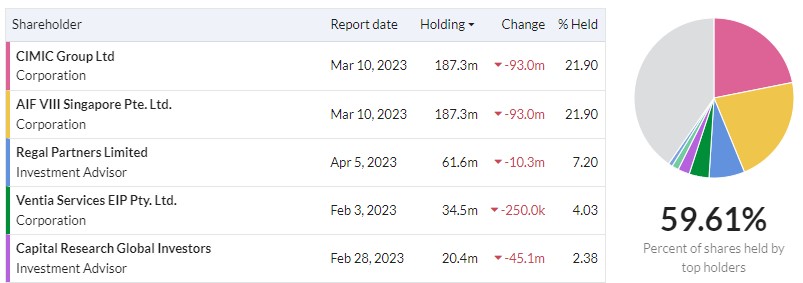
To complicate matters, the owners had made no secret that they would intend to likely exit their stake, and at the start of this month they started the process. They have done this twice now. Once in March and again at the start of this month.
What is remaining is circa 14% each (this will be updated in the coming days in Stockopedia.). The expectation is that they will continue with their selldown when the next escrow period arrives in 3 months time.
While some may see this as a potential negative, others will see it at a chance for liquidity to improve. The tight holding had often kept many Fund Managers on the sidelines. It also has hindered its ability to meet the requirements for inclusion in the storied ASX200 index. With a market cap of $2.6B, the only factor stopping it has been access to shares so I am fairly confident VNT is on the radar of Fund Managers and the question now is, should it be on yours?
StockRank
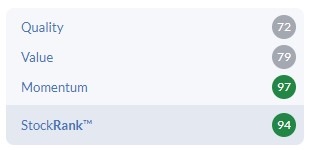
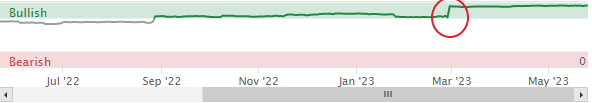
Overall the company ranks a 94. The result is driven in large part by the high Momentum score of 97. This, when combined with Quality and Value, which are certainly not disastrous, means overall it ranks well. The overall StockRank saw a sharp improvement following the company’s annual result delivered in late February when the score jumped from 76 to 93.
The biggest drag on Quality is the Altman Z2 score of 1.58 which puts it into the cautious zone. As with all things Bankruptcy risk score related, it is important to note that during good times the relevance of such a measure is less than when times get a little rough which is where it becomes essential. The Altman Z score measures a company's ability to safely absorb a shock to its business and not go broke as they sort things out.
For now this is not an immediate stress on the company, but should their business circumstances change it will be something to watch. The main catalyst for the poor score is the negative Working Capital figure (Current Assets minus Current Liabilities) which implies a potential issue with immediate liquidity if ever immediate funds are needed.
I expect this ratio to improve in the coming months as the company establishes more of an earnings history and consolidates its position as a public entity which will hopefully bridge the gap between trade payables and trade receivables..
However, I will definitely not ignore this number.
Services businesses over time have had a checked history with an unsettling tendency to go broke or close to it. This extends beyond Mining Services. My mind goes back to Spotless who after significant trouble in the early 2000s and 2010s was bought by Private Equity. Just to then be refloated, and with a subsequent botched deal with Downer who ended up owning 88% of an illiquid business, it eventually removed itself from the bourse in 2019. Long story short, I hope to see some improvement here as if you can’t control the amount you owe for services rendered to you, it can quickly get out of hand.
Latest Annual Result
The company delivered a very solid full year result adding weight to the idea that it will likely be able to stand on its own.
According to the company, it surpassed its pre-IPO targets and even achieved a record $5.1B revenue year for the first time.
This resulted in growth in NPATA to $180M . (NPATA is Net Profit After Tax and adding back amortisation of acquired intangibles - Note: the company still grew profit on a NPAT basis by $8M more than prospectus forecast). Guidance for growth of between 7% - 10% for FY23 Dec is inline with previous stated numbers. The fact they were resoundingly reaffirmed at the recent AGM attest to the idea that it should be met.
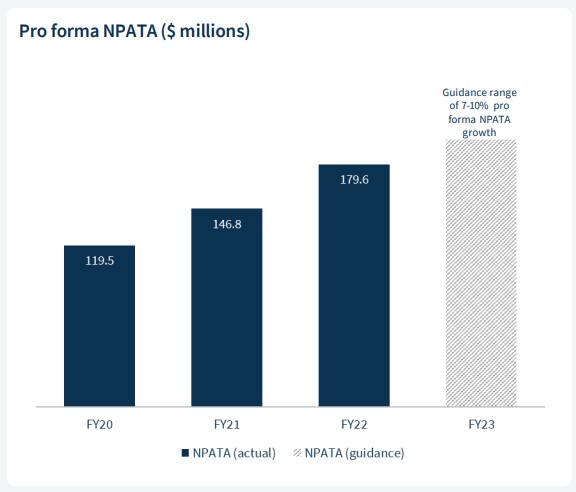
Source: VNT AGM
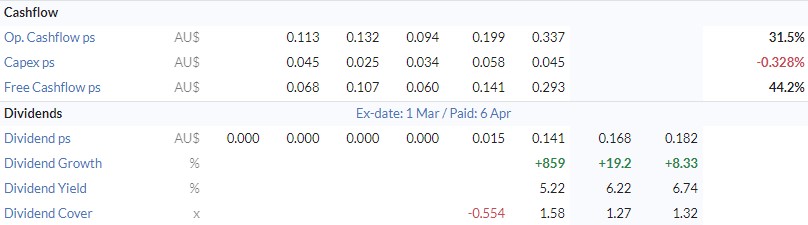
Other pleasing aspects of the result were improving margins (every percent counts in this sector), the company achieved strong conversion of profits to cash and it paid final dividends of 8.28 cents, taking their first year of dividends to 15.75 cents or 5.22% yield at current prices. This met their stated objective of paying 75% of NPATA in dividends.
Operationally the company also delivered some strong metrics with $18.0b work in hand (WIH), up 7.1% and they maintained an 85% client renewal rate, which is important as the average contract per client is circa 3-5 years. The good news is that most contracts are CPI linked so they have an element of defensiveness to earnings. To support the existing work, they also achieved $2.1b revenue from new clients and according to the company their pipeline looks strong with many industry tailwinds. More on that in a moment.
Outlook
The company is starting to see the analyst fraternity come around, putting aside the recent past of COVID, major holders selling down and a less than elegant IPO. This was certainly helped by the recent result. More brokers have become stronger in their conviction.
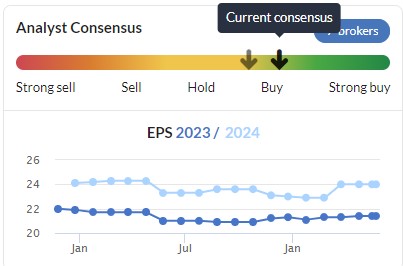
And they have also been upgrading earnings expectations more in line with company forecasts
Which to that end are quite simple with nothing too extravagant that doesn’t seem achievable. The company believes it can grow revenue on average by 7% - 10% per year. This is greater than the expected growth of the services sector which the company believes will grow at 6.6% CAGR (Constant Annual Growth Rate) taking the outsourced Maintenance Services addressable market size to a total of A$87B by FY26 (currently estimated at A$68B)
In a pleasing aspiration, the company also says that it will maintain a diligent focus on cash backed profits with an aspiration of 80% - 95% cash conversion. This will underpin a high conversion of profits into dividends which it estimates will be around 75% of NPATA with the intention of growing dividends into the future. This is an attractive indicator for those investors seeking income.
Risks
All companies carry an element of risk, and in the case of VNT, one major one is the availability of human capital to actually do the jobs they need. While the government’s plans to boost migration numbers certainly, this labour shortage is something the company must continue to manage.
Also as previously mentioned, the shares being sold by CIMIC and Apollo are also a downside risk. Notwithstanding the potential benefits as discussed, this potential sell side weakness may see some delay getting in the stock. The good news is that to date the announcement of any sell down has not impacted price significantly and therefore for the moment this looks contained.
Finally, Margins! As previously stated, margins are everything for these types of businesses. This is a highly competitive industry with pressures on the demand side with clients wanting cheaper priced services, and pressures on the supply staff with the lack of availability of human capital and rising wage demands. So margins will remain constrained. Small improvements will mean a lot, but inversely if they let them slip, that will hurt.
Conclusion
While initially shunned by many as a potential private equity dump, VNT is proving that its ability to deliver results warrants attention. As the number one provider of such services in Australia and New Zealand, it is not surprising to see the company is focused on cash generation and paying high yields to investors as a result.
VNT offers investors potential exposure to the largest player in a vastly growing services sector. Assuming it addresses the working capital issue as anticipated, then the stock is worthy of consideration for those seeking yield with some growth coming as a result of the expansion of the sectors it services.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
1 comment
Good review Elio, will put it on my watch list and do a bit more research