Why growth investors should take dividends seriously

Over the past fifty years, the average holding period for quoted shares has fallen from around eight years to barely eight months. There are various reasons for that, but one conclusion is that many investors have switched from thinking long-term to chasing growth wherever they can find it. While that strategy may work for some, it risks missing out on the powerful compounding effects of long-term capital and dividend growth. If that sounds a bit unexciting, take a look at the returns from a strategy which follows that approach and you’ll find it’s anything but boring...
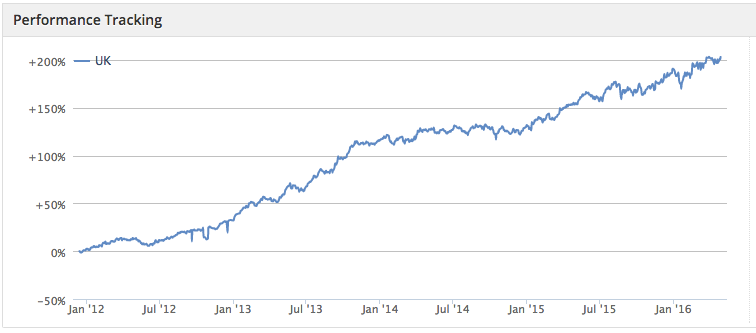
Of all the investment models tracked by Stockopedia, none have a smoother upward trajectory than Winning Growth & Income. This is a strategy that’s generated a 28.9% annualised gain over the past two years. In recent weeks - some four and a half years after we started tracking it - the capital gain on the quarterly-rebalanced portfolio has topped 200%.
Of course, as with all our guru screens, trading costs aren’t taken into account, which would take a lump out of that eye-catching gain. But neither are dividends, and in this case the presence of a high yield rule means that total return could have been much better. For example, the median yield of the 12 companies currently qualifying (which excludes dual-listed stocks) is 3.9%, and it’s been at that level fairly consistently.
What makes this a winning strategy… so far?
The guru-inspired strategies can be a useful barometer of what has and hasn’t recently been working in the market and how that changes over time. The consistency of Winning Growth & Income seems to be a simple set of rules that touch on three very influential drivers of returns - Quality, Value and Momentum, with the added bonus of above average yield. It’s a strategy inspired by work by US investment analyst Kevin Matras in his book, Finding #1 Stocks.
In terms of Quality, the screen looks for companies that are generating profits by looking for an above average Return on Equity and below average levels of debt. In the Valuation stakes, the shares should be trading on a below average rolling price-to-earnings ratio. And for Momentum, companies need to have seen recent analyst upgrades to their earnings forecasts for the next financial year.
In addition, the minimum market cap rule is set at £20 million, which opens the screen up to smaller - but not micro-sized - companies. But their Beta (the sensitivity of the share to the movement of the broader market) also has to be below average.
Growth with a dividend twist
In many respects, these rules echo some of what you see in GARP (growth at a reasonable price) strategies. It has hints of the Jim Slater Zulu Principle strategy about it, which has also performed very well since we began tracking it. And while the Zulu screen doesn’t include yields, the great man was no doubt a fan of companies that paid dividends. In The Zulu Principle, Slater wrote:
“I prefer companies to pay a dividend, as most institutions need an income stream from their investments. Also, the dividend payment and forecast (if any) to some extent corroborate the management’s confidence in the future. The ideal company will have a steadily increasing dividend growing broadly in line with earnings.”
It’s worth noting that dividends aren’t just a pointer to confident management; for investors they’re also an important component of long-term total returns. Work by Professors Elroy Dimson and Paul Marsh and Dr Mike Staunton at London Business School shows that while year-to-year stock market performance is driven by capital appreciation, long-run returns are dominated by reinvested dividends. They’ve found that in the UK, in the 115 years since 1900, an index fund with dividends reinvested would have grown to more than 170 times the value it would have attained without dividend reinvestment.
Tied together, the GARP plus yield emphasis of the Winning Growth & Income strategy has seen it do well in recent years with smaller-cap growth holdings like Zytronic, 32Red, Redde and Matchtech. But the same rules have also seen it holding larger companies like easyJet, J Sainsbury and a long term position in the housebuilder, Berkeley. All of them offered - and in some cases still offer - well above average yields.
Combining growth and income
So for investors tempted by the excitement of growth but conscious of the long-term compounding benefits of reinvested dividends, a combined growth and income strategy could be a useful place to start. As always, care is needed, particularly because when it comes to dividends. Very high yields can be a signal that the market no longer believes that the payout is sustainable. Plus, smaller companies can be susceptible to changing fortunes that might force dividends to be cut. But looking for signs of strengthening profitability, an improving outlook and below average valuations could help in the search for growth companies with an added dividend kick.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

16 comments
..
I may be wrong in saying this so can someone correct me if I'm wrong: but if your rebalancing quarterly you could be selling stocks that were meant to get in that desired level of divendeds? so you wont get that pay out as a stock needs to be held a certain amount of time to get the divended payout.... ?
Hi Vik.
If you look at the third paragraph above, it states that dividends (and dealing costs) are not taken into account in this and other guru screens. Any realised dividend receipts are an additional enhancement to the figures shown.
Gus.
I know the figures do not include dividends but I think the point is, if you sell at end of quarter then you could be missing a large dividend?
The other point is why are not dividends included in the figures this is an income screen? If you added dividends in then it would be about 30% higher?
Unpaid dividends accrue in a company's valuation before they're paid (they're cash on the balance sheet after all), so it doesn't matter if you actually are there on the ex date or not.
It does if you sell before the dividend is paid? Or are you saying the share price will go down by the same amount as the dividend?
Of course the price goes down by the amount of the dividend (on average net of noise), which reflects that the company assets are reduced by as much per share.
If it didn't, you could every day buy the highest yield you can find that pays a dividend in the next 24 hours, keep if for a day, repeat, and you'd literally end up owning the earth in no time through compounding.
By your arguement dividends are not worth having.
Sometimes the share price goes down more than the dividend, because for large dividends people wait and then all sell, sometimes hardly at all. But even if it goes down because of the dividend it usually recovers in the following days/weeks.
Yes exposure to actual dividend events is as such irrelevant economically.
On average the share price does not go down materially more than the dividend and "usually recovers": if it did you'd surely would have become a billionaire exploiting this effect.
One needs to look beyond the odd anecdote to be able to draw numerically accurate conclusions. Many people have done exactly that (it's a classic topic in academic research) and have not found the effect you propose (sadly, a free lunch would be nice).
As I said the high dividend payers often go down more than the dividend because there are lots of sellers. Thats why it can be a good time to buy, shares often recover after the initial selling is over.
Buying and selling of course there are costs, spread is often 1% or more, dealing costs and stamp duty, so no I don't think that would really work, also capital gains tax and dividend tax?
Ben, just run that screen and there are now 16 qualifying shares, are these added daily?
The first two shares in that screen are Telecom Egypt Co SAE and BLOM Bank SAL. These are both foreign shares listed on the International Order Book. Although technically a full LSE listing I don't believe that shares from the IOB should be included in a UK screen. This has been mentioned before. I would appreciate a method to exclude the IOB from all UK screens.
Yes I quite agree.
does stockopedia manually update the portfolio for this quarterly? if so what months are the stocks for this screen updated?
Seems to be updated daily, rebalanced quarterly.
Not sure the lower average holding period means people are chasing growth. Maybe they're chasing dividend and frantically rotating stocks to get the highest yield available each day...