Why high flying small company stocks could be worth a look this ISA season

The rise of the FTSE 100 has captured the financial headlines in 2017. But while many blue-chips have done well, that performance has been more than matched right through to the smallest end of the market. In fact there have been some stunning small-cap returns over the past year - especially on the Alternative Investment Market.
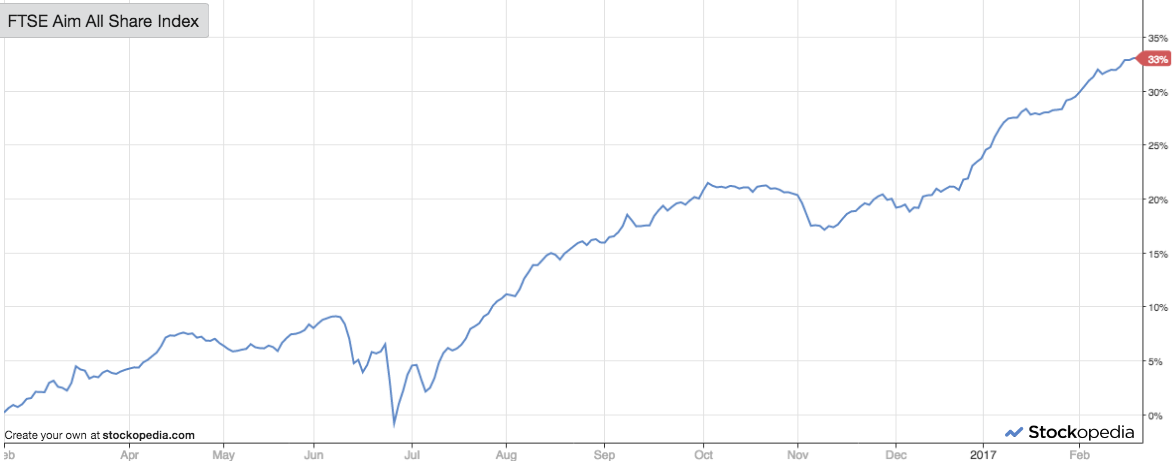
For onlookers, this surging pace could at first seem a bit disconcerting. After all, it’s human nature to look for a bargain. And with London’s junior stock index, the AIM All Share, rising by around 33% over the past year, there’s a sense that small company shares have very quickly got a lot more expensive.
So with markets in such a bullish mood in the run-up to ISA season, the conditions call for a strategy that doesn’t fear apparently high prices - as long they come with the best quality and momentum on offer.
On the hunt for high flyers
High quality companies with strong price momentum in their shares can be seen as the market’s High Flyers. You can find them in all indices and sectors. Often they’re the biggest and best known names in investing: think JD Sports, Domino’s Pizza, Hargreaves Lansdowne, Boohoo.Com and Fever-Tree. They tend to have really solid performance histories, making them the stocks that everyone would dearly like to own. Except they almost always seem expensive, which puts many of us off.
The academic and professional support for a high quality, high momentum approach to stocks is wide ranging. In many ways it forms the backbone of strategies used by influential investors like Richard Driehaus, William O’Neil and Mark Minervini.
In all cases, valuation is relegated from the stock selection process. As Driehaus explained: “One market paradigm that I take exception to is: Buy low and sell high. I believe that far more money is made buying high and selling at even higher prices.”
Minervini echoed that sentiment in his book, Trade Like a Stock Market Wizard, where he wrote: “Expose your portfolio to the best stocks the market has to offer and cut your losses quickly when you’re wrong.”
What do quality and momentum really look like?
To find companies with strong quality and momentum, there are some straightforward places to start. Generally a quality company is one that’s highly profitable with high industry leading margins, stable, growing and ideally accelerating sales and earnings. It will have a strong and improving financial track record and no signs of accountancy or bankruptcy risk.
In turn, strong momentum will show up in stocks trading at, or above, their 52 week highest prices and performing strongly against the rest of the market. They’ll often be beating broker estimates and seeing estimate upgrades and recommendation changes.
At Stockopedia we simplify all this by scoring and ranking every company in the market with a Quality Rank and a Momentum Rank - taking the above measures into account. To be a true High Flyer, these stocks would also have to rank fairly low against our third ranking factor, the Value Rank.
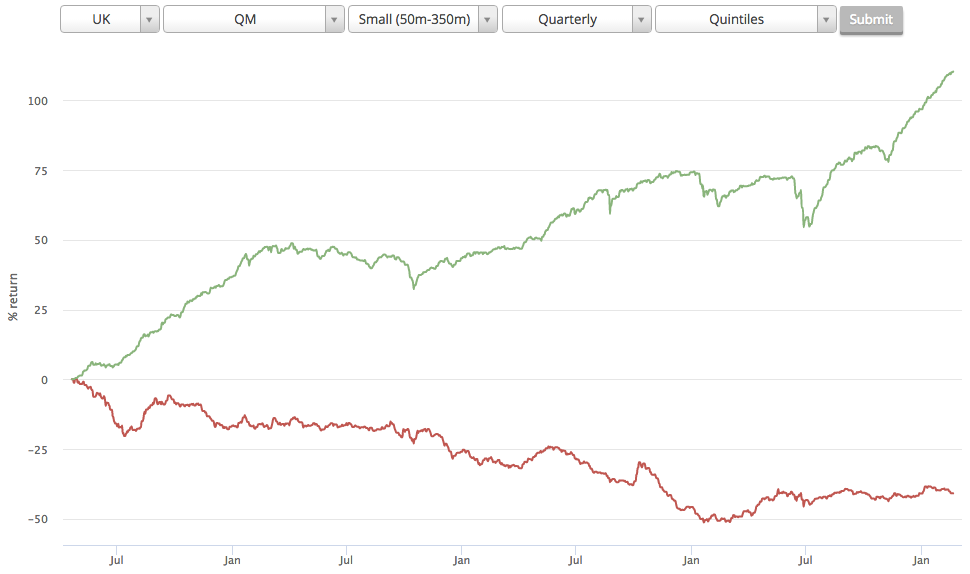
Interestingly, what we’ve seen over the past year is that small-cap shares (valued between £50m and £350m) with this kind of High Flyer profile have produced some impressive performances. The green line chart below shows the performance of the highest 20% Quality & Momentum stocks since we started tracking in April 2013. There has been a very strong acceleration over the past year. The lowest QM stocks have fared much worse.
Our regular High Flyer screen with a minimum market cap of £500m can be found here. But a variation on that, with a focus on small-cap shares, can be found here. Here’s a snapshot of that screen:
| Name | Mkt Cap £m | QM Rank | Value Rank | % Price Chg 1y | Sector | Exchange |
| Animalcare | 70.6 | 99 | 26 | +58.3 | Healthcare | AIM |
| Gamma Communications | 456.5 | 99 | 26 | +23.6 | Telecoms | AIM |
| Dialight | 329.9 | 98 | 18 | +131.9 | Industrials | LSE Main |
| Porvair | 233.8 | 98 | 21 | +74.9 | Industrials | LSE Main |
| YouGov | 273.8 | 98 | 10 | +95.9 | Consumer Cyclicals | AIM |
| ULS Technology | 66.1 | 98 | 30 | +87.2 | Technology | AIM |
| accesso Technology | 357.3 | 97 | 9 | +75.8 | Technology | AIM |
| ECO Animal Health | 334.9 | 97 | 13 | +64.0 | Healthcare | AIM |
| Craneware | 329.6 | 96 | 12 | +61.9 | Healthcare | AIM |
| dotDigital | 184.3 | 96 | 10 | +29.5 | Technology | AIM |
The companies on this list are not (or perhaps not yet) the sort of multi-year compounders that you see with much larger High Flyers. But it’s worth saying that some of the highest ranked larger High Flyers like ASOS, Boohoo.Com, Fevertree and even Domino’s (way back) were once much smaller AIM stocks that grew into big successes.
The big risk with High Flyers is that their momentum begins to breakdown. At that point they can become expensive-looking Falling Stars. And that’s arguably more of a risk with smaller shares, so this strategy does need care. Even so, in any market conditions (particularly bullish), it does offer a different way of thinking about expensive looking shares. They might seem pricey, but they’re often marked-up for good reasons. When those stocks have strong blends of quality and momentum they could have much further to go.
If you want to read more about High Flyers and other styles of investing, this is a good place to start.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
20 comments
Ben, your screen combines a high QM score with a low value score. Is the latter really necessary? Why not just high QM ranked by QM? It seems strange only to consider the dear options!
Hi Ben
Thank you for the article and sorry rather late to the party.
You mention your regular High Flyer screen and your small-cap variation and give links through to them. However, I was trying to see how I could find them, should I not have the links available. I have looked through all the Momentum, Growth and Quality Screens and cannot find a 'High Flyer' screen.
Does one actually exist or have you just recreated them for this article?
Hopefully I'm just being obtuse as I know High Flyer Screens have been mentioned previously and you can enlighten me as to where on your website I can access them
Many thanks
Santa
You can copy them over as a duplicate to form part of your own screens and modified the rules, that way you will always have them to hand.
Thank you Herbie for that suggestion. Very helpful
Santa
ok will try and follow the videos. One other devil's advocate point below. My last comment and I will try to hold my piece!!!
What is quality anyway?
The term is a misnomer. Many people define it (as is the case with Stockopedia) using backward looking financial metrics such as margins, track record, return on equity etc. These can help unearth quality companies but are backward looking in nature. You can have apparently good quality companies crash to earth i.e. Serco for example apparently had strong financial quality metrics.
Essentially what investors want are long-term "winners". This includes companies in good long-term sectors. It also includes winners in sectors that generate mixed results. If you look at any stock or sector that has done well over the long-term it is because it has a winning formula versus other sectors or companies. Financial quality metrics can be useful but they are not decisive.
If you look at Fevertree it has done well as it has a winning product within premium tonic water with significant growth potential. Quality metrics may even have been poor for Fevertree a few years back given that it was investing in marketing and growing the business.
Essentially investors need to find future "winners". Take the UK package holiday space for example and it is clear that Dart Group and On the Beach are winners in that segment. The hard part is identifying future winners where the long-term "winning" isn't priced in. Most of what drivers a future winner are qualitative factors. However, I accept that established winners will have strong financial quality metrics (i.e. Unilever, Reckitt Benckiser etc)
One of the characteristics of high quality companies is that they have a Moat, that allows them to produce high ROCE/ROA/ROE year after year. We can all find exceptions to the rule, but generally 'winners keep on winning' so in this respect historical out-performance is predictive of future performance. I would much rather back companies with good historical performance and a positive outlook (likely to create price Momentum) than those without. Ian
Well, if you believe the market is efficient, future "winners" are likely to richly priced and showing strong momentum ;)
Who says the market is immediately efficient - The whole point with +ve Momentum is that it is a market anomaly, which is an investor under reaction to good news. So Momentum winners can be both high PE Quality stocks which continue to out preform and/or improving historically low PE Value stocks that are re-rating. Both senarios are likely 'winners' and can continue to beat the market for 12 months or more. Ian
@ratioinvestor I don't really agree with your argument. All the companies you mentioned were flagged as high quality before the majority of their share price runs:
Of course there are stocks where you can find future growth, before the Quality metrics catch up, but that's normally flagged well before by improving earnings or price momentum.
There's nothing wrong with trying to anticipate the future, but I've learned that I'm much better at following the data than believing my own biases.
Haha. "probably best closing it down now before we all start writing academic papers."
Fair point.
gpacker - I have tried lots of things and searched for what I view to be an optimal approach. Yes different strategies can work. However, I am of the view that there is an optimal approach. I could follow a sub-optimal strategy and have a really hard time or I could follow an optimal strategy and make my life easier. If have looked at a number of sub-optimal approaches and for me they are mug's games.
That someone else is successful as a day trader, for example, doesn't negate the fact that for most people day trading will generate negative returns. My approach is that investment can be defined as a problem and in doing so an optimal solution can be sought. As is the Stockopedia mantra, it is all about increasing the probability and expected returns. Certain approaches do have relatively high chances of success and high expected returns.
This debate could go on for years!!!! Suffice to say some interesting points on all sides and probably best closing it down now before we all start writing academic papers.
Edward - I look forward to the next event that Stockopedia is at. I am guessing it is Master Investor or the Investor Show. May try and say hello but the stand is usually packed or a presentation is on.
Actually we're not doing any shows this season. The dates didn't work for us I'm afraid. We're going to be doing a lot more video this year to make up for it.
Ed
Yes please, more videos. I learn a great deal from them as you always illustrate a new aspect of Stockopedia that I had not yet discovered.
Regards
Howard
@ratioinvestor "The name of the game is to get quality at a good price"
Is it?
The name of the game is to get the best return on your investment isn't it.
As you alluded to momentum is also an indicator of a quality stock that is performing, sometimes ahead of forecast and sometimes lagging in nature.
I think we should move away from what is right or wrong, the market is full of different views, that's what makes the market interesting and challenging.
I remain open to all ideas and remain adaptable depending of market conditions/consensus.
Interesting reply. Whether someone is a buy and hold is all relative. I.e. how others view their typical holding period. I think it would be a stretch, though, to say that Buffett isn't a buy and hold investor.
I would also qualify my remark earlier that momentum is a "dirty" word for investors. It can be an indicator of a quality business rather than just investors getting over-excited. I.e. momentum could have enabled you to spot Unilever, Reckitt or Ryanair for example.
On the other points. I again would be a devil's advocate. The name of the game is to get quality at a good price. Also I think the modelling in a few replies back is very simplistic. The analogy I would draw is the economic modelling that economists use but which fails in the real world. Modelling typically has implicit assumptions that turn out to be wanting. It also ignores real world issues such as psychology.
I would compare the idea of just chucking out a stock at "fair value" and moving onto the next discounted value stock to market timing. In hindsight market timing is easy and there are certain rare extremes when the odds are favourable I.e. short the market or go long. However, generally it is very hard. It is the same for stocks in that they can stay at above "fair value" for a long time and compound away. At extremes it is obvious, such as Coca-Cola on a 66X P/E but these extremes occur infrequently.
The truth is that any investment approach can potentially work. However, the crux is what is the simplest and most robust approach. Just to take the real estate sector as an example. It is cyclical and highly leveraged and so therefore tends to destroy value. A company like Daejan has a commitment to low financial leverage and mature assets. My contention would be that Daejan will outperform the real estate sector over the long-term. I therefore buy and hold and do nothing. At some points Daejan will be highly valued and some points it will be cheap.
Switching in and out of stocks, though, appears simple but is generally a mug's game in the same way that market timing is a mug's game. The investors who have done well in the UK over long periods - Nick Train, Neil Woodford, Terry Smith - appreciate this truth. The exception are cyclical stocks where switching is key but these are hard to play as no two cycles are the same.
Hi ratioinvestor,
I am afraid I just don't agree with the idea that using momentum turns one into a trader and one is just trying to time the market by jumping ship first.
For me the most logical way to invest is to use data driven academic research and if there are many research papers suggesting a trait produces an average outperformance; I will use it in my investing method. Characteristics that have been brought together under the umbrella of “momentum” have historically produced significant outperformance, so I think should be included and can be included whilst still calling myself an “investor”. Whether it is intuitive to me (which it wasn’t for a long time) is irrelevant as long as the statistical basis is sound. To me now the psychological basis in people that causes the momentum mispricing is just as logical as the psychological basis for value mispricing, and in both cases it is this that the investor benefits from.
In my experience adding momentum to my investment process has not significantly increased my trading costs compared to when I was dealing with a more value & quality base. It has however certainly improved my returns which is, at the end of the day, why I do this.
In addition I think quality is a particularly useful filter in the small cap space, take the 2015 Cliff Asness paper: Size matters, if you Control your Junk. I think without a quality filter investing in small caps would be seriously scary!
Pete
Edward - That makes sense and it is an interesting parallel. However, unfortunately I am a bit of a devil's advocate on these things.
It depends if you are a value investor who chucks stuff out when it is "fair value" or deemed to be "fully priced." I don't really subscribe to that school of thought and prefer to look for stocks that will outperform over the long-term. I.e. Buffett didn't seek to trade Coca-Cola when it got expensive at the end of the century. Being the value investor who chucks out expensive stocks and then buys cheap value stocks is simple in theory. However, it is very hard to do consistently well in practice for a number of reasons. The practitioner evidence shows this very clearly.
So I am not a fan of momentum or the type of value investor who chucks out value stocks when they reach "full value." Although granted that Buffett did do this successfully with a number of stocks such as PetroChina.
Actually I'd counter that - he definitely did. Just not in the way you might expect. I have lost my source materials, but from memory he took out a massive hedge that swapped the returns from stocks for the returns from bonds. He may not like selling his underlying holdings but he certainly sold (at least some of) their returns for something preferable. At 66x earnings, Coke was clearly in bubble territory, he took advantage of it.
I think in this day and age of ultra-rapid creative destruction it's not wise to marry very many stocks forever. There are certainly some companies that have enduring moats, but they are harder and harder to identify. And there's a ream of CFAs who have been trained to think like Warren Buffett. It's a very different environment to the 1970s-1990s.
Great companies can be terrible stocks of course. Just as terrible companies can be great stocks (ask Benjamin Graham). Buffett himself made his first fortune taking deep drags from cigar butts.
PS - for more on Buffett's real trading habits (rather than the buy and hold myth) - have a read of Altucher's tome "Trade like Warren Buffett"
Just my view but I find "momentum" a terrible investment word. I have no doubt that momentum persists and that statistically it can be taken advantage of. However, it would mean lots of trading costs as you have to sell out when momentum reverses. It also often means buying stocks at elevated prices after strong rallies.
Momentum is a strategy that seeks to "make a turn" rather than assess the fundamental investment merits of a company. It really turns someone from an investor into a trader. The trouble is that you would get whip sawed in and out of good companies when momentum goes and then comes back.
Sure it will work for years in particular sectors such as the tech sector in the late 1990's. But it isn't really an "investment strategy". It is essentially a "follow the heard" strategy and hope you can be one of the first ones to jump ship when things start to go awry.
Adding a quality filter to momentum can obviously help but I am personally not reassured on statistical indicators of quality. They can help for larger companies with good track records but have mixed results in the fast paced arena of medium and small caps.
There's a Zen moment in investing when you learn that value and momentum are flip sides of the same coin.
There's polarity in everything in the universe, and there's a rhythm that exists between the extremes.
Stocks get undervalued, and they get overvalued.
Both types of investor are often at each other's throats as they don't understand each other. But there are many examples of billionaires who made their fortune from one or the other side of the coin. Both can co-exist quite peacefully... in fact they may have more in common than they realise.
Archetypal Value Investor mindset
Archetypal Momentum Investor Mindset