Why tech stocks are missing from the SIF Portfolio (AMO, OMG, TTG, PTEC)

Investors in technology stocks have done well over the last year. According to figures from the FT, the technology sector has risen by about 25% in that time. That’s more than double the 12% managed by the FTSE All-Share index, although it does lag the 31% gain delivered by the AIM market.
I’m mentioning this today because the SIF portfolio hasn’t really had much exposure to technology stocks over the last year. Although former holding XLMedia and current holding Taptica International are technology businesses, they are also marketing operations. Both are classified as Consumer Cyclicals rather than Technology companies.
Today I’m going to follow up on my piece from two weeks ago, where I looked at the portfolio’s sector allocation. I found that my stock-picking rules have left the portfolio overweight in sectors such as Industrials, which have outperformed over the last year.
At the same time, the portfolio’s exposure to underperforming sectors like Energy and Telecoms has been limited. This has helped the portfolio deliver a 1-year gain of 25%, versus 12% for its benchmark, the FTSE All-Share.
The strong performance of the Technology sector has left me wondering why my stock screen hasn’t highlighted any opportunities in this area over the last year. As far as I can tell, it’s mainly a question of valuation. Interestingly, four tech stocks qualify for the relaxed version of my screen, which looks at slightly more expensive stocks. So if recent falls continue, one or more of these stocks could soon qualify for the SIF Portfolio.
Amino Technologies
Television set-top box maker Amino Technologies will be familiar to readers of Paul Scott and Graham Neary’s excellent small cap reports. It’s an affordable looking business with strong cash generation and a decent record of growth.
I’ve previously been uncertain about the long-term outlook for this business, suggesting that the functionality provided by set-top boxes may soon migrate into the cloud or be built into televisions. So far my caution seems to have been misplaced.
In its recent interim results, Amino discussed the opportunities that are arising from its ability to update the software of legacy boxes. This means that cable network operators can upgrade their networks to new IP-based services without the cost and complexity of having to upgrade customers’ set-top boxes.
The shares have risen by 50% over the last year but still score well on Stockopedia, with a StockRank Style of Super Stock and a StockRank of 99. Amino also passes 13/14 of my screening rules, only falling short because of an earnings yield of 6.6%.
I estimate that a share price of about 155p would be required to lift the earnings yield to my threshold of 8%. That’s around 18% below the current price of 190p. That seems unlikely, but it’s not impossible. After all, the stock has already fallen 13% from May’s high of 220p.
Oxford Metrics
Software developer Oxford Metrics makes analytics and infrastructure management software for customers including highways authorities, Hollywood studios and hospitals. It seems like clever stuff to me. Better still is that this cleverness now appears to be generating rising profits and plenty of surplus cash.
The group’s share price has climbed 30% over the last three months, thanks mainly to a strong set of interim results. These showed record H1 revenue and net cash of £11.1m, double that of one year ago.
This company fails two of my screening rules, but only by a tiny margin:
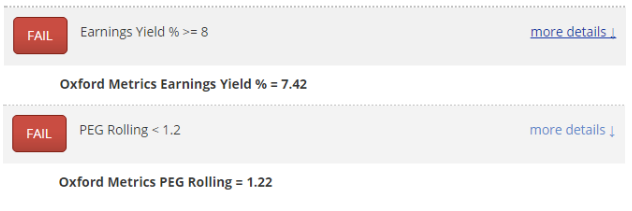
A slight pullback in the share price would be enough to clear these fails from the list. Given the shape of the share price chart, a period of consolidation seems possible or even likely to me:
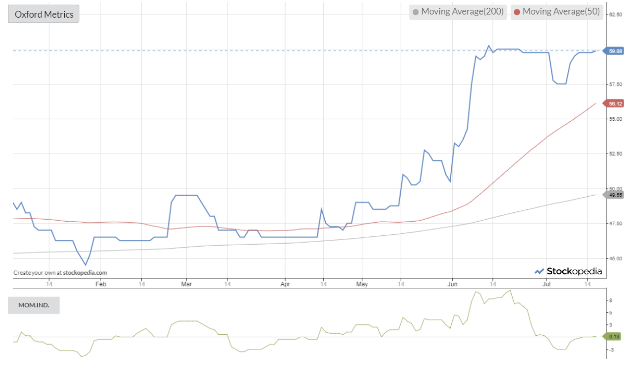
Oxford Metrics stock now trades on a forecast P/E of 26, falling to a P/E of 17 for 2018. It’s not cheap, but the group’s profits are backed by free cash flow and healthy margins. At first glance, I’d be happy to add this stock to the SIF portfolio if the opportunity arises.
TT Electronics
TT Electronics makes electronic sensors for automotive manufacturers and industrial markets. The group is obviously exposed to any future downturn in these sectors but trading appears to be strong at the moment.
In its most recent trading statement, TT said that the group’s order book was “strongly ahead of the prior year”, giving good revenue visibility. The company believes that its plan to focus on “structural growth markets where there is increasing electronic content” is paying off.
Revenue at constant exchange rates rose by 3% last year, while operating profit was 26% higher on the same basis. Statutory figures were given a strong boost by currency factors, but the underlying trend seems to be that profitability is improving.
Stockopedia styles the firm as a Super Stock and it carries a StockRank of 91. At the time of writing, the only thing stopping TT Electronics from qualifying for my SIF screen is an earnings yield of 7.7%, versus my threshold of 8%. It’s certainly a stock I’d be happy to consider adding to the portfolio.
Playtech
The last of my four tech stock candidates is rather larger than the others. FTSE 250 group Playtech has a market cap of £3bn and specialises in gaming software. It provides services to operators including William Hill, Betfair and Sky.
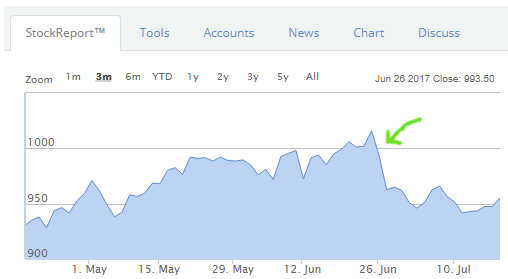
The firm’s founder, Teddy Sagi, recently sold 10% of his 17% stake in the firm to finance a move into real estate. This knocked the share price in June:
The resulting sell off has left Playtech trading very close to the valuation needed for it to qualify for my screen:
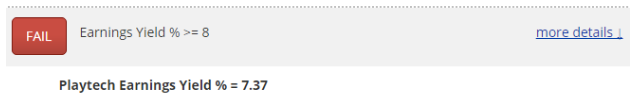
Playtech passes all my other screening rules and looks reasonably valued, on a rolling forecast P/E of 12.2 and a yield of 3.6%. However, even if it qualifies for my screen, this stock would rank below the others I’ve looked at this week due to its StockRank of 73. Although a respectable score, the other three all have ranks of more than 90, suggesting a higher probability of outperformance.
Coming next week
All four of these stocks have experienced some share price weakness recently. If this continues, there’s a good chance at least one of them will make its way into the SIF Portfolio.
The portfolio’s shortage of cash has prevented any additions in recent weeks. However, this should be rectified next week when McColl’s Retail, Miton Group and Wincanton are all due for review. Selling one or more of these holdings should free up some cash for fresh opportunities.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

12 comments
PTEC (Playtech) has been at this level seven times since Sept 2013.
Three times 760p or so provided Support, twice it acted as Resistance.
Once it broke above only to fall back after a few sessions and in 2015 it powered through on an impressive continuous rise from 615p in November 2014 to 943p in July.
Stockopedia never gave it Value above 50 at the 760p level, however VectorVest gives it good RelativeValue for the sector.
Nebulous legality in some jurisdictions may give it a discount.
Discussions on the founder's sale and the ethics of the business can be endless.
However the Risk/Reward looks interesting and I have taken an opening position.
Gus re Playtech (LON:PTEC) you may have missed today’s FT markets live;
https://ftalphaville.ft.com/marketslive/2017-11-02/
In my view it is totally uninvesteable as it stands..but you may be braver
Hi rhomboid1.
Thanks for the heads up on the FT discussion. I hadn't seen it. Makes interesting if slightly fractured reading.
My take is that Playtech (LON:PTEC) sails (very) close to the regulatory wind by operating in mainland China via offshore entities. In the past it's been very profitable but the law enforcement net seems to be tightening although the company is none too transparent in spelling this out. Possibly one to take a short term spread bet on rather than a long term buy and hold. Then again, the dog may just have too many fleas on it ....
Thanks again.
Gus.
Hi Roland.
At risk of reaching for a falling knife, I wondered if you had looked at Playtech (LON:PTEC) recently? They came out with a profit warning this morning (5% below bottom end of market expectations) attributable to lack lustre performance in Asia. Not sure if this is readily fixable or more of a systemic problem.
https://www.stockopedia.com/share-prices/playtech-LON:PTEC/news/playtech-plc-trading-update-urn:newsml:reuters.com:20171102:nRSB3626Va/
Either way, shares are down more than 20% at the moment - a huge drop for a FTSE 250 company - which should bring the earnings yield well within your target range. All the rest of your screen tests appear to be passed although not sure if this will still be the case when the algos work through the profit warning. No position at the moment but thinking about it. Any views?
Gus.
Hi Roland
Ive been looking at OMG for last few weeks and taken the plunge and gone long..
It operates in two business segments:
Vicon Group, which is engaged in the development, production and sale of computer software and equipment for engineering, entertainment and life science markets;
Yotta Group, which is engaged in providing services for the management of infrastructure and taxation, highway surveying and software development.
Discretionary clients of Hargreave Hale Ltd more than doubled their stakes in the business earlier this month.
If OMG continue to deliver, with positive updates the shares have a lot higher from here to go. I think we will get a break out. Using technical indicators the tenkan line is still hovering above the kijun sen. This represents bullish momentum for the shares. Whether or not the shares are ready to break out further is yet to be seen. I think they will stay around the 58-64p mark before the next break out.
Im long.
Rowland, yes agreed - Its about finding investing methods that suit your particular personality. Mine is to take away the stock picking by numerical screening and then with the shortlist checklist/follow news/introduce bias from there! I have tried both ways and am much better at the latter! Ian
Rowland,
Some interesting companies among your prospective list. Rather than use absolute screening criteria I have moved to a 40+ point checklist (quantitative mainly). The metrics that pass are in black and the ones that fail are in red to build up a numerical picture of a particular company. Companies don't have too (nor ever do) pass all the listed criteria, but in general the more they pass the more interested I become. Then I write myself a paragraph of it's key quantitative and subjective attributes and decide whether to buy.
As an example I did this in mid June before buying Oxford Metrics (LON:OMG) and my written summary at the time is below:
Restructured business with new 5 year 2x profit strategy. Momentum, Quality and reasonable Value (96 Q and 86 QM with 86 SR). LFL sales +15% with increasing SaaS%. 52 Week High after 6/6 interim results. Very low Beta and Volatility. Decent Divi and catchy ticker that institutions will like. PER multiple should be 25?
Since running my screens and the additional checklist + summary my investing has improved dramatically. So my suggestion is not to be be put off by a minor screening rule fail and to look more at the totality of the business.
Hi iwright7,
Thanks for highlighting this approach to investing. I agree that using a points-based scoring approach to create a ranking list of potential buys can work well. It's not the approach I'm currently using, but does have some attractions and I'm aware that a number of successful investors follow this method.
I think there's a slight risk that this approach might result in too much subjectivity in stock selections, but with good discipline this shouldn't be a problem.
I guess another advantage of this method is that it allows you to scratch the itch of active investing (!) while maintaining a systematic approach to buying stocks.
Regards,
Roland
Hi Roland. I enjoy your articles which improve my knowledge and technique in researching suitable investment opportunities. You refer to 14 qualifying criteria which each potential candidate should meet or exceed in order to qualify and I am wondering if you would be prepared to share your insightful knowledge? I am in the middle of reading Michael Minervini's book which refers to using tick lists and I know Warren Buffet and Charlie Munger also use this simple process which helps to shortlist potential investments. I also subscribe to Research Tree which provides detailed fundamental analysis; this provides an overview but care must be taken where the broker also acts as the sponsor for the company and bias can creep into the research.
Hi Abingdoninvestor,
Thanks for your comments. My 14 criteria are the ones in the Stockopedia screen which I use to generate a short list of stocks to consider including in the portfolio.
You can see the current screen results and the screening rules here:
http://www.stockopedia.com/screens/stock-in-focus-screen-113218/
Regards,
Roland
Thanks Roland. I gathered that your SIF list was the one you use to highlight qualifying stocks after I had requested information.
Update and info much appreciated Roland - Thank you.