Boohoo (BOO) Trading Update - Q1 (3 months to 31 May 2021) - discussion

Good morning, it's Paul here with a separate article to discuss the Boohoo (LON:BOO) (I hold) trading update for Q1. We keep it separate from the SCVR now, because BOO is a mid cap, and is widely held/discussed by readers, so it tends to overwhelm the SCVRs.
PR title -
Building for growth and a sustainable future
Key data -

.
My views -
- Overall 32% revenue growth is excellent, and well ahead of previous guidance of +25%
- Core UK market performed exceptionally well, at +50% - this must include the start of the new brands recently acquired, so not all organic (the split is not given)
- Rest of Europe revenues down -14%, which is a bit surprising. The pandemic is blamed, but I wonder if problems with dispatching & returns from the UK to Europe (re Brexit) could also be a factor? Rest of Europe is only 11.3% of total sales now. This should recover in time (e.g. setting up a warehouse in Holland might be a good idea, which some UK companies are doing apparently)
- Key export market is the USA, which performed very strongly at +43%. This was 27% of total revenues in Q1. I wonder if BOO shares might attract some interest from USA investors at some stage? Growth companies get much higher ratings in American markets.
- Note that constant currency "CER" shows that sterling's strength against the dollar has helped boost sterling reported revenues in the USA, and worsened revenues as reported in sterling in Rest of Europe, and Rest of World.
.
Gross margin - slightly down at 55.0% - still very respectable, and much higher than Asos (LON:ASC) (I hold) for example.
Net cash - of £199.1m, reduced due to heavy capex, including purchase of freehold office in Soho. Not an issue, the position looks fine to me.
ESG - publication today of latest report from Sir Brian Leveson. I'll read that later, thankfully it's only 13 pages!. The group is making "excellent progress" according to the trading update today. Personally I think this issue is waning now - BOO admitted there were serious shortcomings in its supply chain, and couldn't be doing more to rectify it. The latest issue in the press is use of plastics in man-made fabrics such as polyester. BOO is moving to recycled materials, so they're on the case there too.
Guidance - remains the same -
The Group has made a strong start to its financial year against challenging comparatives, and in line with expectations uncertainty remains in a number of markets that the Group operates in around the world as a result of the pandemic.
Guidance for the year ending 28 February 2022 therefore remains unchanged, with revenue growth of around 25% and adjusted EBITDA margins expected to be in the region of 9.5-10%.
Our medium-term guidance for 25% sales growth per annum and a 10% adjusted EBITDA margin remains unchanged, reflecting the board's confidence in the Group's prospects as it continues to invest in building for the future.
Broker Update - Zeus has kindly made available an update note this morning, available on Research Tree.
It is forecasting 11.81p diluted adj EPS this year, and 15.31p next year. PERs of 27.9 and 21.6 respectively. That strikes me as far too cheap for a rapidly expanding, highly profitable group.
My view - it seems to me that, having comfortably beaten guidance in Q1 (32% actual vs 25% guidance), then as the saying goes, risk is probably more to the upside. Therefore I imagine we're likely to see upward moves in guidance as the year progresses, which is the typical pattern we've seen in the past.
Directorspeak - management are rightly pleased with this performance, since it comes up against tough comparatives from lockdown 1 last year -
"I am delighted with our performance in the first quarter, particularly as it was always going to be challenging to produce strong growth rates on last year, when lockdowns around the globe drove such high traffic to online retailers. The two year CAGR of 38% highlights the Group's continued phenomenal growth, with revenues having increased 91% over the last two years, with particularly strong performance in key markets such as the UK and US, where sales have more than doubled.
My opinion - I'm really happy with this. That BOO has beaten guidance, with +32% revenues growth, despite setbacks in Europe & RoW, and tough comps, is mightily impressive.
For me, this is the ultimate coffee can (i.e. hold forever) share. It's going to be a very much larger business in a few years' time, and everything else is just background noise to me.
For balance, I should mention potential negatives -
- ESG - not out of the woods yet, although this is clearly a concern mainly for journalists, and investors with an ESG mandate for their funds. It's obvious from the performance statistics, that BOO's customers have not been put off by ESG issues.
- Online sales tax - now widely expected, so possibly already in the price? Although when announced, I am expecting a short term blip in price, so am keeping some powder dry to buy more. All taxes are passed on to end customers, so it really shouldn't make much difference.
- Windfall tax? - if it moves, they'll try to tax it! The latest wheeze emanating from the Treasury is apparently to punish companies which did well over the pandemic. This could hit online retailers. My view is that providing any taxpayer support is repaid in full, then they should be left alone.
- There was talk of a campaigner against slave labour trying to get BOO banned from the USA. Nothing seems to have come of that, and it's not mentioned in today's update.
What are your thoughts? Let's discuss in the comments below.
There's a conference call for analysts & investors at 09:00 today. Details here:
UK Toll Number: | +44 333 300 0804 |
UK Toll-Free Number: | 0800 358 9473 |
Participant pin code: | 36301957# |
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
54 comments
Its surprising the small numbers that can leverage social media into bigger headlines. Activists tend to be more 'active' unsurprisingly. Then the wider media feed on it, and away we go.
Another have a go at Boohoo (LON:BOO) article in the Ecotextile News:
https://www.ecotextile.com/202...
I don't subscribe but the intro reads:
"Workers' rights campaigners are raising concerns over the progress of fast fashion company Boohoo in addressing labour rights abuses in its UK supply chain.
On the day of the fashion brand’s AGM, three groups - Business & Human Rights Resource Centre, Labour Behind the Label and ShareAction - say they are not convinced by Boohoo's actions so far.
Boohoo launched its Agenda for Change programme, under retired judge Sir Brian Leveson, after it emerged that some of its suppliers in Leicester paid workers less than half of the minimum wage and failed to implement COVID safety measures."
I suspect these groups will only be happy when every capitalist wealth and job producing company ceases to exist but it still makes share price progression of my second largest holding (12.29% of portfolio) more difficult.
It will add to the wall of information discouraging institutions from investing in Boohoo and therefore creates a real head wind.
Will continue to hold but I suspect that I will reduce as it is creating a real drag on the portfolio.
Regards
Michael
I agree however I believe only Burtons/ DP etc were seen in the numbers above. There was minimal contribution from Deb. They refer to the phase the acquisitions are going through as a 'soft launch' where the marketing taps haven't been turned on yet.
The metrics from row and Europe are worrying. Management are putting this down to buyer fatigue which is reasonable enough however I'd wager shein have gained substantial ground on boo in both those markets so the question is was there an error in marketing, warehousing, product strategy or perhaps just price? Management should be able to address these issues and with FWD pe in the early twenties risk reward is more favourable than most out there. It's a watchful hold from me.
Good to see Director top up today….
Director's Dealing
boohoo (AIM: BOO), a leading online fashion group, announces that Iain McDonald, Non-Executive Director, purchased 56,000* ordinary shares of 1 pence each in the Company ("Ordinary Shares") at a price of 326.37 pence per ordinary share on 15 June 2021 and 44,000* ordinary shares at a price of 326.59 pence per ordinary share on 16 June 2021.
I think there is a good news story for Boohoo (LON:BOO) on ESG….when they are ready to promote it. At present they are still bleeding out the negatives, under regular attack from ‘activists’ of various stripes who are working hard to regularly paint the worst picture, eg the current attempt to get Carol Kane removed from the Board - it won’t happened but it gives all concerned another opportunity to rehash negative news from 2020.
As for growth, well I think that for February to May, with almost all of their markets under Covid lockdowns to some degree, but in many areas physical shops open, these are superb results. Frankly the novelty factor for shops in April was clear to see with queues of young people waiting to get into clothes shops. So if Boohoo (LON:BOO) is till able to bring in over 30% growth, with the pressures of:
* Agenda for Change ESG programme and seeing through its business implications
* Integrating new acquisitions
* Developing new acquisitions
* Taking on whole new lines of business (eg beauty, children’s clothes and home)
* Covid Worldwide logistics issues
* Impact of Covid on clothing demand due to restrictions on social occasions and travel
* Rubbish weather in May, which normally dampens (pun intended) clothing demand
I see that as very creditable performance. When looking at these pressures, it is easy to see how the 2nd half of the year may see higher growth rates.
The new acquisitions are not a big feature yet. Eg for anyone who has followed the development of the Debenhams website will know that, it’s only started around late April/early May, it has been very much in development phase (still is) and there has been no marketing for the Debenhams. Boo take the (re)development of their acquisitions very seriously and indeed cautiously, and expect to build them up over time. If sales are already over target that’s encouraging as really the whole Debenhams story is only just beginning.
Boohoo (LON:BOO) (no position)
Without breaking out organic/inorganic growth I'm not sure today's update really told us anything other than growth looks to be slowing, which seems strange given how many acquisitions have been made recently.
In any case, here are the Year-on-Year growth rates for any interested.
I didn't notice it until now, but the growth rate was actually at its peak just before covid started (+47% in Jan-Feb/"P11-P12" 2020).
Cheers
A
Not surprising, I think many customers buy clothes for nights out on the town or parties, in lockdown then they won’t be going out. There maybe some return to growth when venues such as nightclubs reopen.
I’m not convinced that some of the acquisitions were a good deal for Boohoo (LON:BOO).
As well as the remnants of the ESG issue, this appears to be the other big issue for Boohoo (LON:BOO) - in my view their acquisitions these last 18 months have been fantastic…but they only show their true value after 1-2 years development. I will be very interested to see how Debenhams looks after it has had two Christmas periods. Until then I guess it’s a matter of faith either way…though even the most sceptical must agree that Boo have been virtually acquiring companies from their petty cash (albeit they do then put significant capital investment in).
Shock Horror Boohoo (LON:BOO) to open up a bricks and mortar shop (only the one mind)
https://www.telegraph.co.uk/bu...
For those who cannot access the full article, "Leading cosmetics brands typically demand that retailers have a presence on the high street before striking partnerships - a stumbling block for companies such as Boohoo, which only sells online."
Asked my 23 year old son if he ever purchased from Boohoo as I only ever see ASOS bags arrive. His reply was “not anymore as they use slave labour. I through away all my boohoo stuff”. Although investors are aware of the amends the company is making it appears their target audience are not.
I have never ordered from Boohoo (LON:BOO) but have just placed my first ASOS (LON:ASC) order. The prices were good, 4 polo shirts for £22 inc. postage. Not keen on the £4 postage but returns are free. Delivery takes about a week and they use Hermes which is not everyone's favourite. Will see what the quality is like. If you are going to order several times a year you can get the annual postage for £10 which does not seem a bad deal.
Where do ASOS (LON:ASC) source their clothes?
Asos (LON:ASC) have souring Factories listed on the Corporate Responsibility Site (under supply chain): https://www.asosplc.com/corpor...
ASOS (LON:ASC) It all sounds very good but it's easy to find reports that claim things are different and that is in the UK, who knows what goes on in China and some other countries. Seems a majority of their clothes are from China and the Indian sub-continent.
I hold and read all of the info and opinions with interest.
Does anyone think that if Boohoo (LON:BOO) started to pay a dividend at some point that might change the view of the market on them at all?
Surely it's easier to sit out of a stock if you are 'only' speculating on the share price rising and you selling ta a later date, but if it's consistently returning a high income yield to its shareholders it would be much harder to ignore?
I'm not saying in any way they should do this as they're finding better things to do with the cash right now but would value thoughts on it longer term.
Personally it'd probably detract from my opinion of Boohoo (LON:BOO) if they started paying a dividend.
I'd take it as an indicator that they're running out of places to allocate the capital effectively.
The flipside would be that, I'd rather them be honest about not being able to allocate incremental capital at the historical rates of return and pay it out as dividends, than to allocate it in sub-par projects etc. and dilute the existing ROCE.
The appeal of Boohoo (LON:BOO) for me is that there is a large runway for continued growth hopefully at the same (or better) ROCE.
"In the short term the market is a voting machine. In the long term it is a weighing machine" or something like that. John Maynard Keynes (I think). When will the weighing start to take over from the voting? When it does, BOO could easily double.
Ben Graham but I agree very apposite in the case of £BOO. I am fairly certain the weighing will take over from the voting at some point but will it be before a. my patience runs out and b. after I have missed oppotunities in other companies?
There is an interesting article in Bloomberg today on the super fast growth of Chinese fashion brand Shein. According to Bloomberg Shein's revenue tripled last year with clothes prices so cheap that they make even Boohoo look expensive. Their app is now the most frequently downloaded retail app. The Bloomberg article is based on information from the US market.
I had a look at Trustpilot (the UK site) this morning. Reviews of Shein are distinctly iffy. Mixed in with appreciative comments are lots of complaints about:
1. deliveries that don't arrive
2. customer service problems - customers waiting fo refunds that also don't arrive
3. poor quality garments that don't resemble the pictures on the website
The US Trustpilot site has a similar range of reviews to the UK site. So, based on these Trustpilot reviews, hardly a competitor to Boohoo. Does anyone know any more. A competitor with equivalent quality but cheaper prices could easily affect Boohoo's prospects. A competitor whose clothes don't arrive or don't please is going to be little more than a temporary blip.
Probably the most interesting comparison for boohoo would be with US listed company Revolve.
https://investors.revolve.com/overview/default.aspx
I'm just travelling on the London underground and have noticed a number of Shein adverts now you've mentioned it - though £boo still outnumber. One to keep an eye on.
I compared boohoo's trust pilot reviews to shein's a while back and didn't see any tangible difference.
I'd argue that it is a major competitor that can do things cheaper than boohoo and react to trends just as quick.
Interesting that it seems fine by the woke community (i.e. I have not read of a campaign to persuade people to the contrary) to buy clothes from a company (Shein) based in the most human rites abusing country in the world that executes an estimated 2,500 people a year but fine to stick it to a company (Boohoo (LON:BOO)) that employs 100's (1,000's?) in the UK generates income, taxes and wealth for the UK and is taking seriously the need to clean up the rag trade.
We live in strange times.
I've held Boohoo for a long time now and i've done so knowing that a re-rating of the share price will not happen in the short term. I've talked about this before but ESG considerations and cancel culture is only getting stronger. And its very sticky. When i made my choice to buy, i weighed up the possibility that Boo could make a ton of progress, but trade sideways for a significant period, with ESG concerns being the main driver of a supressed SP.
What I would like to see is them draw more attention to the work they're doing to address the ESG concerns. if you ask someone walking down the highstreet about Boos problems, they could probably tell you about the 'leicester workers slavery' story plastered all over the news. I highly doubt any regular member of the public knows about any remedial actions being taken.
I reckon they should pump some of that cash in to the Instagram / TikTok influencers and get them to talk about it at a very basic level whilst advertising the latest offerings.
I hear what you are saying, however, look at this guardian report - which of all the media would highlight cancel culture, it comes across as very fair and clearly states the praise given by Leveson:
https://www.theguardian.com/business/2021/jun/15/boohoo-sales-debenhams-website-covid-online
In fact if Boohoo were truly clever they could highlight the fact that they are prepared to listen, take ESG concern seriously and compare and contrast with rivals - what for example are Zalando, ASSOS etc doing to address labour issues. They turn a perceived weakness into a strength.
Asos (LON:ASC) are very progressive in terms of ESG. Their strapline is "Fashion with Integrity: epitomises our approach to business". They were founding members of the Fast Forward initiative, which Boohoo (LON:BOO) has now joined: https://www.fastforwarduk.org/ that looks to ensure supply chain is ethical
I am on the investor call - but can someone put the recording up on the web pls.
They continue to do very well but the market has been applying a harsh P/E compression over the last few years possibly due to the negatives on Paul's list being more of a structural shift and part of millennial's growing activism against fast fashion. Many big YT influencers are talking about recycled clothes, and clothes that last a long time (one of which Boohoo are addressing, and the other is not in line with their business model).
In the end I sold out of my position as the opportunity cost is too great for my capital allocation against global growth stocks. I continue to keep an eye on it as a great British business and wish all holders the best of luck.
Hi shamusj, on the subject of fast fashion being out of fashion, there was a news story on a report about how about half of Boohoo's clothes were made from plastic, mentioning Prettylittlething, Missguided and Asos too, which wouldn't have been a news story at all until recently. They mentioned Boohoo's Up Front strategy "which sets an "ambitious" goal of all polyester and cotton being recycled or more sustainable for 2025" but also that they had a "mountain to climb" to meet this target. However, Boohoo said that their customers use charity shops and resale sites, and that throwing away clothes was a last resort (I certainly see Vinted featuring highly in the shopping habits of my sample group of one teenager). They didn't mention the microplastics angle at all. Mind you, my memory says that cotton isn't always seen as environmentally great with the insecticide and bleach angle, but maybe I'm out of date there. I guess reduce-reuse-recycle is the safest angle to be in with the influencers.
Hi Indie - Re Fast Fashion and Plastic v Cotton. There is also the ESG Issue with some cotton producing areas, for example - https://www.bbc.co.uk/news/wor...
It doesn’t make sense to me they can export into the US seemingly without issues but exporting into Europe is a problem.
EU doesn't have a trade deal with USA, so pre and post Brexit trading arrangements remain the same?
We fought tooth and nail for a deal with the EU with the fear we may end up on WTO. We trade with the US on WTO and that seems the smoother option.
Punitive actions by the EU.
There are no "punitive" actions by the EU. What we have is a transition from Britain from being in the SM/CU to an external deal. Something that was entirely the UK's choice (or at least parts of it). It's not hard to see why US trading has been smoother over the past 6 months - it's continued under exactly the same regulations as previously. Everyone is set up and used to it. Unlike current trade with the EU, where there was little real help or clarity from the govt before Jan, and there's a big learning process going on, and dealing with new costs.
Perhaps the difference is that there is a long established trading mechanism for exporting to the USA that everyone knows and understands but there isn't anything similar set up for exporting to the EU. The English Government seems to have left it to individual companies to find their own way.
WTO terms you mean?
There is no English government. I think that gives us an idea of your grasp and knowledge on the subject :)
(Non woke alert). I did a quick trawl of the Boohoo (LON:BOO) website. I think the issue with the lack of sales growth into Europe might be down to them not having the appropriate stock for the European market.
Gus.
I can just see this on the front cover of the Daily Mail with the headline of "Late nigh revellers letting their hair down"
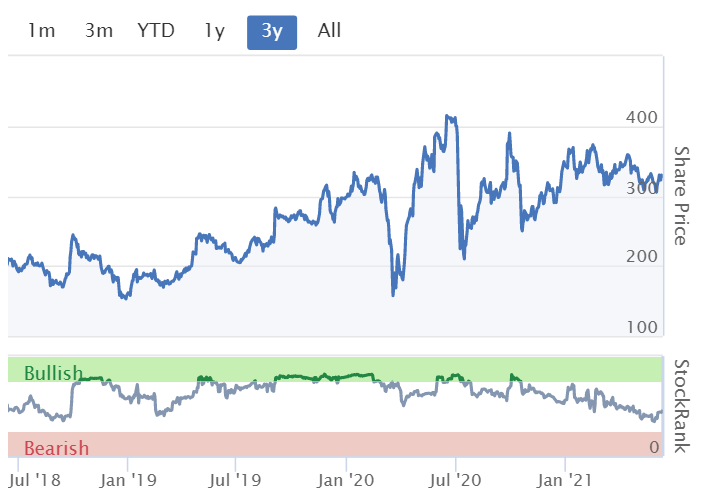
Any Boohoo (LON:BOO) Chartists care to give a view, I'm a future long term holder since the initial ESG blips so and keenly watching for progress on ESG and how the platform grows, I'm also wondering if BOO looks like a cheap UK company as many are being looked at now that Brexit is largely done and the covid impact is understood
Hi ihalliwell,
I've been waiting patiently on BOO for some time. Like many on here, I'm already a holder.
Technically, its still looking constructive. I think most people are aware of the long term flag, which I think is best viewed on the weekly.
The lower trendline of the flag has been holding, and you can see that volume has been steadily 'tightening up' since July - I like this. As they say "from contraction comes expansion". If we can see a move up, and a break out of the flag on volume, we could be off to the races, although a re-test after the breakout would not be unusual.
Recent price action also has a double-bottom structure to it, another potentially positive sign.
I'd be looking at a break of 365p to have higher confidence that a sustained move up is starting.
I think Boohoo (LON:BOO) has "trodden water" for long enough, above 25% growth for this Qrt against last years growth during the same period is concrete evidence of continued growth even with covid and brexit, I actually expect £boo to re rate , starting today, its well overdue for me.
I think what it really needs is a breakout thru 380 (extra confirm in case of false break) but in a lot better volume than seen of late. As you rightly say it's been going sideways now for about 9 months and seems to lack institutional fervour, but is a darling of retail traders for whatever reason. So am very much on the fence here......particularly as perceived favourable numbers seem to have little impact.
Agree, lack of volume indicates institutions are shunning it imo. I personally think it’s down to two factors:
1. ESG concerns.
2. There was a big capital raise at 340p last April (2020) - those investors are still in a loss and had the massive shock of the drop to c230p last summer. Therefore, I suspect that there is a lot of supply coming to the market at around 340p so this could move sideways for a long time yet.
A clear break through 360/380 on significant volume is required but the longer this sideways move happens the more likely it is to break to the upside on positive news in time, but only when this supply has stopped coming to the market.
Anything negative and it’s going to get hammered.
This is my largest position by far and I’m not at all comfortable with the price action to be honest.
Three comments from me:
(I hold)
I just want to add one further comment to what I said earlier. Reflecting on it, +50% growth in UK is astonishing at this stage in the business - even if we allow for the fact that a fair proportion might be new brands. This is a really well performing business in the UK. The Europe result does make me nervous as it might limit some of the potential upside longer-term but the UK/US growth is looking really encouraging.
We tend to value organic over acquisition led growth because:
1. acquisitions tend to be expensive
2. the additional revenue that was already in the acquired business is not really growth
Neither of these apply here:
1. BOO bought most of these brands out of the money they keep in the the biscuit box
2. Given that the newly acquired brands used to be primarily store based, much if not most of the revenue from these brands is new
In other words, pretty much all of the growth (including that from acquired brands) is real
On the conference call, the CFO mentioned that the prior year comps for Europe were particularly harsh, as last year saw a big surge on lockdown 1. He sees a "big opportunity" in Europe, when re-opening happens. Also mentioned that there are not many reasons to be buying going out clothes in Europe at the moment, and there are signs that customers "are tired of lockdown clothes".
Shortly after that I got cut-off, so missed the rest of the conf call. It was about 8 minutes of the CEO reading out the RNS. Then Q&A from analysts, so not much of interest in it really.
I am a massive boo fan but personally I think the 50% UK growth is disappointing given previous trend growth.
If we assume that Debenhams, Dorothy Perkins, Wallis and Burton are 100% UK brands then;-
1) When it acquired Debenhams boo said that existing annual online revenue was £400m
2) Annual online revenue for DP, Wallis and Burton weren't disclosed when acquired but must be significant, say at least £100m? (boo paid £55m for £400m of Debenhams revenue and it paid £25m for the Arcadia brands)
How much of that approx £500m of acquired UK annual online revenue would have found its way into today's Q1 UK numbers?
Personally I think UK organic growth in today's numbers will have been flat or down. But that's just an opinion for what it's worth and I still like the long term outlook and I am super-impressed with the 40% US growth.....
There is a blogger on twitter that just suggested the same, that UK organic growth could be negative this quarter.
It is strange that they didn't break organic v inorganic out. Did anyone ask on the call?
yes, they said the new brands were delivering above their 5% target that they aim for when integrating new brands but they weren't going into the details because the details are fluctuating week on week at the moment - but above.
they said they were pleased that so much of the growth was still coming from the original brands, which analysts might not have expected.
they haven't turned on the marketing spend on debenhams.com yet, but would be soon
recent weeks have seen a massive upturn on dresses with sales of dresses above pre-pandemic levels
I am not going to comment on your summary Paul - apart from it is as excellent as per usual, however from a technical point of view - the share price has tightened up, showing a flag shape - does this suggest a potential large movement of the share price - especially as Boohoo appears to be moving in the right direction?
An excellent write up and an excellent performance from the company. Keeping guidance at 25% revenue growth for the year having delivered 32% revenue growth in Q1 looks particularly conservative and will likely lead to upwards revisions as we go through the year.
They are clearly doing really well in USA where British retailers have generally done poorly and it has always been said that they do not understand US market (M and S etc). The potential for future growth here must be considerable