Didn't buy Serabi Gold? Why clear uptrends are the best uptrends and 20 stocks to consider now

Have you ever watched a share rise and rise - and never had the courage to buy it? I do and regret it all the time. The numbers often look good, brokers are upgrading forecasts, but the price keeps grinding higher and gets away from you. You wait for a pullback but it never comes. A year later and it's doubled again!
This annual series is my attempt to fix that mistake. It rests on a counterintuitive idea - that the shares with the clearest, strongest price trends tend to continue to outperform. But these are the ones our instincts tell us to avoid.
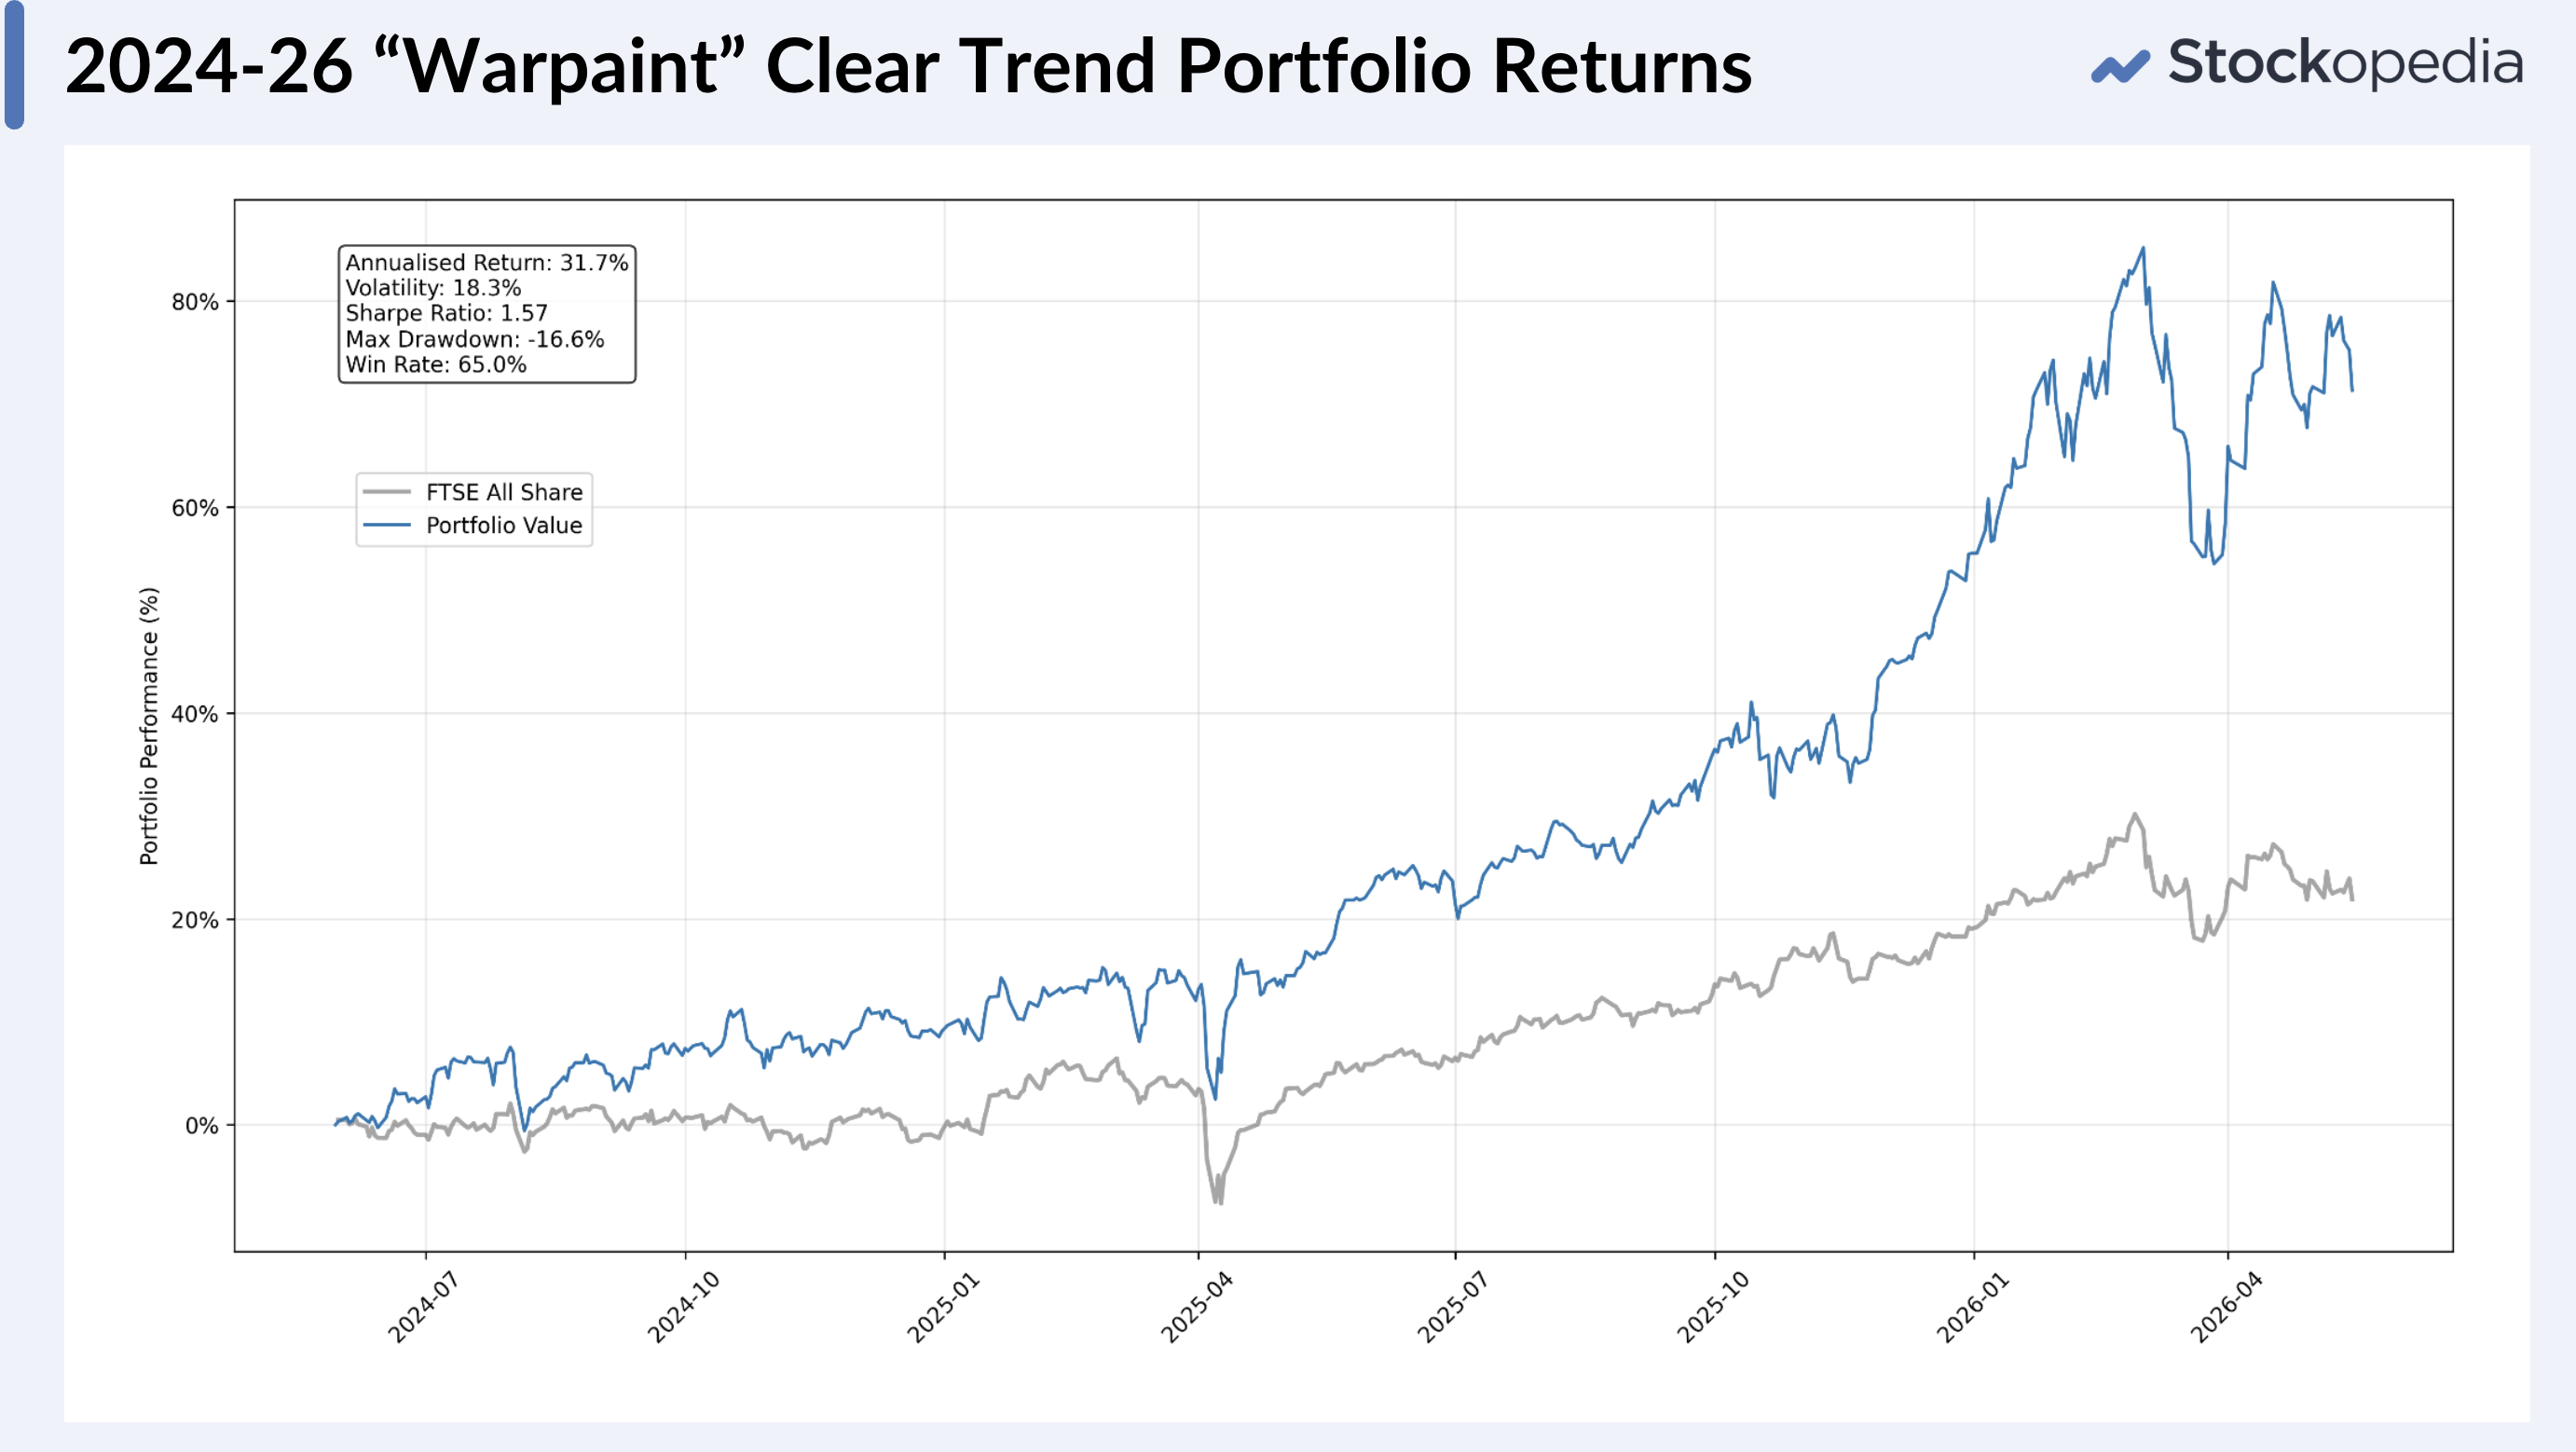
While the research is robust, two years of published returns now back this strategy up. The May 2024 "Didn't buy Warpaint?" portfolio is up 71% against the FTSE All Share's 22%. The June 2025 "Didn't buy Rolls-Royce?" list did it again - +30% in just eleven months vs +15% for the FTSE.
This year's top 20 are laid out below, but the same mental aversion applies - every share already looks "too late". You are likely to feel huge resistance as you read these names and their charts. But it's this psychology that underpins why the approach works - when everyone turns away, stocks are often underbought.
One thing worth mentioning. The share I name in the title each year has a habit of not leading the next pack. Warpaint slipped 12% in the year after the 2024 piece (and collapsed 64% over two years). Rolls-Royce has kept rising and made eighth place. As for Serabi Gold itself - up 412% since the 2024 list after 2 years of inclusion - it's not made the cut this time. Will it sustain its momentum?
The rules, recapped
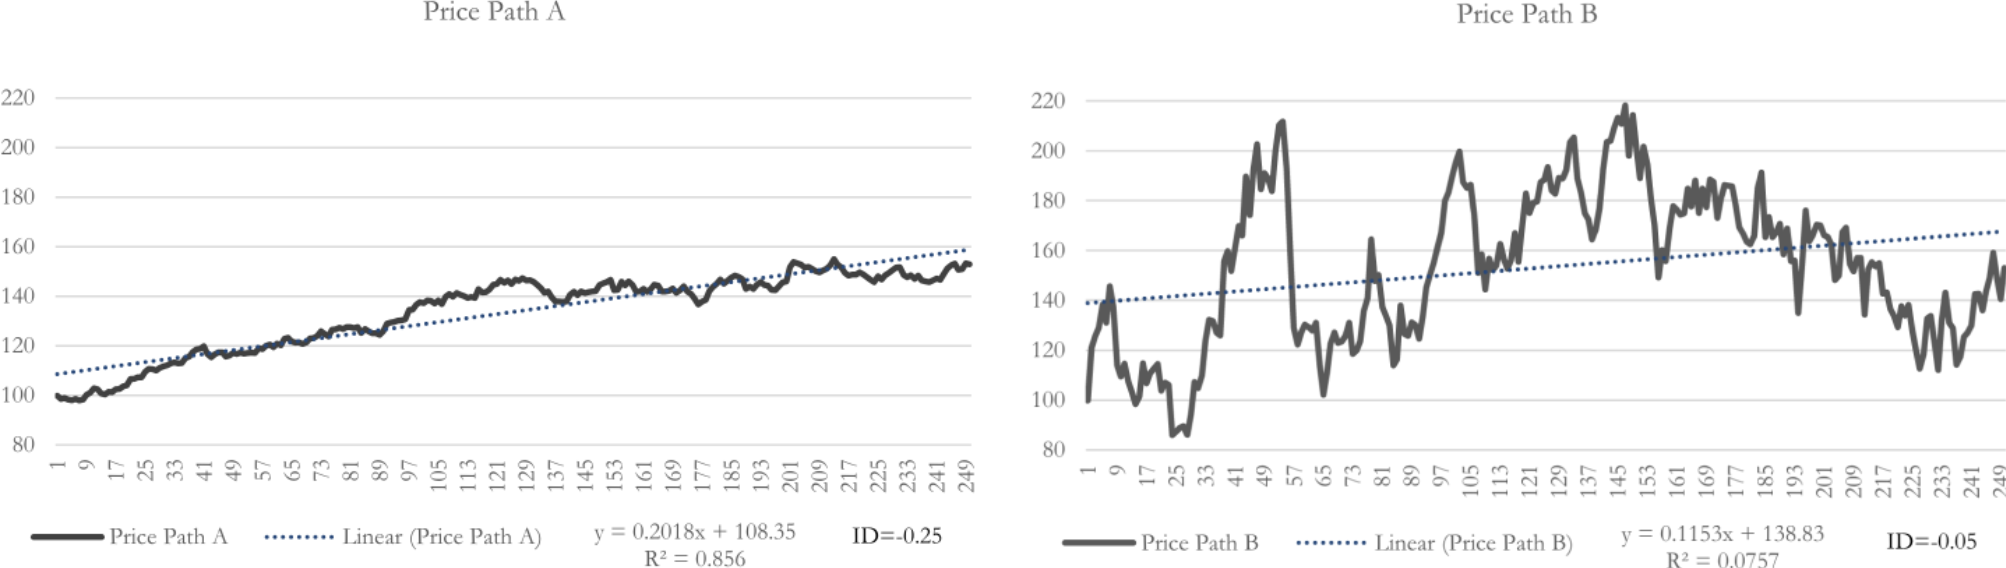
A 2024 paper called Trended Momentum showed that shares whose price charts trace a smooth, orderly line - high "trend clarity" - significantly outperform standard momentum. You measure it with the r-squared of a regression line through the share price. The original write-up has all the details - but the graphic below is easy to understand - you want to pick a smooth glide path, not a wild one.
Here are my own rules, which skew towards higher ranks:
- Start from the 75+ StockRank universe (a touch broader this year as the UK universe has shrunk).
- Filter to the top 20% by six-month price strength (high momentum).
- Calculate R² for each (clear trends).
- Take the top twenty, equal-weight.
When I first ran the numbers yesterday, I used a 12-month lookback, which did keep Serabi Gold on the list. But for consistency with the previous two articles, I've stuck with 6 months - but the macropolitical friction across that timeframe completely changes the underlying set. What emerges is a very different picture from the one I was expecting.
The 2026 portfolio and what it's telling us
I always like to research data-first, narrative second - I want the rules to do the selection, rather than the stories. But I enjoy pulling out the investing themes after a screen runs. It helps to understand what the market is currently rewarding and what you might have missed.
This year's list reads quite differently from last year's. The unifying idea across the set is that constraints and bottlenecks are driving returns. It's pointing at companies that profit when things are in short supply - like calm markets, barrels of oil, critical minerals and datacentre foundations. Scarcity drives profitability and reratings for companies that can fulfill supply.
It's also worth noting the sectors that don't show up in the list. No software compounders, no UK domestic banks, no housebuilders, no utilities, no pharma majors. Many of these industries are exposed to inflation and rate hikes - maybe that's the price of a bottlenecking world. And interestingly, in counter to recent years - no major defense stocks.
Here is the top twenty that qualify for those rules, ranked by trend clarity. The themes are explored further after the table.
Name (Ticker) |
Sector |
Mkt Cap £m |
StockRank |
R² |
Seplat Energy (LON:SEPL) |
Energy |
3,456 |
93 |
0.97 |
Georgia Capital (LON:CGEO) |
Financials |
1,381 |
83 |
0.92 |
Tortilla Mexican Grill (LON:MEX) |
Consumer Cyclicals |
28 |
81 |
0.92 |
Capricorn Energy (LON:CNE) |
Energy |
224 |
99 |
0.91 |
Keller (LON:KLR) |
Industrials |
1,621 |
98 |
0.91 |
Glencore (LON:GLEN) |
Basic Materials |
67,396 |
80 |
0.90 |
Pharos Energy (LON:PHAR) |
Energy |
121 |
92 |
0.88 |
Goldplat (LON:GDP) |
Basic Materials |
25 |
99 |
0.86 |
AEP Plantations (LON:AEP) |
Consumer Defensives |
845 |
98 |
0.85 |
Enquest (LON:ENQ) |
Energy |
371 |
95 |
0.85 |
IG group (LON:IGG) |
Financials |
5,080 |
93 |
0.85 |
Luceco (LON:LUCE) |
Industrials |
376 |
96 |
0.84 |
Afentra (LON:AET) |
Energy |
165 |
97 |
0.84 |
Amigo Resources (LON:AMGO) |
Financials |
33 |
82 |
0.84 |
CMC Markets (LON:CMCX) |
Financials |
1,061 |
95 |
0.83 |
MTI Wireless Edge (LON:MWE) |
Technology |
55 |
97 |
0.83 |
M P Evans (LON:MPE) |
Consumer Defensives |
975 |
98 |
0.82 |
Tullow Oil (LON:TLW) |
Energy |
247 |
78 |
0.82 |
Polar Capital Holdings (LON:POLR) |
Financials |
784 |
96 |
0.82 |
Tpximpact Holdings (LON:TPX) |
Technology |
45 |
91 |
0.81 |
Let's dig into some themes:
- African energy is in play - the Hormuz effect - This is the single biggest cluster, new and a real eye opener. Seplat Energy (LON:SEPL) , Capricorn Energy (LON:CNE) , Pharos Energy (LON:PHAR) , Afentra (LON:AET) and Tullow Oil (LON:TLW) - these are all Africa-focused upstream oil and gas names. With the Strait of Hormuz disrupted, reliable barrels outside the Gulf are in much demand. The majors have retreated from Africa, and these names qualifying all at once suggest that Europe may be scrambling to secure supply. Is this a temporary blip or the start of a structural supply shift?
- AI and Tech Infrastructure in play - This has been such a hot theme - Keller (LON:KLR) appearing on the list is no surprise as the global geotechnical contractor doing the foundation work under hyperscale US datacentres. Meanwhile Polar Capital Holdings (LON:POLR) runs the successful listed Polar Capital Technology Trust - packed full of big US tech and supply chain names. The one year lookback portfolio contained names like Volex in this theme too.
- Market volatility benefiting brokers - Another theme our editorial team have been strong on - the companies that earn from market volatility. Two pure-play UK spread-bet / CFD specialists qualifying together is a sharp signal. IG group (LON:IGG) and CMC Markets (LON:CMCX) both thrive when markets are jumpy - investors trade more. Of course this could reverse if markets return to calm, but these businesses have been diversifying successfully.
- Indonesian palm oil - AEP Plantations (LON:AEP) and M P Evans (LON:MPE) are both pure plays. A decade long ESG investment trend put a big squeeze on financing palm oil plantations, as did limits on deforestation. We've well flagged these names. Markets are simple. Own the supply when demand keeps rising and you can do rather well. I was reading that there could be a troublesome El Nino this year, which would increase palm oil prices further.
- And the rest - The remaining stocks span various other bottlenecks - Glencore (LON:GLEN) for copper and other resources, Amigo Resources (LON:AMGO) for a quite extraordinary recent pivot from lending towards Tanzanian rare earths and gold, MTI Wireless Edge (LON:MWE) is selling military antennae to the Israeli defence sector, Luceco (LON:LUCE) pushing into UK EV charging and cabling..
In the last two years, gold and copper stocks were among the biggest performers (e.g. Pan African Resources (LON:PAF) +451%)- so only one partial exposure is a surprise in this set. The unifying theme seems to be that right now - it's bottlenecks that matter.
What to watch out for
We've found that Momentum is the most powerful of all the three QVM return drivers - and smooth, strong trends even more so. Both the last 2 year's portfolios have outperformed the NAPS by 5% per year. The backtests in the research suggested this, but it’s impressive to see it in real time.
A word of caution before anyone runs out and buys this list based on past performance. Yes these are quite high ranked stocks - generally profitable etc - but this list is highly loaded to recent 6 month momentum. Hormuz disruptions, market volatility, hyperscaler capex - these are big themes which can and may well reverse. All the portfolio needs is for one of these to run further than expected to power outperformance - but watch for trends that break.
Anyway, let’s finish with a game - out of this list, which company name is the one that's going to be next year's eponymous "Didn't buy {regrettable-missed-opportunity}?" - Place your bets!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

72 comments
Coal is off the radar of most investors but prices of thermal coal are rising sharply. Your section on “African energy names” does not include Thungela (LON:TGA) which has thermal coal mines in South Africa and Australia. Low PER, high dividend yield and trading close to tangible NAV.
Interesting that the African Energy names, after a mean reversion, are performing well - Seplat Energy (LON:SEPL) on a tear since this article and all 5 in profit.
And the overall portfolio doing almost as well - but in a rather tidier fashion. I don't expect the 56% annualised return to persist - but you never know.
Barbara: on 24 May, you kindly posted a R2 formula for Google sheets. This was as follows:
=LET(
s,$A6,
d,GOOGLEFINANCE(s,"close",TODAY()-182,TODAY()),
p,INDEX(d,,2),
nums,FILTER(p,ISNUMBER(p)),
RSQ(nums,SEQUENCE(ROWS(nums)))
)
I am assuming this is a 6-month R2. However, in your husband's rules, he states:
Stockopedia doesn’t calculate R², so I export to Google Sheets and calculate it myself — both 220-day less current month and 65-day windows.
Just for absolute clarity, could you please confirm what the forumlas should look for these two windows. In particular, I am a little confused as to how the condition "less current month" is incorporated in the forumla.
Last but not least, just to say how much I appreciate the knowledge and research being shared. Thank you!
The formula doesn't remove the last month, to do that you'd have to change the second TODAY() to TODAY()-30.
Apologies Saucepan I’ve only just seen your message. This is the formula to ignore the past 20 days
=LET(
s,$A2,
d,GOOGLEFINANCE(s,"close",TODAY()-220,TODAY()-28),
p,INDEX(d,,2),
nums,FILTER(p,ISNUMBER(p)),
IF(COUNTA(nums)<2,NA(), RSQ(nums, SEQUENCE(ROWS(nums))))
)
Results for Stockrank R2 portfolios for week ending 12/6/26 are as follows. If you want to see the results for all 12 of the r2 portfolios they are posted every week on Substack. This is the link https://rulesbasedmomentuminve...
Results for week ending 2026-06-05
AEP Plantations (LON:AEP) M P Evans (LON:MPE) R E A Holdings (LON:RE.)
Indonesia has now published the detailed rules for its new export system, and it appears that existing long‑term contracts can still be fulfilled. Am I right in thinking this removes the worst of the earlier fears around MPE, AEP and REA, even though the new DSI framework still stands?
Separately, I’ve been reading about the rising probability of a strong El Niño this year and the potential impact on palm‑oil yields. If that’s correct, the medium‑term backdrop for CPO prices could be tighter than the market is currently pricing.
I’d be interested in views from those who follow this more closely. Does the combination of the policy clarification and the El Niño risk meaningfully change the outlook for these names? The market is unmoved this morning.
The El Nino is the least of your worries if you hold exposure to Indonesian palm oil. The current president is an unsavoury corrupt fellow who has been on a literal land grab - plantations and mines. Foreign investors are an easy target and squeezing them would play well to the domestic audience.
https://jakartaglobe.id/news/i...
Thanks JP — just to clarify, I was flagging El Niño as a potential positive for CPO prices, not a risk. Historical episodes suggest the main production impact arrives six to fifteen months after onset, so if a strong event develops this year, the medium-term supply backdrop could be tighter than the market is currently pricing — which would benefit these producers.
On the DSI rules, the picture is clearer than it was three weeks ago. Existing contracts can continue to be fulfilled during the transition period, and all three companies sell domestically rather than directly exporting, so the immediate operational impact appears limited. Real uncertainties remain around pricing methodology and DSI's fee structure, but I'm wondering if the acute panic seems to have overshot
On the political risk point, I'd separate two things. The broader trajectory of Prabowo's resource nationalism is a legitimate concern and worth watching closely — I don't think anyone following these names can ignore it. But the concession enforcement campaign so far has targeted Indonesian domestic operators with long-standing permit issues; none of the UK-listed names have been mentioned. AEP, MPE and REA have transparent governance structures and sustainability certifications that put them in a different category from the Duta Palma-type groups that have been seized.
We should, hopefully get a clearer view soon in any case. REA have their AGM update on Wednesday, MPE follow on Friday, and AEP's AGM is the following week — so all three should be giving some indication of how operations are running and whether they're seeing any practical impact. That'll be more informative than the current speculation.
Results for week ending 29/5/26
My understanding is that palm oil development is a major factor in deforestation of natural habitat whatever the companies claim. The lemur is virtually extinct in Madagasacar. I know it is difficult but lines must be drawn.
How is R2 calculated?
This is the formula to use on Google sheets SWIFT1467
=LET(
s,$A6,
d,GOOGLEFINANCE(s,"close",TODAY()-182,TODAY()),
p,INDEX(d,,2),
nums,FILTER(p,ISNUMBER(p)),
RSQ(nums,SEQUENCE(ROWS(nums)))
)
Thanks
To clarify was the R2 calculated over 6 months as well? Would be interesting to compare 6 vs 12 months as I understood academic literature to be saying 12 months was the sweet spot, or are you saying 6 months seems to be better for our markets? thanks
Luce
My husband has been posting on an adaption of this strategy for the past few months. He has a number of portfolios using Stockopedia to screen and rebalances monthly. I hope you find the results interesting. Weekly updates can be viewed HERE
I’m sure Mr Croft will be happy to see that the r2 portfolio based on stock ranks is the best performing with a ytd return of 16.24%
Hi Ed
Thanks for another interesting piece. It is interesting to compare the 6M & 12M charts of the highest R2 vs those lower down. The 6M tends to keep a smooth journey but the 12M often paints a different period. Looking back to previous article you mention a possible holding period of 12M - is that still the "plan" - provided the trend remains your friend with no nasty turn at the end - in the meantime !
I will throw my hat in the ring with Tortilla Mexican Grill (LON:MEX) - which I know nothing about (except have partaken in some burritos down the years) but on the basis that it is in "Consumer Cyclicals", which seems to be a relatively unloved sector and different to most/all the others appearing - has a fair chance of being near the top or bottom of the list after a year !
This is what would have happened if you’d created a NAPS like portfolio using stock ranks above 80 and then selected highest r2 stocks within each sector. All data based on Jan 2nd with r2 calculated on prices between 2nd July 2025 and 2nd January 2026. Note no utility stocks made the cut.
I think Capricorn Energy (LON:CNE) is in middle of takeover - should it be included?
Glad I did not buy AEP Plantations (LON:AEP) - down 25% day after this thread started.
... and M P Evans (LON:MPE) - down 25% the day after.
I don't know about AEP Plantations (LON:AEP) but M P Evans (LON:MPE) fall seems overdone. They already sell all their product locally and though there might be some disruption from the Indonesian government's announcement, the 25% fall looks overdone. I'm using it to top up! M P Evans (LON:MPE) is a well-managed company I hold for the long term.
Good point. I have loaded up with M P Evans (LON:MPE) after their announcement that this should not impact on their business.
M P Evans (LON:MPE) I suggest you re- read the announcement. If exporting Palm oil becomes more expensive then perhaps it will be a headwind for domestic pricing.
Looks like that was a good move with today's 10.7% rebound!
I owe you a drink for nudging me in the right direction. Thanks Mark.
Thanks Ed, for another thought provoking article and through following your Naps strategy and follow up postings I am pleased to see several investments familiar mentioned this morning. I am not sure if the list of 20 companies given was suggested as an upgrade to the original 2026 list and depends on the middle Eastern situation remaining relatively unchanged. I certainly missed out by a reluctance to go with MTI. Not realising that Netanyahu and his right wing IDF chums would escalate defence of Israel into domination of their entire sphere of the globe. If that is the case I'll need to start swapping some already fairly well performing stocks around?
Not realising that Netanyahu and his right wing IDF chums would escalate defence of Israel into domination of their entire sphere of the globe
This is a ridiculous comment. Why would you think this is a forum to make such an outrageous and inaccurate comment. This is part of the reason this country is struggling so much with antisemitism, because people think such comments are acceptable and are happy to spew mis-information and hatred.
Criticism of the state of Israel is categorically not the same as antisemitism, any more than loathing Trump and his policies is to be anti-American. For that reason I I can share exactly the same reluctance to invest in MTI Wireless Edge (LON:MWE), while not regarding myself as remotely antisemitic. Investment choices are also sometimes moral and political choices.
Perfectly well put Brucie. Several of my own family members are Jewish and I am certainly not antisemetic and meant no criticism of Israel, but like the US with Trump as you point out, the leadership and direction gives me pause for thought when investing.
Well Said? Why? Because he defended your mis information? Maybe you should ask your family members what they make of your comment and if its acceptable to spew lies with loaded comments. The idea that you now say you meant no criticism of Israel is ridiculous. You are allowed to criticise and are free to have your opinions. But when you make loaded comments not based on any fact, expect people to stand up for what's right / true, and to call you out!
The original comment was perhaps an exaggeration, but it clearly wasn't antisemitism.
Your intention seems to be to smear Bob as a racist. That's not right.
I want to make it clear that this is an investment forum and divisive politics is not appropriate. We've had threads descend into these areas and it never ends well.
We're ok with modest debate and reasoned differences of opinions on sensitive topics - when it descends into accusations, personal attacks or worse we can't tolerate it.
I've already had to moderate a few comments - and any more on this topic will be instantly moderated.
This thread is about clear trending stocks and the trends moving those stocks. That is all.
Thank you - remind yourselves of the moderation rules and more importantly basic etiquette.
Any reason why Star Energy (LON:STAR) doesn’t appear on the list as I have it as an r2 of .9
Looks like we can cross MP Evans and AEP off the list. Greedy governments, eh? When will they learn.....
It looks like the cause of the fall is this: (Indonesian gov to take control of some commodities exports):
https://www.reuters.com/busine...
Wonderful quote on Reuters concerning the Indonesian palm oil move.
"The (export control) agency may create more distortions instead of being the solutions to the distortions, on top of already severe distortions that exporters face," said Rizki Siregar, an international trade economist at the University of Indonesia.
Worth looking at M P Evans (LON:MPE) response: https://newswire.tickerapp.net...
Yes indeed - unfortunate timing for the Palm Oil stocks mentioned ! If I had an emoji picker it would be a {face palm}
To those despairing on their MP Evans and AEP share price falls today, me included, demand for Palm oil hasn't been switched off and supply is already becoming more restricted. Therefore the price of this vital food product staple and profit to be made from it can only increase, even if some portion of that must benefit the grower's host country government. These two particular companies have produced astonishingly good results in adverse weather conditions and it may be too soon to panic and sell until the full effect of the export controls or tarrifs intended.
A very interesting post Ed. Having decided some time ago that individual stocks are too volatile for me, I have been trying to invest in ETFs displaying smoothly trending momentum.
My investment strategy has evolved into having some defensive assets in the form of ERNS (a short-term bond ETF) and CGT and PNL (multi-asset investment trusts) together with a reasonably diversified set of large ETFs (with assets gretaer than £500 million) that are selected using the JustETF website with the rules that they should all have positive 1-year and 6-month previous returns and prices above their 200-day simple moving averages, and also have highish values of (1-year previous return / 1-year previous volatility) although I ignore bond ETFs that can have very high values of this measure due to their very low volatilities. I try also to avoid buying ETFs with 1-year volatilities greater than 30% in order to reduce risk, and also to have lower weightings in the more volatile ETFs for the same reason. I use ETFs rather than ITs nowadays (apart from CGT and PNL) because: ETFs (unfairly in my view) do not incur 0.5% stamp duty on purchase whereas ITs do, large ETFs tend to have smaller bid-offer spreads than ITs, and ETFs tend to be less volatile than ITs because ETFs always trade at NAV whereas ITs don't. I've been following this 'absolute momentum' ETF strategy for about two and a half years now, and so far it has worked well (with better returns and smaller draw-downs so far than a global equity index tracker fund). But that might just be because the past two and a half years has been a favourable period for this type of strategy. However, I do trade some ETFs in my portfolio every few weeks, and this requires quite a lot of effort, in researching and deciding which ETFs to trade, and also in the administrative work needed to keep track of a changing portfolio.
In case anyone is interested, my current portfolio is:
iShares £ Ultrashort Bond GBP ETF (ERNS) 11.0%
Capital Gearing Trust (CGT) 5.5%
Personal Assets Trust (PNL) 5.6%
WisdomTree Physical Gold GBP Hedged ETC (GBSP) 8.7%
Amundi Bloomberg Equal-Wt Commodity ETF (COMG) 7.7%
State Street Global Convertible Bond ETF (GLCB) 8.3%
iShares World Value Factor ETF (IWFV) 15.6%
Amundi New Energy ETF (NRJL) 7.3%
iShares Semiconductors ETF (SEMI) 6.8%
Xtrackers World Energy ETF (XWES) 3.9%
iShares UK Dividend ETF (IUKD) 9.6%
VanEck Developed Markets Div Leaders ETF (TDGB) 9.9%
Definitely interested thank you for the disclosure Rob
Interesting thanks, what has the yearly performance been like out of interest? Obviously low vol is an added benefit rather just returns.
Goldplat (LON:GDP) on R² 0.86 and Keller (LON:KLR) on R² 0.91, have both published strong trading updates today. Onward and upward!
Luceco (LON:LUCE) is the ONLY London quoted share on Phil H's QM Blueprint Screen ATM
Yes I’ve bought on that basis
Couple of questions- did the R2 value determine whether the share qualified for the top 20 ie is the list the top 20 purely by six month price strength or have you excluded shares which have greater price strength but maybe due to a one day large price rise eg takeover speculation. S4 Capital comes up in the search I tried but was it excluded because it hasnt risen smoothly for the last six months. Secondly have you looked to see whether the results are improved if you purely look at the Momentum Rank rather than the Stock Rank. Stockopedia has a model for the stock ranks with NAPS, so it would be nice if we could have something that highlights different shares.
S4 didn't make the cut due to a lower R-Squared - it probably would qualify on a shorter e.g. 3 month R2.
It's a good idea regarding using the Momentum Rank. As you'll know, the momentum rank does include an earnings momentum component, so it's not pure price momentum (which I'd want to avoid).
I have been thinking, given the interest in these approaches, that it might be quite good to launch a more official Active Momentum portfolio on a par with the NAPS. I'm still live testing some of the "significantly ahead" and "big jumps" insights that we've had over the last year or so and considering whether there's a hybrid approach which could be half event-driven, and have more passive clear trends. It would be quite fun to run.
Codename the "RIPS" portfolio. The NAPS and the RIPS - has a good ring to it! We're keen to launch a more official Model Portfolio area to the service - to bring these things a bit more structure than pure editorial.
RIPS Portfolio idea sounds great. It may need a basic filter for not opening new positions in bear markets (like Clenow has) and maybe a more active way of trading but I`m sure it can be done.
Why not combine the 2 using top 2 in each sector based on r2
Thanks Ed for another thgought provoking piece, much appreciated.
For what it's worth, my money would be on Enquest (LON:ENQ) to outperform their current S.P. This operator has in my view a great deal of untapped / undeveloped potential which once utilised would empower some serious revaluation. The fact that Momentum is up +6 over the past 30 days is no bad pointer either.
Thanks Ed, excellent piece as ever. I hold Keller (LON:KLR) and Polar Capital Holdings (LON:POLR) , so hopefully one of those!
I try and steer clear of too much speculative stock having bought five grand worth of Pan African Resources (LON:PAF) for 16.5p in May 2017.
Why the regret, you may ask? I must be sitting on the proverbial gold mine!
Unfortunately no: I got spooked by its poor performance and sold half the stock three years later: finaly divesting of the rest of it in August 2024 when I needed the cash, and didn't even break even!
I'm not sure what the moral of the story is, other than to sit on small cap stock for a decade... but I've enjoyed your webinars on when to sell, and am a bit more rigorous in my approach now, thanks to Stocko!
My bet would be Enquest (LON:ENQ. I don't own but most geared oiler to oil price out there imo. Mkt cap $500m, net debt @ $400m. Currently earning @ $40m FCF per month, debt to equity value transfer, 40-50kbopd, over $3bn tax losses so windfall tax doesn't apply. Mainly N Sea but some production in S E Asia as well. If oil price stays high then FCF in next 12 months could be same as mkt cap. A 40-50kbopd producer should be valued at min $1.5bn imo (@ $30k per bopd). Negatives are decom costs & criminal govt neglect of N Sea in pursuit of net zero madness.
Excellent...will certainly have a review on the ideas. The one I hold is MWE. One company that has issued a RNS this morning but not received comment is Pennant(Pennant International (LON:PEN) . Their QVMSR numbers are awful but their EPS growth is projected 1400% 2026 to 2027. They are facilitating paper manuals to digitisation in the defence sector as well as being in partnership with Siemens who are integrating Auxilium into their package. This is similar to what Eagle Eye Eagle Eye Solutions (LON:EYE) has done in the loyalty card process and Kainos (LON:KNOS) in many areas. I hold both of those. I would also.mention that both Hastings and Ronaldo follow this closely and I respect their views!
Thank you Ed, very insightful as always. In terms of your inviting "game" my bet is on AEP Plantations (LON:AEP) AEP. On the one hand the share price growth curve makes my eyes water, but with a PE of 10, PEG of 0.8 and ROC of 18% and a cracking balance sheet backed by conservative management, it still looks like a Goldilocks stock to me. Granted that it could be argued that we may be at the top of a COP price cycle, and granted that the weather is a clear risk as well as an opportunity, conservative management have evolved a well padded business highlighted by the Nusantra IPO, which backs up AEP Plantations (LON:AEP) AEP continued price attractiveness. In addition, the Pinago acquistion shows continued commitment to growth and, yes, I appreciate that some of this may already be priced in, however when one considers all of these factors I would be interested to hear which top 10 London stocks look more compelling right now in a world of growing demand for a such a versatile product. Anyway, each to their own but you've prompted me to go back in today, high on the growth chart hill at circa 2020p (hopefully 2020 vision) in the belief that the bull points highlighted provide sufficient oxygen to see 50% uplift over the next 3 years with a worth while dividend to provide some company. Off to apply similar logic to the rather more binary Serabi Gold (LON:SRB) now, which still displays spectacular metrics.
I meant 2220p, apologies
Well I'm going to go with CMC Markets (LON:CMCX) as it plays catch up on its peers. New ATH's due IMO.
Great article and research Ed. I hold a few of those listed above since in recent months (based on your published research) I've been experimenting with part of my portfolio into high QM ranks and earnings upgrade stocks. Performance is encouraging so far but I'm early into the experiment. Your 2 year history builds confidence for the rest of us.
Is there a way we can copy your screen so we can research further? Also how do we calculate the R2 or is there a filter in your screening tool for this?
Wildshot - the r-squared is hand-cranked right now. Yes, it should be screenable. We are working on a different area of the service at the moment, but we'll get round to improving the screening fields soon enough.
It's interesting when you interrogate this list because the average share on this list has risen by 120% in the last year. That creates vertigo. Nonetheless, the median earnings yield is 11% - which is impressive given the price rises. It's not a premium list - it still skews towards value.
Ceres Power Holdings (LON:CWR) : watched it, as my father used to tell me wrt learning the game of tennis, "right onto my racket" - about this time last year - only to let it go. I try my best not to look at it now.
;)
I can do better than that, bought at 200p sold at 45p now 700p. So bad it's embarrassing rather than annoying
I sold Filtronic at £1 taking a 20% profit and thinking I was clever!
Thanks Ed - an interesting read.
My half-crown bet is on AEP. Why? I suspect a food related commodities surge may be on the way and had that in mind even before the latest El Nino story. In passing, I hold a different palm oil producer - REA Holdings whose 9% Prefs have done me well over some many years.
The Indonesian president Probowo owns 20 palm oil companies! Indonesian Rupiah is in free fall, economy is struggling. It is safe to say palm oil exports are high on the export agenda. Personally, having seen from the air the apocalyptic destruction of the rainforests, I cannot invest in palm oil.
I went with R E A Holdings (LON:RE.) too as a turnaround that may follow the likes of M P Evans (LON:MPE) and AEP Plantations (LON:AEP) however a direct stocko comparison makes AEP Plantations (LON:AEP) the winner ATM.
Its a winner unless you are a native of Sumatra in which case its a killer .
Thanks Ed another fantastic article.
Momentum seems to be the strongest factor, but it does occasionally suffer from dramatic drawdowns when the narrative changes. Some academics argue that this risk is the reason the factor premium is not eroded away.
With that in mind, it would be useful to have an escape route when disaster strikes. I suggest a stop loss at the 20% mark. Alternatively limit the portfolio to no more than four shares in each theme / industry.