GuruScreen Movers - June 2nd: Focus on Character Group (CCT)

The UK’s fourth largest toymaker, Character Group, has enjoyed a strong run this year. The price jumped 9% yesterday after the company was tipped in the Investors Chronicle. However, Paul Scott has warned of the dangers of stock tips. They can trigger short-term spikes before the prices revert to their previous levels. Indeed, for these reasons, Paul sometimes sees tips as a selling opportunity.
It is impossible to judge what Character Group will do over the next few days. But to assess the company's longer term prospects, it is useful to analyse whether the firm is exposed to factors which have historically driven share price returns.
Quality minus Junk:
Ben Hobson mentioned Character Group in a recent article on the size-effect - the theory which holds that small stocks outperform larger stocks. Academic research suggests that good quality small stocks tend to outperform good quality large stocks, at least over the long-run. Small caps may be small because they are unprofitable companies, which are unable to grow, and offer unattractive returns to investors. But if you dump the junk and focus on a basket of good quality small companies, the size effect becomes more pronounced. Small tends to beat big.
With a market cap of £91.9m, Character is amongst the smallest companies in the stock market. But is Character Group a high quality small cap? The company has a QualityRank of 99 out of 100. Firms with a higher QualityRank are usually stable, growing, cash generative businesses with high returns on capital. They may also be companies with a strong balance sheet and improving fundamentals. For example, you can see from the table below that Character Group has trended higher in previous years, with wider profit margins and a stronger return on capital.
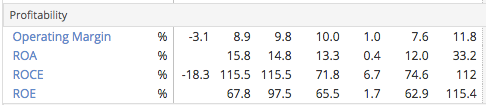
Character Group also has the traits of a growth stock. Brokers expect earnings to grow more than 50% in 2015, supported by the launch of new product ranges, including a new ‘food play’ collection. Revenues have already grown steadily since 2013, thanks in part to its portfolio of iconic toy brands, including Scooby Doo and Fireman Sam. The strength of these brands means that revenues are perhaps less susceptible to the fads and fickle tastes of the highly competitive toy market.
High Piotroski Score
The Piotroski F-Score is one of the most useful metrics to assess whether a stock has improving fundamentals. The F-Score seeks to identify companies that are profit-making, have improving margins, don’t employ any accounting tricks and have strengthening balance sheets. Character Group has the highest possible F-Score (9 out of 9) and also qualifies for Stockopedia's Piotroski F-Score PE Screen, which searches for companies with cheap P/E ratios and high F-Scores. So perhaps Character Group isn't just a good quality company. It may be a good quality company trading at bargain price. Indeed, the company has a PE ratio of just 9. Assuming that earnings grow by 54% (in line with broker estimations), the company would still have a PE ratio of just 11 - within the cheapest 25% of the market.
Strong Price Momentum
Character Group's share price has popped. Up nearly 10% yesterday. Up 126% over the last 12 months...! Research in the field of behavioural science suggests that investors are often reluctant to buy shares when the price has already gone up. It is more intuitive to buy low and sell high. So when companies announce good news, like record profits, investors underreact and share prices move upwards to reflect new information very slowly. For these reasons, stocks which are rising in price tend to keep going up, at least for a while.
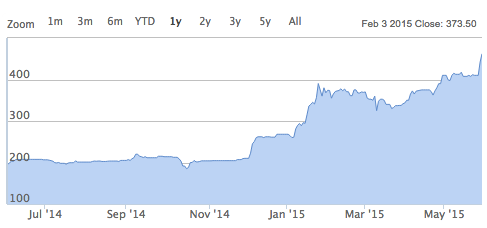
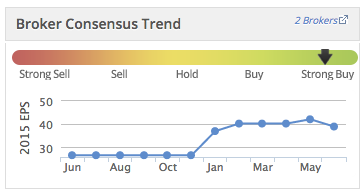
We don't know where Character Group will go from here. However, the company does seem to be exposed to the momentum factor. The firm qualities for the Tiny Titans Screen, which filters for stocks with strong price momentum and a cheap PS ratio. Furthermore, brokers are generally becoming more optimistic about this company. The EPS forecasts have risen from 26.6p to 38.8p over the last twelve months (see below).
Conclusion
Character Group is exposed to four factors which have historically driven share price returns: quality, value, momentum and size. The company is a small cap, but it also has a high QualityRank and Piotroski Score, not to mention cheap PE and PS ratios. Furthermore, the firm has beaten the market over the last years and brokers have become increasingly optimistic about the EPS forecasts. The company’s overall StockRank is 98. To filter the market for potential investment opportunities, why not explore Stockopedia’s GuruScreens and StockRank Portal. If you want to take a free trial of our service, just check out our plans page: www.stockopedia.com/plans/
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

9 comments
If you buy and the sp falls, if you still comfortable with the company you can double up at lower price then if sp goes up passed your original purchase price you can sell the first lot of shares, then you have the shares at a lower price. Of course there are risks. It has work for me on several shares, most recent was Solid State (LON:SOLI), bought at 741p fell to 600p buy more @ 603, sold the first lot @ 801p. So in effect I have bought the shares for about 560p.
Of course they could have fallen below 600p and stayed below then you are in a value trap.
Yeah thanks for that but I didn't know about the IC tip until after I bought it my fault but got the div on the 4th hope it comes back it should I guess, rough week on my portfolio, sell in May.................
I bought CCT last Tuesday it's now down 10% great! Iv put the fall down to x div date and FT fall this week
I think the main reason the share price went up was of the Investors Chroncile tip, market makers increase the price at start of trading, investors still buy so sp goes up more, old holders take profits so sp falls.
Incidentally, this is from the latest Edison note on Entertainment One (LON:ETO), the owner of the "Peppa Pig" brand:
"The Family division materially outperformed our original expectations in FY15, with revenue up 71% to £60.8m and EBITDA of £23.8m (FY14: £10.3m). Our Update report dated 21 May 2014 forecast FY15 EBITDA of £12.0m, although this was revised upwards during the year and post very strong Christmas 2014 trading. The roll-out of Peppa Pig across international markets (including SE Asia and Latin America) has delivered profits earlier than we expected (broadcast deals give brand exposure but most of the profits come from licensing and merchandising). Peppa Pig now has over 600 licensees globally, 180 broadcast territories and 250 live broadcast agreements. Retail sales of $1bn (£650m) are more than three times the level of four years ago. An illustration of Peppa’s global awareness is that over 3 million paid apps have been downloaded globally, and on YouTube the US, Mexico, Brazil and Russia all deliver a greater number of page views than the UK. eOne believes it can double retail sales to $2bn. For example, US retail sales are just beginning to take off (Walmart stores recently began selling a range of Peppa products and Target stores will carry them later in the year) and Peppa is soon to launch in China, broadcast by the main state broadcaster, CCTV and with a small initial licensing programme."
Character (LON:CCT) has the Peppa Pig licence for UK and, I believe, for a few other territories.
Peppa ought to bring home the bacon for CCT shareholders.
Although the launch in UK of "Yummie Nummies" (the "food play" range from Japan) was alluded to in the article, it's worth noting as well the (imo) tremendous potential in Character (LON:CCT) also now having the worldwide master toy licence (for plush and plastic toys) for the relaunched "Teletubbies" franchise. Here's an article from today's Guardian on this relaunch:
http://www.theguardian.com/media/2015/jun/03/teletubbies-bbc-return-touch-screens-stomachs
Character (LON:CCT) also has the licence for "The Clangers".
Imo, growth prospects are still excellent.
All IMHO, DYOR.
It is still a good undervalued share and I had it in my watch list for a while to buy, It narrowed down to 1 of 8 shares to consider today. What put me off a little was the low volume of trades which means the bid offer spread was about 2% or 10 p. Not a very good argument for an excellent company, but that was about the only thing that stopped me,everything else is good.
It is never wrong to take a profit & top slice some profits. It is still a 52 week high. With a stock ranking of 98 The potential looks positive.
Having held since October 2014 with a buy just above 200p I am tempted to sell half my holding at this price and hope for a fall to top up again. Then again, on fundamentals I could still be a buyer at this price! Decisions, decisions.......
Alex,
Great article - I brought into Character in April and my notes at the time... "52 week high with record half year, Momentum/Quality play on very low PE of <10, F9 Stockrank 98 and Quality 99, Operationally geared + Share buyback make it a Buy". Cheers Ian