Hunting for compounders - Spectra Systems

Spectra Systems (LON:SPSY) is a fascinating company but summarising its operations is a challenge. That’s because there’s just so much going on at this industrious, innovative small cap.
Maybe we can crowdsource some additional insight in the comments… I’m keen to see what people make of this one.
It’s been on the research list for a while - possibly as a future Investment Club pitch - but while I’ve been taking a closer look, the shares have gone up 10% or so this past week due to a promising contract announcement (covered below).
For those companies with substantial upside though, a 10% rise should be loose change in the grand scheme of things.
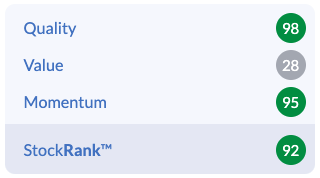
Spectra is a profitable, innovative, cash generative technology business with no debt, stable long-term income streams, and some fantastic growth opportunities. The high StockRank is no surprise:
The group has pumped millions of pounds into research and development in order to get to its current position, and it has the proprietary tech and materials to show for it.
It also faces into some substantial markets for a £90m small cap:
- Banknotes - over 150 billion banknotes manufactured annually vs. 45 billion banknotes with Spectra security features worldwide,
- Global lotteries - estimated at over $300bn, per MarketWatch,
- Tobacco manufacturing - Spectra TruBrand ™ materials on 6m packs of cigarettes in FY19, with billions more likely to come,
- Keurig coffee machines - optical materials used in disposable coffee K-cups.
With all this activity and potential, if you take a step back then a 10% move doesn’t mean you’ve missed the boat.
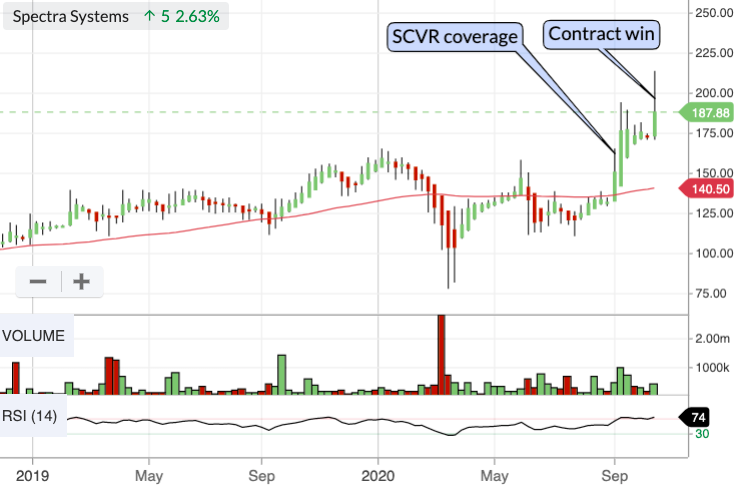
So let’s take the contract announcement and strong share price as a sign that we might be onto something here, and continue with the research…
What does it do?
Spectra’s core profit and cash engine is longer term contracts providing products and services to help authenticate and process banknotes.
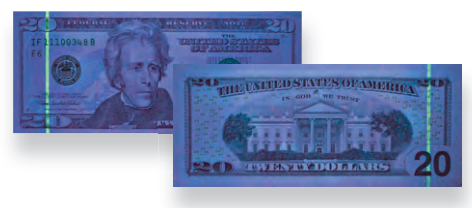
It makes the fancy bits in banknotes and passports that shift and shimmer under the light among other things.
Company accounts
That’s the simplified version, of course - there’s plenty more going on at Spectra. It’s clearly a smart, ambitious firm with its sights set on multiple ways of providing product quality and security services.
And you might think that banknotes are on the way out given the widespread adoption of digital payments, but apparently not.
In its first half update, Spectra said:
discussions with central banks during H1 have reinforced our belief that worldwide demand for banknotes will be significantly higher this year than last year and that this will positively impact our earnings in H2 of this year.
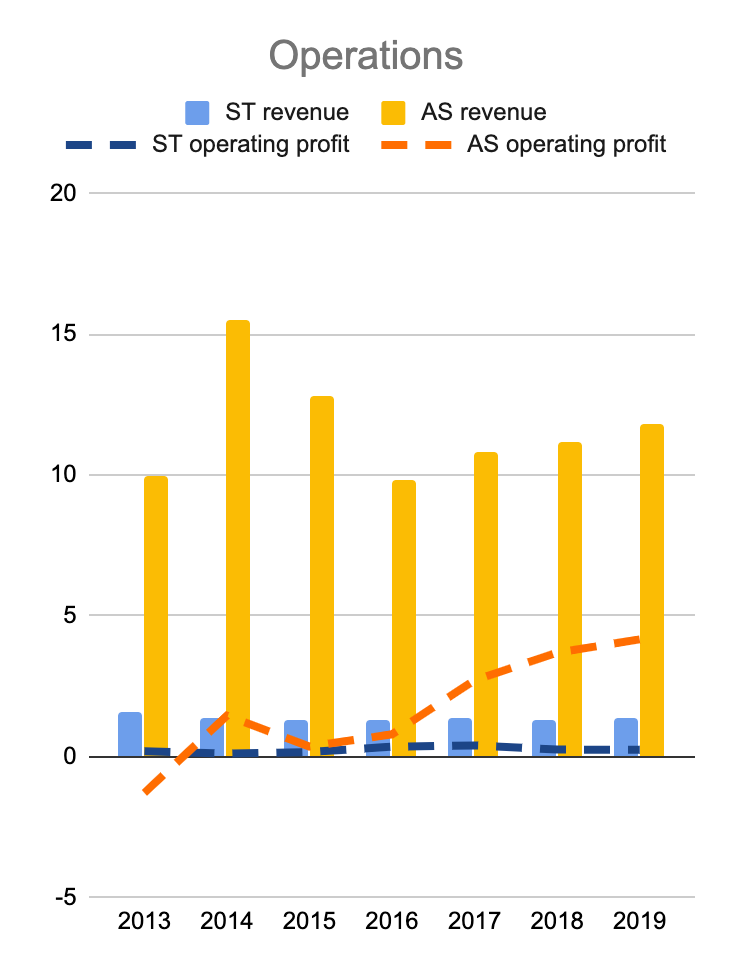
As of FY19, the group reported two operating units:
- Authentication Systems - $11.83m of revenue (89%) and $5.07m of adjusted EBITDA (92.5%) , and
- Secure Transactions Group - $1.41m of revenue (11%) and $0.41m of adjusted EBITDA (7.5%)
Authentication Systems includes Spectra’s central bank banknote dealings, consumer product authentication, and its optical materials which allows k-cups to be more compatible with Keurig coffee makers (K-cups being those little containers of coffee that coffee machines puncture and then flow water through).
Digging a bit deeper, Authentication Systems seems to be the real money maker here.
Spectra supplies an impressive list of clients, including national central banks, global security printers and papermakers, nationally approved lottery operators, passport makers, and multinational consumer product companies.
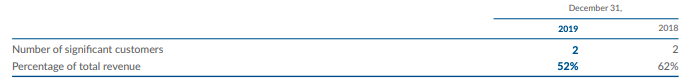
For all that though, client concentration is a risk with more than 50% of revenue coming from just two customers in the prior year.
History
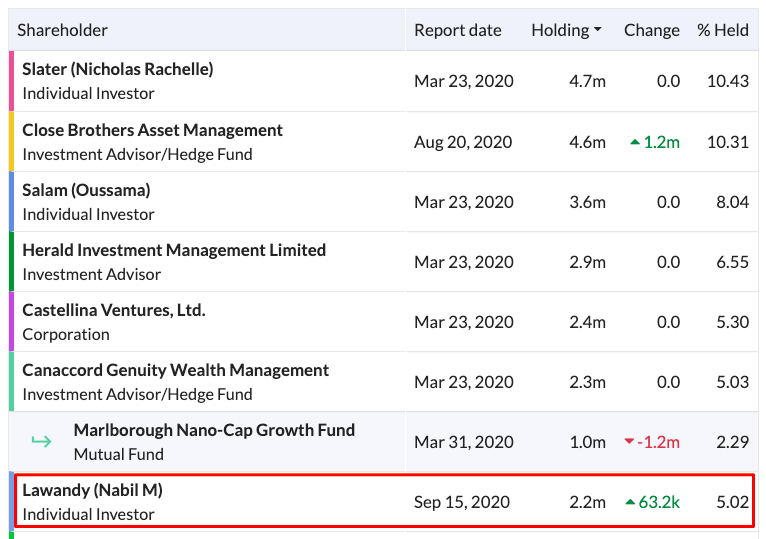
Spectra is the ever-evolving brainchild of founder and current president, CEO, and 5% shareholder Nabil Lawandy, who set it all up in 1996.
Before that, Lawandy conducted pioneering research into lasers at NASA and earned a tenured professorship in Engineering and Physics at Brown University.
Quite the resume… But what matters to investors is not the professional history of Lawandy but the commercial prospects of Spectra Systems.
On that note, Spectra’s impact looks to be quite far-reaching, with:
- $1m of lottery and gaming transactions processed by Spectra every day,
- 800m banknotes passing its authentication systems annually,
- 950m of energy drinks sold per year containing its materials,
- 10m bottles of wine protected by its technology over the past three years,
- 155m American passports protected by its materials in the last 10 years, and
- 45bn banknotes in circulation containing SPSY materials.
Spectra has spent millions in research and development over the past decade - about $22m or so. We can see the fruits of that labour in the group’s double-digit returns on capital and expanding operating margins.
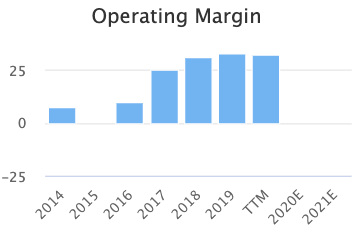
The group has proven adept at deploying its capital and continues to generate cash from long term security contracts with high quality clients. It all points to scope for substantial future value creation if Spectra can commercialise its product pipeline.
In the meantime, it is already a profitable, cash generative technology business with no debt, predictable long-term income streams. Revenue and profits have both trended higher over time.
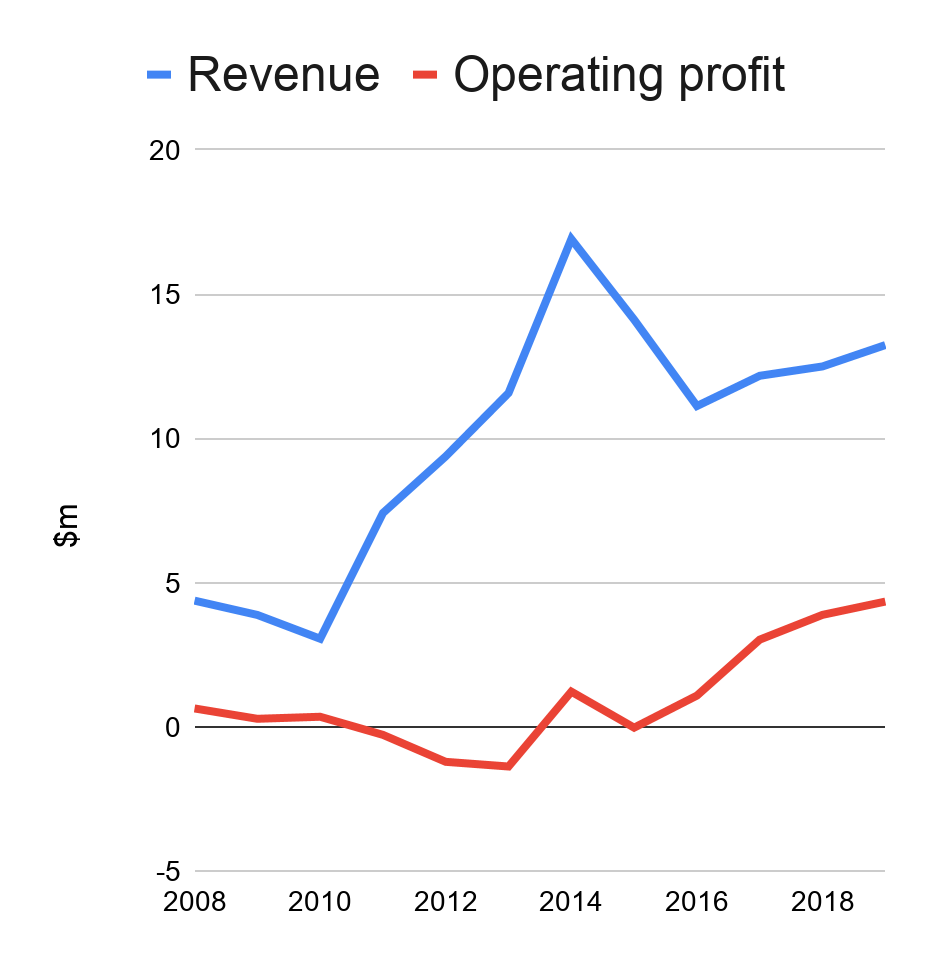
This mix of profitability, cash generation, and technological expertise and innovation is worth paying attention to - especially when comparing today’s market cap of £90m to the sheer size of many of the markets Spectra is either already in or looking to crack.
Strategy - multiple shots on goal
Spectra has so many initiatives the question becomes which lines of development will be material further down the line.
Group strategy is focused on 1) brand authentication, and 2) commercialising covert security technologies (with an emphasis on polymer banknotes and technology).
The brand authentication sector offers short-term growth potential and some large opportunities for smartphone-based technology, while the covert banknote security sector provides stable long-term, multi-decade revenues once new contracts are locked in.
Spectra also comments in its recent half year results:
Over the past four months, the Company has continued to explore possibilities of diversifying the business beyond authentication in areas where we can support this initiative with our world class core competencies in optics, engineering, physics and chemistry. We have identified certain intellectual property owned by another company, obtained academic feedback from Harvard University on this technology, and are now in the process of having the issued patents valued through an independent third party which has expertise in this area. The current candidate technology has applications to biotech assays, point of care testing and metrology. We expect to have made a decision on this specific technology by the end of H2.
The group seems to be pushing on a lot of doors and there is plenty to look forward to. It splits opportunities between short term (2020-2022) and longer term (2023-2025).
Short-term opportunities:
- Fulfillment of large orders for materials to a central bank customer;
- Additional funding beyond the currently contracted research program with a central bank customer;
- A multi-million dollar sensor development contract with a central bank customer;
- Increased number of tobacco packs sold in China with TruBrand materials and smartphone App;
- Adoption of phosphors for use by a supplier of products to a major Asian central bank;
- Expansion of the optical materials business with compostable K-cup customers;
- Sales of Spectra’s newest patent pending phosphor product; and
- Sale of its first Aeris banknote decontamination system to a gaming casino.
The longer term opportunities are:
- A licensing and supply agreement for polymer-based technology developed with a major central bank;
- Supply of further upgraded sensor capability to a central bank customer following the contracted development phase; and
- Sale of secure polymer substrate to central banks, which combines high security and a durable substrate in one product.
The group itself believes this combination of initiatives should be enough to continue revenue and profit growth through to 2025 while providing organic funds for investment in cutting edge technologies.
Catalyst - strong H1 trading and big contract win
The H1 figures are strong given the COVID backdrop:
- Revenue +1.8% to $6.5m
- Adjusted earnings per share down from 4.8c to 4.6c
- Cash from operations +14.6% to $2.3m
- Special dividend +28.5% to 9c
- Net cash down slightly to $10.9m
And hopefully there is a little more growth in store than what’s on show above. Operational progress is robust and broad-based, with strong sales of optical materials for K-cups, lottery contracts, and R&D.
The company certainly sounds optimistic of its prospects and ‘expects to significantly exceed market expectations, in spite of the COVID-19 pandemic’.
Maybe when it said that it had one eye on its most recent announcement just a couple of days ago - a contract announcement with a central bank.
This contract is split into a few phases:
- $1.9m to initiate Phase 1 development work,
- $5.6m in Phase 2 development through 2023,
- as much as $34m for the delivery of an as yet unspecified number of sensors, and
- a service component worth approximately $7.5m
It’s a promising hint at the scale of business SPSY could drum up in future.
Valuation - relative premium justified
This latest contract win validates the good work Spectra appears to have been doing for many years now. It also provides some useful forward visibility.
Beyond that, opportunities are rife and include:
- TruBrand’s Chinese tobacco printing trial,
- Continued strong sales of optical materials for K-cups,
- The launch of a new phosphor that performs better than rivals and can be sold for less,
- Increasing levels of polymer banknotes that can increase authentication revenues, and
- Ongoing COVID-19 studies on Aeris.
All of these opportunities are relatively advanced.
While a precise appraisal of its various business lines and prospects is probably beyond the scope of this article, brokers have raised their target prices on the back of this contract announcement from 200p to 240p.
What is more immediately obvious is Spectra’s strong financial position.
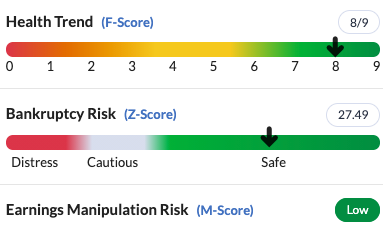
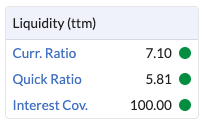
The only fail in the F-Score is a slight drop in the current ratio from 7.6x to 7.1x - still extremely comfortable, given that anything above 1.5x is typically seen as safe.
On that note, all of the group’s liquidity ratios are strong.
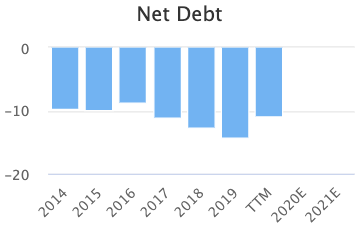
This is no doubt helped by the company’s prudent net cash position over time:
When you couple this strong balance sheet with the group’s cash generation - free cash flow regularly exceeds earnings per share - then SPSY passes some basic financial health checks with flying colours.
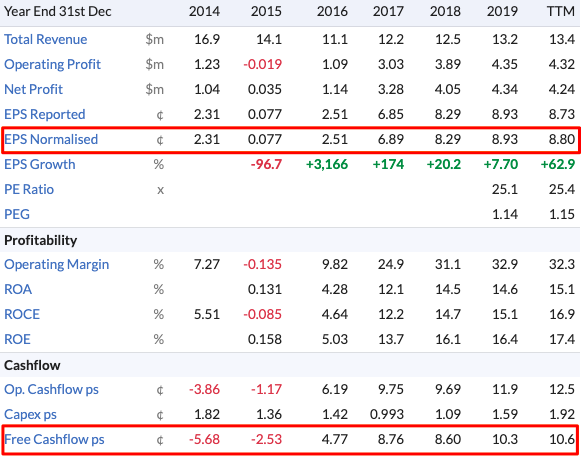
So that’s quite a promising picture of a sensibly managed, innovative, cash generative small cap with a probably big market opportunity and a founder-CEO that retains a stake in the business.
The above in my view justifies a premium relative valuation, with a good chance of upside in future once you take into account the group’s intellectual property, history of R&D and innovation, and stated target markets.
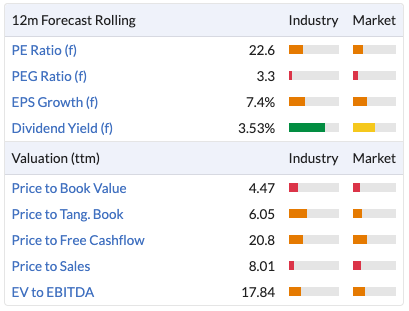
Conclusion
There is scope to increase market share of the growing polymer banknote authentication market here. And, as shown in the above, there are many other irons in the fire at Spectra.
That potential blue sky upside is supported by Spectra’s existing profitable operations, which are underpinned by stable contracts with high quality institutions. These contracts are cash cows that help fund all the other smart things the team is working on that might in time diversify revenue.
An exciting company with some promising prospects then, and certainly worth taking to the next level in terms of research.
No stock is perfect though and there are potential issues here too.
Even after a fair bit of research I haven’t yet got a firm handle on Spectra’s existing operations and the commercial scope of the company. And then there is the client concentration, possibly offset by the long term nature of contracts.
The good outweighs the bad here, in my view, but I’m interested to hear what others make of Spectra - did you buy, have you kept it on a watchlist, or did you find something that ultimately put you off?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

33 comments
Excellent article Jack. You expanded my knowledge re Spectra's activities! Please keep following this Company.
I have been following Spectra Systems for around 2 years holding the stock in an ii Isa. I completed a WBen80 form (via ii where I hold both an ISA and Trading Account) when I purchased Somero Enterprises (another US based stock listed in the UK) a while ago. One needs to renew (after 3 years?) but the procedure is not too challenging with the help of a knowledgable broker.
The Company has only become highly profitable in recent years following (IHMO) development of a considerable level of IP. It is led by a well qualified founder who leads a similarly well qualified small team of scientists who remain in close contact with former US University colleagues.
Information about their activities is hard to come by, maybe driven partly by their customers' wish to keep jointly developed technology under wraps, so if you are unhappy with this I would not bother to own the share.
It intrigues me that this year, Spectra put out 2 RNS advising news of their bidding for and losing out on a large contract because of failure to match the price of a competitor, who was offering a lower quality product!
The Company has been generating cash from its operations in recent years, pays an attractive well covered rising annual dividend and maintains a positive cash balance. Not great for ROCE but helps one sleep at night!
AJBell have got the WBEN80 thing sorted, it comes up pre-completed when you try to buy a US stock and took all of 10 seconds to complete and then allowed me to buy Spectra straightaway.
It would be interesting to know their thoughts / approaches to the likely advent of central bank digital currencies and whether they are deploying any R&D in that direction.
It would be interesting to know their thoughts / approaches to the likely advent of central bank digital currencies and whether they are deploying any R&D in that direction.
There's nothing in the public domain about Spectra having any interest in this area.
In any case CBDCs are unlikely to replace physical banknotes any faster than electronic payments and the range of options that Central Banks are considering are really varied, so it's probably wise to hold off spending money in this area at the moment. Most Central Banks seem to view them as a way of getting parachute money directly to citizens and businesses without having to rely on the banks to manage the process (which they do badly, in general).
But realistically there's not much overlap between physical banknote production / authentication and CBDCs which will be based on a mixture of blockchain and traditional payment technologies and probably mediated via the existing banking systems to ensure you don't get agency issues where everyone sticks their cash in the Central Bank as soon as a crisis looms.
The only real overlap is in terms of contacts at Central Banks - and possibly the relationships could be levered in this area. Possibly.
It's a fascinating area, but at the moment real-world CBDCs are years off and they're not likely to impact physical cash very much. And as the BoE points out there's nearly twice as much cash in circulation now than there was a decade ago:
https://www.bankofengland.co.u...
For Spectra's immediate future CBDCs aren't very relevant as far as I can tell.
timarr
I have tried buying Spectra Systems (LON:SPSY) in my ISA with Interactive Investor. But I can't because they think it's a US security and would need a W8BEN form. I have asked them to sort it out. So we'll see what happens.
I can buy in my ISA but I need to fill a W8BEN form out for any US shares, this is to do with the dividend and witholding tax.
Herbie Thank you for your reply. It looks like I can put Spectra Systems (LON:SPSY) in my ISA at Interactive Investor. But I won't be bothering due to the time I would have to waste on admin,
A great article, thanks - one to watch for me.
One quick question - is the information on customer concentration you've used available on Stockopedia?
Jack,
What do you think the realistic Target Price is for you?
The chart looks uptrend, but the fact that Directors been selling recently is not a good sign, what do you think
This company looks too good to be true. it's difficult to understand exactly what it does, and who are its competitors? It's a concern that AGMs appear to be inaccessible. The stock turn is extremely low.
The thing about Spectra Systems (LON:SPSY) is that you have to take their technology advantages on trust. I worked in the ID card / passport industry for a while and the security features that those rely on are kept secret - for obvious reasons. There are overt features, covert features and trick features, all designed to make counterfeiting difficult. Banknotes and asset protection features have similar properties.
They could be winning business because they have the best technology or the best pricing or the best contacts with central banks and governments or even the best supply channels. It's hellishly complex. In terms of valuation it's a black box which I wouldn't want to waste any time trying to unpick.
That said, the addressable market across all of the assets they could possibly help protect is huge. Against that, there's a lot of competition and as we can't assess their IP advantages it's difficult to make any kind of forecast or assess their moat, if they have one.
Anyway, I bought a few in the June dip and will continue to hold on financial progress. There's a possibility of a takeover too, although those are dependent on continued goodwill as maintaining relationships with central banks, regulators and government departments are critical.
Note that the Spectra Systems (LON:SPSC) line are US Regulation S restricted shares, which can't be held by US citizens, which goes back to the IPO I believe. They can be converted into Spectra Systems (LON:SPSY) which is more easily tradeable on request to the company. The last time I looked, back in June, there were only about half a million SPSC left in issue compared to over 45 million SPSY. Unless you have a very good reason the SPSY line is the one to buy due to liquidity.
timarr
Thank you Timarr.
Do you know who their main competitors would be please?
Regards
James
Hi James
Do you know who their main competitors would be please?
That's dependent on the exact sector - but if you're looking at banknote security features then the likes of G&D, Oberthur, De La Rue, Toppan can all supply them. It's a complex supply chain, and different players fit different parts of it some will produce the banknotes, some will provide security features, some will provide the authentication methods, etc, etc.
When you extend the range of solutions as Spectra Systems (LON:SPSY) have done into banknote cleaning, security features for other industries and even Internal Control Systems for lotteries it becomes more than usually impossible to analyse what the company is doing. On the plus side the contracts tend to be long, so there's a reasonable certainty of ongoing revenue.
Based on the financials they seem to be doing a good job, but I wouldn't want to waste my own time analysing any detail here. Way too complicated.
timarr
All set for strong growth over next five yrs. A good income stream will give the company plenty of scope for development. A strong management team in place, bodes well for the future.
Just found out that despite this being an AIM share I am unable to buy this through Barclays as it is apparently a US share!! I had a similar issue with Somero. Tried buying in my ISA and SIPP to no avail. Wanted to flag this up for anyone with Barclays thinking of buying and also to ask those with other brokers whether they have had this problem?
No problems buying on iWeb (Halifax)
No problems with HL.
No problem with AJBell which is interesting as Barclays use AJBell!
Able to buy it through HL.
Hi Jack,
Another excellent article for which many thanks.
One additional point worth noting is that broker forecasts for Spectra Systems (LON:SPSY) only ever incorporate the revenue and profits SPSY are very highly confident of achieving from existing contracts.
Any additional contracts won result in broker upgrades. SPSY is essentially a downgrade free zone.
HTH. Cheers, Martin
P.S. Spectra Systems (LON:SPSY) and Jarvis Securities (LON:JIM) are currently fighting it out for which is my second largest holding so hopefully I am not wearing rose-tinted glasses.
This is a core holding for me. I think it is probably one I feel most excited about. Bull points well covered:
> The broad range of applications for their technology, sticky revenues and integrated packages (including after service income) should underpin growth.
> I like the fact they are prudent in RNS announcements and cautious in way account for revenues. Cash flow statement is easy to understand.
Bear points (for me):
> Difficult to get "under the bonnet" with the company as they are protective about news flow and it has been a struggle to find out much beyond their website (and some investor events). Based in USA, AGM's not accessible etc. Under the radar??
> Key man risk, already mentioned.
> Customer risk. Majority of revenue from small number of clients (but definitely countered by strength of product offer and integration into customer operations). Also their customers are not going to go out of business (as central banks etc!)
I’m a happy Spectra Systems (LON:SPSY) holder. I think of it in a similar way to Bioventix (LON:BVXP) in a different sector. Exciting growth opportunities on top of stable well run existing businesses that pay dividends.
Both look to be driven by visionary scientists so there is some key man risk that comes with the opportunity.
If anyone knows of any other businesses with similar characteristics please do share.
I agree entirely John and both are top 10 holdings in my portfolio. Just my type of businesses - annuity like income streams, visionary owner/founder, set expectations conservatively and try to surprise to the upside. Cashflows in both are reinvested in R&D for future growth with surplus cash being returned as dividends. And of course, bullet proof balance sheets in both cases.
Cheers
Simon
There are some interesting comments here from 2014 which give background to the development of the Company. Some of the contracts are for very long periods - 20 years or more creating the beginnings of a decent moat.
Thank you for sharing this, it is much appreciated!
Thanks for your analysis of Spectra Systems Jack. I have held this share for just over a year so I will explain why I bought. Small technology companies which offer rapid growth prospects do not usually interest me because they often have high debts and weak financials. This not the case with Spectra, it even has a half decent ROCE. I also like small companies which genuinely address global markets as I have had previous success with these types of companies. I think you have pointed out the downsides, the main one being that revenues/profitability relies on very few customers so I am expecting a bumpy ride. The company also relies very heavily on its founder and president, Nabil Lawandy. Wouldn't this company make a brilliant acquisition for De la Rue?
Thanks for an excellent write up Jack. Spectra Systems (LON:SPSY) is my second largest holding, having held now for around 3 years. There are a couple of points I would add.
Aeris is a banknote cleaning product and development has been accelerated due to Covid - perhaps that has some connection with the biotech patent (or they could be unrelated). Either way, Aeris is another growth opportunity.
One thing that I really like about being a SPSY shareholder is that they have a habit of surprising to the upside. That’s because the broker forecasts only include contracted revenue and therefore, anything new or additional leads to exceeding expectations. So for example, earlier this year when they lost the Indian banknote tender at the last hurdle, I was happy to average down on the share price fall because I knew forecasts were unaffected and there were plenty more opportunities in the pipeline. Sure enough, SPSY beat expectations and increased the dividend by 30% when all around were suspending and cutting their dividends. So generally, I see SPSY as a low risk but exciting growth play, supported by a rock solid and growing dividend.
However, there are some risks. The main one for me is key man risk and when/how Nabil chooses to exit. My hope is that it will be a takeover at a healthy premium a few years’ down the track. There is also a bit of a corporate governance thing with AGMs consistently being postponed due to the lack of a quorum. The leap of faith is that Nabil will run the company in the interests of all shareholders and I believe he does, so I am happy to hang on to his coattails.
Thanks again for a great article.
Cheers
Simon
I have held both Spectra Systems (LON:SPSY) and Spectra Systems (LON:SPSC) for a few years. They seem to me to be worth holding long term just for the dividend yield, with the capital growth as a bonus.
I don't know who the individual large shareholders are, or whether there is potential for a bid. There certainly seems to be valuable IPR in Spectra.
... and Spectra Systems (LON:SPSC) offer is currently 2p below Spectra Systems (LON:SPSY) bid.
Hi FREng,
Just wondering what the difference is between the two classes of shares? Is it a similar position to Schroders (LON:SDR) and Schroders (LON:SDRC) ?
Hi Freng. Can I ask, what is the difference between (LON:SPSC) & (LON:SPSY). I notice they are both listed in the UK, however, there are a couple of comments here saying the share price is in USD, but appears to be in GBP. I'm confused. thanks
Looks interesting, but I don't think that I am alone in scarcely having touched a bank note during the last six months.
Yes, from a western perspective that may be the case but globally cash in circulation continues to go up apparently! Spectra seems to have cracked the ability to build protection into polymer notes, which has previously been difficult. This remains a growth market I believe