International SIF: Strategy update + three Euro stocks head for the exit

As promised a few weeks ago, this week I want to provide an update on my International SIF virtual portfolio.
I’m going to make some changes in response to reader feedback in August. Plus I’m going to review the five stocks that are up for eviction this month.
Strategy changes
After receiving a fantastic response from readers in August, this week I want to share with you a summary of your comments and the changes I’m planning.
Geographic changes: Most comments related to the folio’s geographic focus. There was a strong preference for US stocks, with Europe in second place. This is no surprise, as the US is generally the most popular foreign market for UK-based investors. The reasons for this are fairly obvious -- the US market is broad, deep, and very liquid. Company reporting is consistent and reliable and there’s no language barrier.
However, Stockopedia also has a number of subscribers who are based overseas in countries such as Australia and India, where local web services are more limited.
A number of readers suggested multiple regional portfolios. Although this would be interesting, I just don’t have time to do this at the moment. So I’ve come up with a compromise solution that will hopefully satisfy a majority of readers, without excluding anyone.
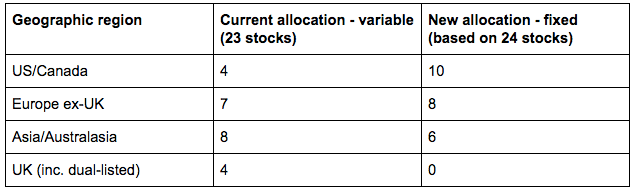
I’m going to change the geographic allocation of the folio so that it’s weighted more heavily to the most popular foreign markets. I’m also going to exclude all UK stocks, as there’s no point in duplicating the stocks I hold in the main UK SIF fund.
Here’s a comparison between the current allocations and my new fixed allocations. I’ll gradually migrate to the new allocations as stocks are bought and sold:
Costs, dividends and total return: A number of readers suggested I should include total return, not just price returns.
I’m a big fan of total return and include this in my UK stock write ups. However, tracking dividends on overseas stocks is a bit more complicated, in my experience. And transaction costs vary widely on foreign stocks.
For these reasons, I’m going to continue to ignore dividends and costs. I’ll focus on price return only for international stocks.
More detailed analysis: So far, my analysis of the foreign stocks chosen for the portfolio has been pretty limited. I’ve simply bought the top-ranked stocks that have qualified for my screen.
Your feedback suggested you’d like to see more in-depth analysis. Given the wide range of gains and losses seen so far, I think this makes sense. So I’ll be looking into new stocks in more depth from now on.
To allow for more detailed coverage, I’m going to change my schedule so that I add and remove shares in alternate months. September’s a selling month. In October I’ll buy three new stocks for the International SIF. This means my holding period will be increased to 10 months, but I don’t see this as a major issue for this virtual, experimental portfolio.
Portfolio changes for September
Last month I dropped one stock from the International SIF, but didn’t buy any new ones. This month I’m going to be adding and removing shares, while keeping my new target allocations in mind.
First of all, here’s a snapshot of how the portfolio looks at the time of writing:
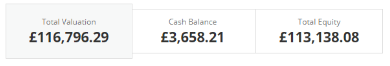
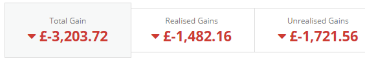
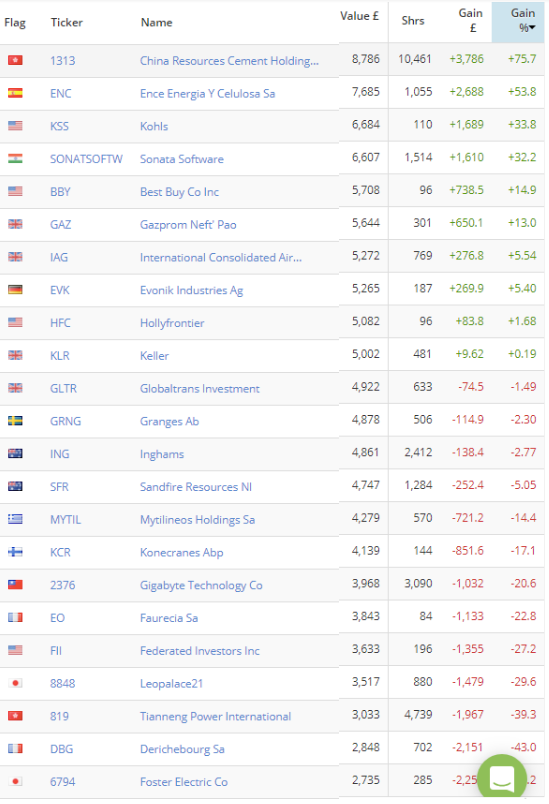
As you can see, performance continues to vary widely. Gains and losses on open position vary from +75% to -45%. I’m not entirely comfortable with such big drawdowns on open positions, so hopefully some extra analysis on new positions will help improve this outcome.
Heading for the exit
As with my main SIF folio, stocks are sold after a fixed holding period when they no longer qualify for the screen (my International SIF screen is here).
Here are the stocks that are up for eviction in September.
China Resources Cement Holdings: This £5.8bn Hong Kong-listed cement group continues to qualify for my screen. Performance to date has been quite volatile, but it remains the portfolio’s best performer to date.
Verdict: Hold
Return to date: +75c
Gazprom Neft’ Pao: Russia’s answer to BP continues to look cheap. But an ultra-low P/E of 4.1 and the stock’s UK listing mean it no longer qualifies for my revised rules.
Verdict: Sell
Price return: +13pc
Faurecia SA: This French maker of car seats and emissions control systems has fallen 22% since it joined the folio. Although broker forecasts have improved since I added the stock in December, the market seems to be losing confidence in the outlook for this firm.
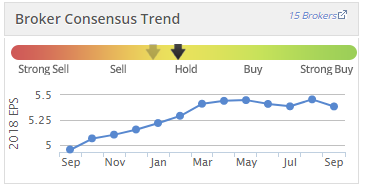
The shares look cheap on 9 times forecast earnings, but a negative relative strength reading means that it’s lagged the market over the last year. As a result, Faurecia no longer qualifies for my screen.
Verdict: Sell
Price return: -22pc
Konecranes ABP: This Finnish firm specialises in building heavy-lifting cranes. Like Faurecia, it’s fallen out of favour since December. I’m not sure why, although Konecranes appears to have issued quite a lot of shares over the last two years:
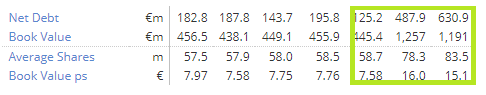
Given the increase in book value and net debt, I assume the group has made major acquisition(s). But it’s starting to look like 2017’s 10% operating margin was a one-off -- the TTM operating margin has now fallen back to its previous level of c.4%.
This stock no longer qualifies for my screen for three reasons:
Earnings yield is < 8>#/p###
Net debt > four times net profit
1-year relative strength is < 0
As a result, Konecranes joins this month’s exodus.
Verdict: Sell
Price return: -17pc
Sandfire Resources NL: This Australian copper, gold and silver miner has slipped 5% lower during its time in the folio. However, I don’t think that’s a bad result given recent falls of c.10% in the price of gold and copper.
Broker forecasts have also slipped and are now slightly lower than they were when I added the stock last December:
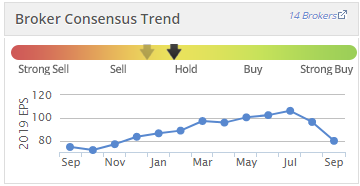
However, the black arrow and its shadow on the coloured bar above indicate that broker sentiment is improving. I remain positive too.
The group’s results for the year to June are already in the system and show that net cash rose from AUD125m to AUD241m last year. Earnings per share rose by 57% and the group’s return on capital employed rose from 22% to 29%.
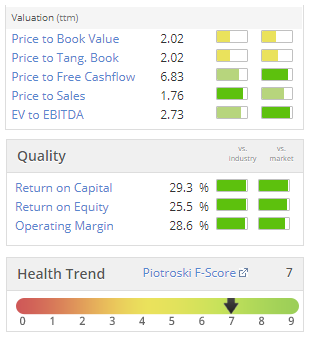
There’s a lot to like here, in my view.
Despite such strong quality credentials, the stock still looks affordable:
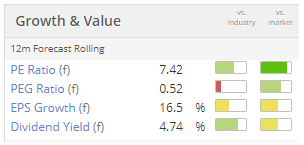
Unsurprisingly, Stockopedia’s computers also like Sandfire. They’ve awarded the shares Super Stock status and a StockRank of 91.
Happily, this stock continues to pass all of my screening tests, so will remain in the folio until the next review.
Verdict: Hold
Price return to date: -5pc
Summing up
After the changes I’ve listed above and those I made last month, the International SIF is down to 20 stocks and is showing a 2.6% loss to date.
In October, I’ll aim to add three new stocks that will continue the folio’s shift to my new target geographic allocations.
As always, your thoughts on these changes would be very much appreciated.
Next month, I’ll get back to the main UK SIF fund with my usual monthly review.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

8 comments
Roland
Thank you as always for a very interesting article.
May I ask on this forum whether you have considered a purchase of Gazprom Neft Pao for your UK portfolio. As you say the stock still looks cheap and it has performed relatively well on your international portfolio.
I would be very interested in your answer.
Regards
BB
Hi BB,
I've experimented with owning Russian stocks in my UK portfolio before and after mixed results (https://www.stockopedia.com/content/sif-portfolio-october-review-air-flo-hydr-and-tcs-232558/) I decided not to buy anymore.
These firms almost always appear cheap, but I fear that political interference and vested interests mean that the Russian market doesn't operate in quite the same way as western stock markets.
As this is something I just don't understand, I no longer buy these shares.
Regards,
Roland
Roland,
What do you think is going wrong with Derichebourg
It has attractive multiples, strong ROCE, increasing sales, improving margins, decent covered divi resulting in good Quality and Value metrics
Yet momentum and hence shareprice continues down
I don't really know what's gone wrong (if anything) at Derichebourg.
A number of the International SIF's European stocks seem to have been big fallers without any financial deterioration. Perhaps these markets are taking a more cautious view of the future than UK/US markets? I hope to see some recovery by the time I have to consider disposing of this stock!
Regards,
Roland
The big move back in May was because Derichebourg disappointed on margins at the half year, leading to a suspicion that they'd overpaid for non-earnings enhancing acquisitions, and a potential deteroriation in earnings growth. As we've seen over the last six months in the UK, companies that disappoint even mildly tend to get hammered.
timarr
Hi timarr,
Many thanks for this extra info on Derichebourg. It sounds like outsourcing/support service companies in France may be suffering from similar problems to those which have plagued their UK peers...
Hopefully things won't get worse. A 40%+ drop still seems severe given the TTM ROCE of almost 17%.
Cheers,
Roland
I have some european shares, I will say that last year was a good year but this year has been difficult in europe, I would say they have underperformed the UK which is rather surprising, there have been some big pullbacks on high ranked Stockopedia shares for no apparent reason. This is born out if you look at the screens such as CAMSLIM and Jim Slater Zulu. The problem with euro shares is the lack of information, often you just get a couple of lines at quarterly results. Maybe Brexit is affecting the markets over there.
Thanks for that, I haven't researched Deriche in depth, it just popped up as a good looking stock in screening.
Having said that it has bounced dramatically since my post a few days ago. Up 10% since then. Seems there is value there.