Mark Slater's presentation at the Mello Bloomberg Event on 12th March 2015

I attended the Mello Bloomberg investor event last night and what a good event it was; some excellent speakers and “refreshments" afterwards in Bloomberg's high tech office in Finsbury Square.
The first speaker was Mark Slater, the manager of the Slater Growth Fund, who has a superb record over the near 10 years since launch of the Fund in March 2005. It is up some 280% v around 120% for its benchmark, the IMA UK All Companies Sector.
Cumulative performance to 31st January 2015:
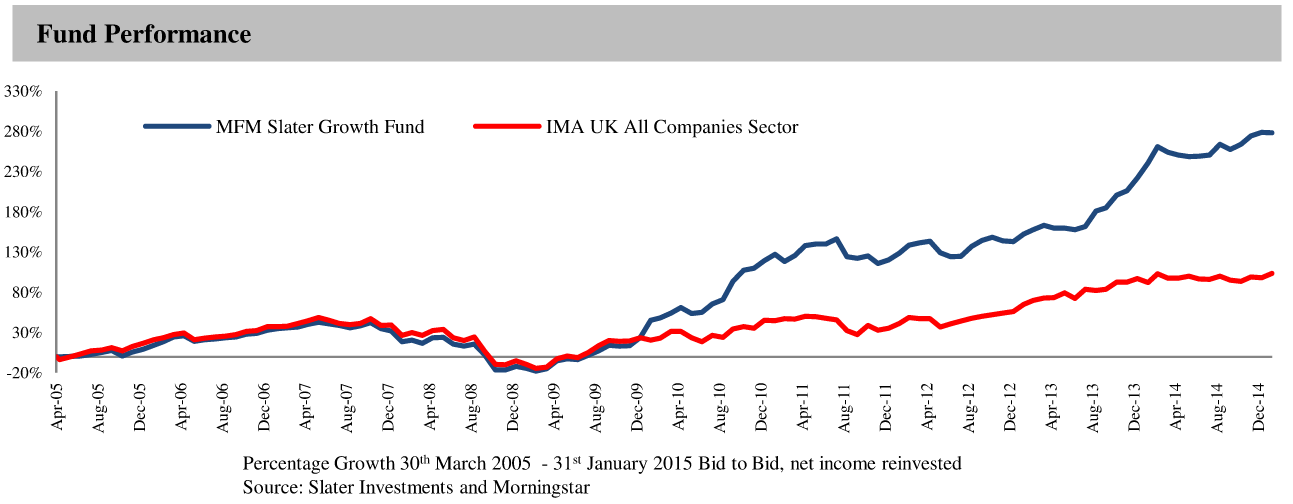
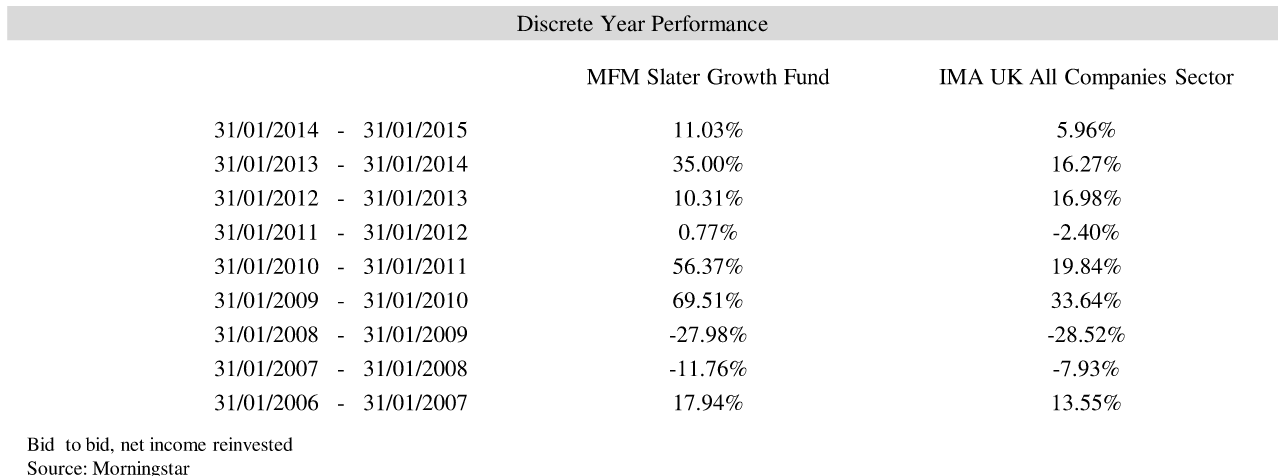
The Slater Growth Fund is one of those that I benchmark myself against; if I can't beat him I might as well give up and invest in his fund. I often have a glance at his Portfolio to find ideas to follow up. Since launching the JIC Portfolio in 2012 it was up some 89% over the three years to 31st January compared to 65% for the Slater Growth Fund; I need to keep that performance going! He described his investment approach and made some excellent observations, notably that he believed private investors had a distinct advantage over institutional fund managers; private investors can move more quickly and are also able to run more concentrated portfolios. He said that if he was managing a private portfolio “personally there was a strong argument for having only 5-10 holdings!"
What Slater looks for in an investment:- Low PE relative to growth; unashamedly he is a GARP man thinking that pigeonholing oneself in either Value or Growth is fine but not for him. Ideal company might be on about 15x forecast earnings and a PEG Ratio (PE Ratio/earnings growth) of 1.0 (i.e. 15% earnings growth).
- Strong cash flow; it's all very well looking at earnings per share but they can be, and often are, manipulated. Cash flow per share is the real measure of the strength of a company. It's okay if a growing company has a short period of poor cash flow providing it is investing for growth but he would want to understand why and expect it to be positive over 5 years. Free cash flow is very important; it's what pays the dividends.
- Positive recent trading statement; he likes investing in companies that are doing well now; I liked that as all too often investors, me included, are blinded by the excitement of the upside if such and such a company achieves success in two years' time; so called “blue sky" companies. Investors invariably pay far too much for the “potential" which is rarely delivered.
- High Return on Capital Employed and margins. It says something about the quality of the company and its potential to keep on delivering growth for shareholders.
- Rising sales per share; too many companies are easily seduced into issuing new shares to fund acquisitions or growth, by investment bankers greedy for fees. Sales per share growth demonstrates that you have found a company where management is really growing the company organically and adding value.
- Directors dealings; it's good to see directors buying shares in their own company
- He likes “clonable" businesses; Dominos Pizza is a classic example where it has been able to open more and more franchised stores at little capital outlay thus driving increasing cash flow and returns. Tremendous operational gearing in the company from new openings.
- He doesn't like IPO's; the odds are stacked against you! He showed a compelling chart showing the poor performance of IPO's over time. They are invariably overpriced and the people who are selling the company know more about it than you. When you buy shares in an existing listed company there is every chance that you know as much, if not more than the person who is selling! The same chart showed that the longer the listed life of the company the better performance has been. He likes “a company to have a bit of history".
- Keep it simple. Simple businesses; if too complicated don't go near it.
- Einstein's 8th wonder of the world: Compounding; those who understand it receive it, those who don't pay it!
- T-Rowe Price; cardinal sin is treating a really exceptional holding like the rest of them!
- Don't buy hope!
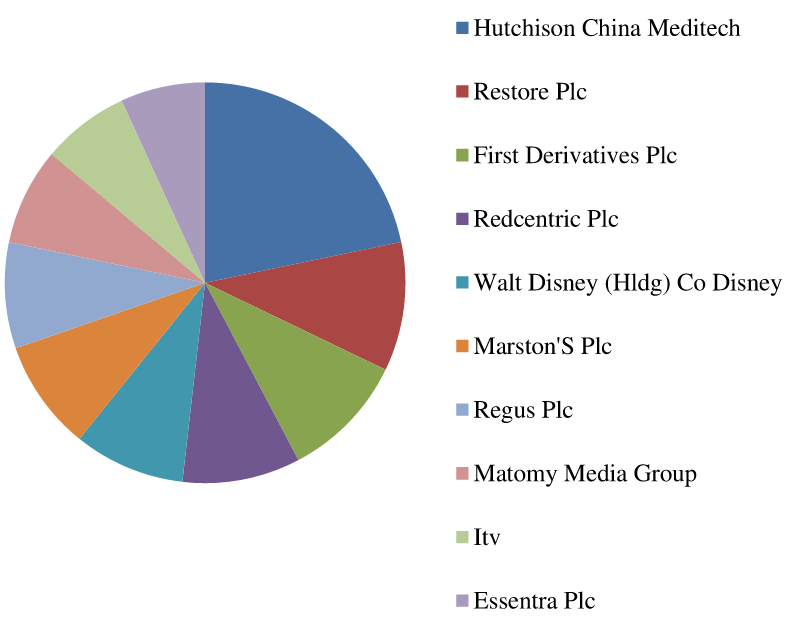
He finished by talking about three stocks which he is currently keen on:
Hutchison China Meditech; it has been a great performer on the back of its exposure to growing health care spend in China which he expects to continue. In addition it has a potential pipeline of new drugs, whose development is being funded by big pharmaceutical companies, which he thinks could add $3-5bn on to the current valuation of HCM of around $1bn. Chinese companies listed on AIM do not have a great reputation or record but in this case there is a degree of comfort from it being a subsidiary of Hong Kong based Hutchison Whampoa, which has a long history of looking after its minorities.
The other two companies mentioned were Dotdigital and First Derivatives. Dotdigital is an example of a company that is currently taking a growth pause as it invests to grow its business internationally. He expects a huge payoff from this investment from mid 2016 onwards. First Derivatives is a relatively recent acquisition; the company provides software and consulting services to the investment bank market, the derivatives technology industry, the foreign exchange market and the provision of technology sales services to the information technology sector. Slater believes it is currently in a “sweet spot".
Conclusion: A highly entertaining talk with some great insights. I will follow up on some of the investments mentioned and check the JIC Portfolio against the list above; I know there are a few stocks that would fail!
To go to the Slater Investments Website click HERE
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
11 comments
Thank you for an excellent write up for those of us unable to attend.
I attended this event and was the person who asked Mark about selling a stock and at what point he thought a stock was overvalued. I didn't really get a quantified (P/E or PEG) answer which didn't overly surprise me as there are many factors that can effect perceived value.
That said I struggle to see why Mark still holds HCM, as jjis has already said HCM is on a forecast P/E of 66. There isn't a ton of cash on the balance sheet to bring this number down, so the fundamentals don't really match the principles that I heard Mark discussing last Thursday.
There is the drug pipeline but if that doesn't work out as planned I could see the shares falling heavily.
Regarding HCM being pricey and Slater tipping ... here's a story that could be of interest...
I remember back at a Master Investor 2011 a few years ago... Slater mentioned Cape PLC as his primary tip - I wrote up his presentation in this article at the time. But it turned out that Slater Investments were in the middle of aggressively selling their Cape position. A few days before the April 2011 Show Slater Investments announced he'd reduced to just under 4% ownership.... so it's not like he hadn't shown his hand...
But even after he'd tipped the stock in his speech he kept selling it aggressively all month, reducing to less than 3% ownership by May - just 3 weeks after the show.
It proved to be very good timing as the top price in Cape plc was barely 10% higher than their selling price - but there must have been plenty of private investors who caught the other side. I'm not sure if he still holds it but I'd imagine that some of the audience from that day still do. http://www.stockopedia.com/share-prices/cape-LON:CIU
The point I'm making is that you shouldn't necessarily trust what fund manager's say in public.... sometimes they can be extremely canny at marketing their book.
It's much better to look at what fund managers have been buying than what they've owned for some time. Whenever we do ship the Stockopedia "Smart money" add-on it will become much, much clearer. (Yes I know, long overdue).
Ed
Very informative piece. And I think very useful too.
To summarise, we should follow fund manager's actions. And ignore what they say.
Thanks.
Further to my last comment... I just checked and Slater Investment have been reducing their position all the way up in Hutchison. I'm sure this is probably to do with portfolio risk management... but they reduced below 6% in 2013 and then below 5% late last year.
I wouldn't be surprised if we get another announcement he's been offloading.... especially given that the biggest sale in the last 2 years he's made was the $10m worth of HCM he dumped last September...
If you want to know what Slater's been buying in recent months... here's a rundown of his biggest purchases year to date:
Networkers International is a StockRank 98 stock... so I might take a closer look. The others don't meet my criteria.
Slater has definitely been buying the other 2 stocks mentioned DotDigital (last December, new position in big size) and First Derivatives last summer.
DYOR !
Nice work Ed - Was this info obtained using the Stockopedia "Smart money" add-on (beta testing version) ? If so then its looks very informative.
"Do as I do, not as I say" is a truism in investing as far as I am concerned.
Ed, I'm sure you're right and I fully expect further RNS disclosing reduced holdings for Hutchison China MediTech (LON:HCM). I don't know his initial entry price, but known he has held for years (although I think I beat him to it having been a very long term holder).
I don't have the numbers, but suspect one of the main drivers of the fund outperformance is due to its investment in Hutchison China MediTech (LON:HCM). If the share price continues to forge ahead, he'll need to keep reducing, to ensure he's balanced and not too overweight in a single stock.
Re: HCM being a Chinese company on AIM, I know where Paul is coming from. However, Hutchison China MediTech (LON:HCM) is not some opaque operation run from a back room inShanghai; its a large company with a renowned BOD. The CEO Christian Hogg is well respected and 'tangible' and its majority shareholder as about as gilt-edged in China as you can get.
Yes the pe is crazy so it's not a value investment. But if just one or two of the TCM sourced compounds come good then this company has massive potential. Of course any failure will be punished. Personally I would look to add on such weakness; it's inevitable that several drugs will fail in the portfoilo.
The great thing is that Matchtech must have a subscription to Stockopedia as they saw the value and quality in Networkers International and bid for it at the end of January. Matchtech itself looks good to me on StockRank of 93 (Quality 83, Value 82). Been buying recently after decent trading statement and new contract wins.
Thanks for the write up John, very useful and lots of common sense stuff in there.
Nevertheless on HCM 300x or perhaps 70x PE with ZERO yield is a bit rich for my tastes and certainly very expensive for a Chinese stock!
Thanks Paul. I think his point about Hutchison Whampoa was important. He reckons HCM is properly audited and that the accounts can be trusted and that HW has a long history of making sure minorities are properly treated. HW holds 69% through Hutchison Healthcare Holdings.
Thanks John, I really appreciate the write-up, as I wasn't able to attend in person after all. I really respect & admire Mark Slater, and his father of course. He's always full of insights. Though the China stock would worry the hell out of me in his shoes, but he's obviously done his research.
Regards, Paul.