SIF December review: Ahead of the market, but facing big losses (COST, SXS, MOTR)

Happy New Year! I hope you all enjoyed a good break over the festive period. Let’s hope that 2019 will be kinder to our portfolios than 2018.
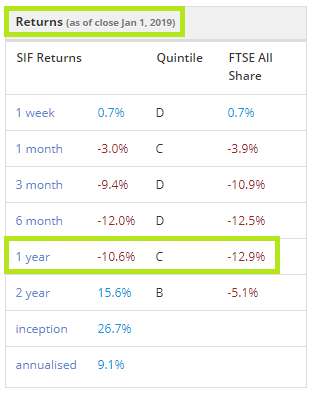
December capped a bad year for the SIF fund, but happily my rules-based portfolio still managed to finish ahead of the FTSE All-Share index by a modest 1.3%:
My view remains that a number of decent stocks have been oversold as investors have taken fright at a multitude of potential risks. These include the prospect of a chaotic no-deal Brexit, US-China trade war, and rising interest rates.
It remains to be seen whether these fears are fully justified. But the forward-looking nature of markets could mean that stock market sentiment improves while newspaper headlines remain full of doom.
Getting back to business
I’m not going to make any more predictions, but I will continue with my strategy of buying stocks which qualify for my Stock in Focus (SIF) Screen, and selling those which don’t.
As a reminder for new readers, my SIF fund is a virtual fund I run through Stockopedia’s Fantasy Funds system. In order to have skin in the game and make this more interesting, I also invest a portion of my own personal portfolio in all of the stocks I add to the SIF fund.
At the end of each month, I review stocks that have been in the folio for at least nine months to see if they still pass my screening rules. If they don’t, they’re sold.
This slightly belated review is for December 2018 and will include three stocks:
Used car supermarket Motorpoint (LON:MOTR)
Engineering and construction group Costain (LON:COST)
FTSE 250 instrumentation and control specialist Spectris (LON:SXS)
Motorpoint is the fund’s oldest holding, having been purchased in December 2017. Costain and Spectris were purchased in March 2018 and have delivered some of my biggest losses to date:
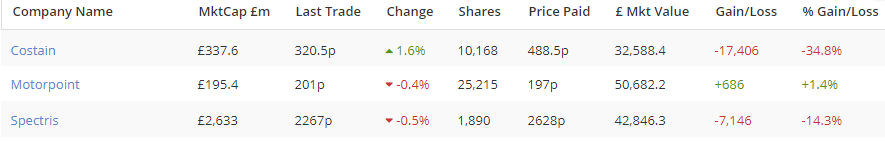
(As at 2 January 2019)
Let’s take a closer look.
Motorpoint (LON:MOTR)
My respect for this car supermarket business has increased during the time that I’ve owned the shares. It appears to be able to generate a very high return on capital employed (ROCE) without excessive use of debt.
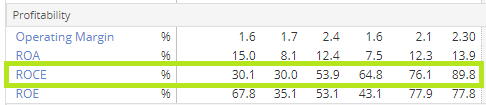
By focusing only on nearly-new cars, the business avoids direct exposure to new car sales. And fairly rapid stock turnover should mean that if used car prices fall, the firm’s exposure to this will be limited as it will soon be buying at lower prices too.
My main concern is that this impressive performance relies on continued sales growth. The operational gearing displayed by this business is very high, as I discussed last month. High operational gearing means that when sales rise, profits rise more quickly. Unfortunately, the opposite is usually true as well. I suspect that a small fall in Motorpoint’s sales would result in a much larger drop in profits.
Although the potential for a slowdown concerns me, a lot of the froth has come off Motorpoint’s valuation over the last year. The shares look reasonable value to me on 10 times forecast earnings, with a rolling forecast yield of 3.9%.
Motorpoint continues to pass all of my screening tests, so it will remain in the SIF folio for at least one more month.
Verdict: Hold
Total return to date: +4.8%
Costain (LON:COST)
The building sector has been hit hard in recent months by fears of a UK economic slowdown. These concerns became more tangible recently when Kier Group unexpectedly announced a £264m rights issue. The company said that one reason for the fundraising was that lenders were becoming more reluctant to offer credit to construction firms.
Costain shareholders shouldn’t have to worry about debt or dilution, as their firm has a stronger balance sheet and has consistently reported net cash in recent years. I also believe that Costain is generally a higher quality business.
A focus on infrastructure and technology has helped the firm to generate an average return on capital employed (ROCE) of 20% over the last six years, according to Stockopedia. The equivalent figure for Kier is just 5.1%.
Although analysts’ forecasts for the stock have remained unchanged, Costain shares have fallen by 24% since the start of September.
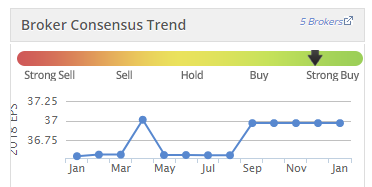
The shares now trade on about 8 times forward earnings with a 5% yield. I think this could be an attractive valuation, but my SIF rules don’t agree. Slower earnings growth forecasts for 2019 and a share price that’s lagged the market means that Costain no longer passes all of my screening rules.
I’ll sell the shares from the SIF fund and from my own portfolio after this article has been published.
Verdict: Sell
Total return: -31.5%
Spectris (LON:SXS)
Like Costain, Spectris has performed poorly during its time in the portfolio. I think this is more an accident of timing than anything else. Ths stock chart suggests to me that the shares may now be establishing a new uptrend:
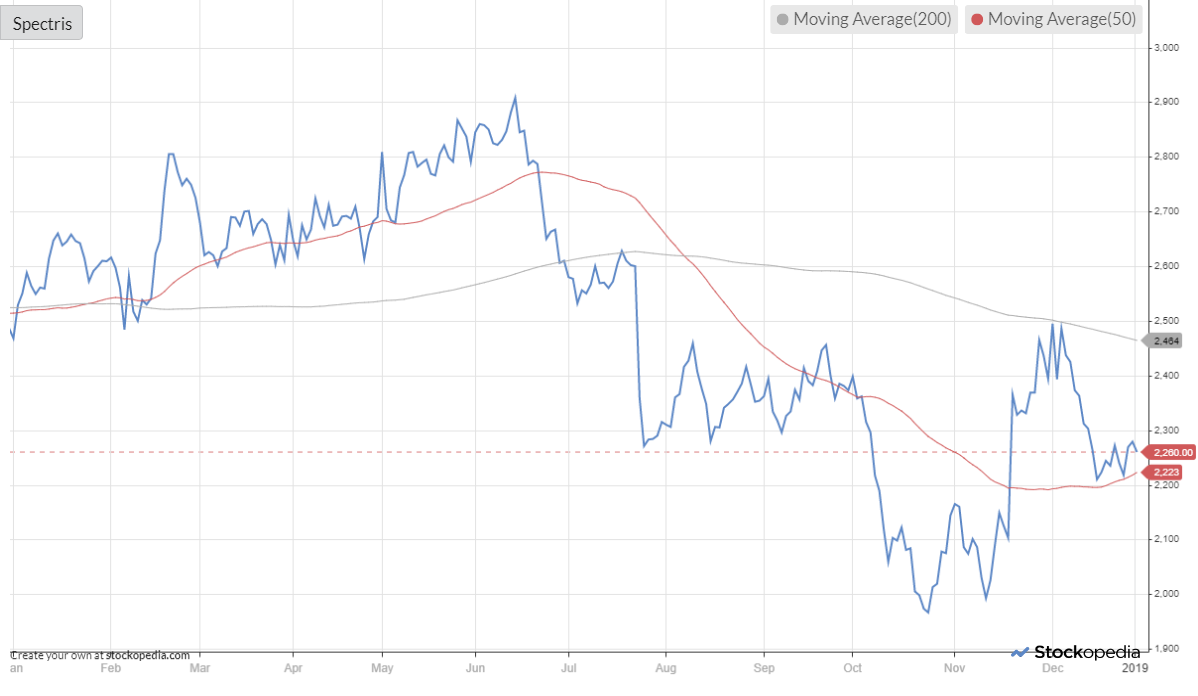
Operational performance certain seems okay. The firm’s most recent trading update showed like-for-like sales growth of 8%, an improvement on +5% LFL during the first half of the year. Profit margins in H1 were broadly unchanged.
One point of interest is that the firm’s profits appear to be weighted towards the second half of the year. About 30% of adjusted operating profit was generated during the first half of 2017. The group’s 2018 results suggest a similar performance is likely.
This means we won’t get a clear idea of profitability until Spectris publishes final results in February. I don’t see any obvious cause for concern in this case, but this seasonal bias is worth remembering when considering the numbers.
Unfortunately, Spectris’s interim results also revealed a sharp rise in net debt, which rose from £50.3m to £231.5m. Although this was due in part to the acquisition of Concept Life Sciences, cash generation also deteriorated. Both factors contributed to a fall in the stock’s Piotroski F-Score (fundamental health) score, which dropped to just 4/9. This is below my screening threshold of six.
Earnings growth is also expected to slow this year, which has caused the stock’s PEG ratio to rise above my maximum of 1.2.
As a result, Spectris no longer passes all of my screening tests and will be sold at a loss later this week.
Verdict: Sell
Total return: -11.6%
Next week
There aren’t many shares qualifying for my SIF screen at the moment. But I hope to be able to find an attractively priced new stock to consider for the portfolio next week.
Interestingly, figures released by department store group John Lewis on Wednesday showed a 4.2% year-on-year increase in sales during the week before Christmas. So perhaps the news from the firm’s listed rivals won’t be as bad as feared. I might even be able to snap up a bargain retailer for the SIF fund.
Disclosure: Roland owns shares of Motorpoint, Costain and Spectris.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?