SIF portfolio: New stock Motorpoint makes me uncomfortable

After a round of profit taking last week, I’m heading to the shops this week. Cyber Weekend may be over, but the SIF screen has come up with a retailer to consider adding to my SIF fantasy fund.
Sharp-eyed readers will note that used car group Motorpoint isn’t the highest-ranked qualifying stock in my screen results.
However, H&T, Redrow and Harvey Nash were ruled out as they’re already in the portfolio. Robert Walters was disqualified as it’s a recruiter, like Harvey Nash.
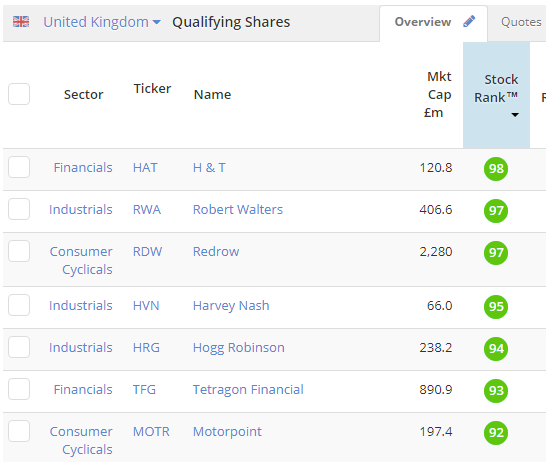
Hogg Robinson is a previous portfolio stock and has a giant pension deficit. Although such deficits have been falling recently due to higher bond yields, I’m going to maintain my self-imposed ban on super-size deficit companies for a little longer.
This brings me down to Jersey-based investment company Tetragon Financial. I decided to rule this stock out as the portfolio already has an asset manager, Standard Life Aberdeen.
Thus my choice for this week is Motorpoint. This is undeniably a cyclical business that’s heavily exposed to the UK economy. So I see some risk of overlap with stocks such as Redrow, even though it doesn’t have any direct sector peers in the portfolio.
I’m not comfortable with this
On a personal level, I’m not comfortable with the idea of adding a car retailer to the portfolio. Recent figures from automotive trade body, the SMMT, suggest that the new car market has peaked. Is now really a good time to invest in a car retailer?
What could go wrong? The risk of falling used car values and stale stock is obvious. An increase in finance costs could also threaten profits.
This could work: I suppose you could argue that Motorpoint’s focus on used cars under three years old might be countercyclical for a while. Some new car buyers might trade down to a nearly-new car next time round. Or perhaps fund manager Neil Woodford’s contrarian bet on the UK economy will be vindicated, and the car market will remain relatively healthy.
There’s a lot of uncertainty, to my mind. But fortunately I don’t have to base my investment decisions on an uncertain macro view. As SIF is a rules-based portfolio, I just need to follow the rules and assess the numbers.
Strong H1 triggers £10m buyback
Motorpoint shares have put on a spurt and climbed 28% in the last month. Graham Neary covered the firm’s recent H1 results in more depth, but the short version is that sales were up by 18%, while underlying pre-tax profit rose 64%. A £10m share buyback programme is now planned to take advantage of what management describes as a “robust balance sheet position”.
Chief executive Mark Carpenter’s view is that while the market is subject to “external changes”, stock supply “remains good” and management are “comfortable” with H2 trading performance so far.
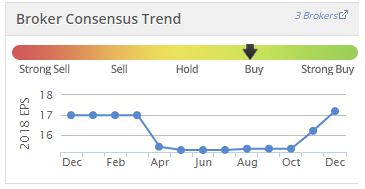
City analysts seem pretty comfortable, too. Broker forecasts have risen sharply over the last three months:
A combination of modest valuation, high quality and strong momentum mean that Stockopedia’s algorithms are also keen on this stock. This car retailer currently boasts a StockRank of 92:
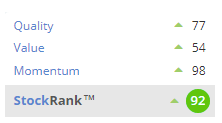
On the face of it, this is an affordable, good and improving business. So are there any hidden nasties?
A hidden bargain?
With a ValueRank of 54, value isn’t Motorpoint’s strongest factor. But most of the stock’s value ratios are much more attractive than this score suggests:
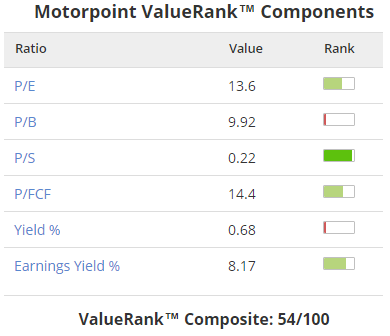
As you can see, a strong set of figures is being dragged down by a high price/book ratio and a low yield. In my view, these don’t need to concern us too much, with one possible exception.
Price/book ratio: The group’s main asset is its stock, most of which is funded by short-term finance (shown under current liabilities on the balance sheet). The value of these assets and liabilities largely cancel each other out, hence the low book value. I don’t see this as a concern. In my view, the stock’s valuation should be based on earnings and cash flow, both of which look healthy.
However, I would point out that in the event of a recession, the group’s lease obligations could become burdensome. A recent RNS noted that leases on three of the firm’s 12 sites (Derby, Burnley and Birmingham) have been extended to between 2028 and 2037.
Interestingly, all three sites are owned by a related party who is also a major shareholder. Another site (Oldbury) was sold in a sale-and-leaseback deal last year, and is now subject to a 15-year lease.
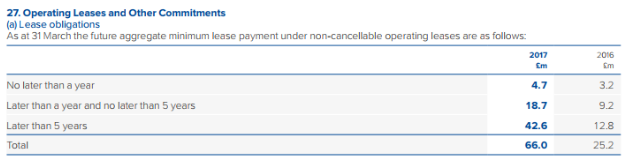
I’m not sure if such long leases are typical for this kind of business, but if Motorpoint ever wanted to close any of these sites these leases could become costly. The scale of these liabilities also seems to have increased. Last year’s annual report shows total lease obligations of £66m, up from just £25.2m prior to flotation in 2016.
Yield: Motorpoint’s trailing dividend yield is low because it only floated mid-way through 2016. So last year’s dividend was a pro-rata payout. This year’s interim payout of 2p is already 50% more than last year’s dividend of 1.33p per share.
Cyclical quality
Moving on, one of Motorpoint’s undoubted strengths is its ability to generate a very high return on capital employed. Coupled with a high Piotroski Fundamental Health score of 8, this gives the stock a strong quality score:
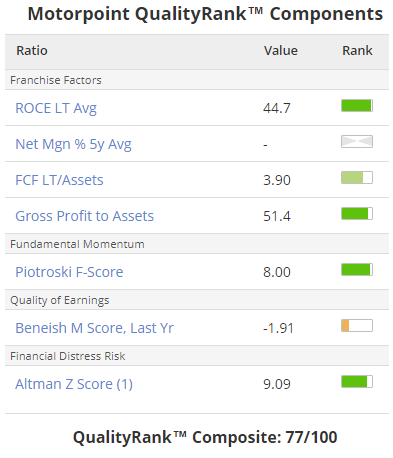
The company’s trailing twelve month ROCE is a staggering 86%. The secret to this is that the group operates with very few assets. So in that sense it’s an impressive business, able to leverage relative small amounts of capital to generate attractive returns.
On the other hand, this is a cyclical business with a slim operating margin of 2.1%. I suspect these profits are heavily dependent on strong residual values, finance commissions, fast turnover of stock and profitable extras like warranties.
Looked at another way, I estimate that if Motorpoint’s sales fell by 1% while its costs remained flat, the group’s operating profit would fall by about 45%.
My conclusion is that this is likely to be a high quality stock only during upcycles. In my view, this suggests that the stock’s relatively modest forecast P/E of 11 is may be high enough.
Sparkling momentum
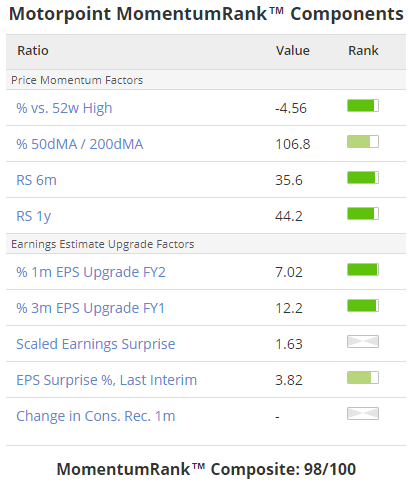
Motorpoint has a MomentumRank of 98. As you’d expect, I really can’t find any faults here on a medium-term timescale. The recent improvement in earnings forecasts is particularly appealing:
One short-term factor which some investors might want to consider is that after recent gains, the shares are looking a little overbought on the RSI index: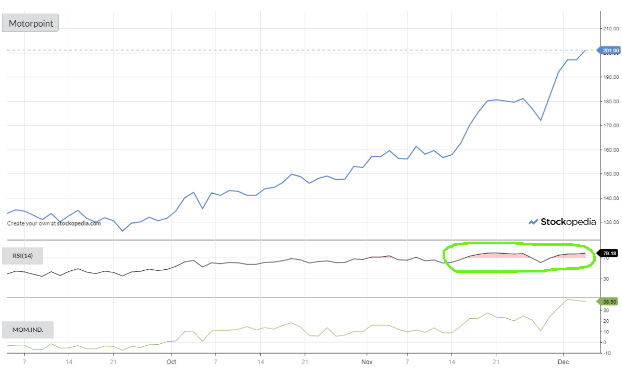
Overbought RSI suggests that there’s a chance the stock may pull back a little over the next few weeks, providing a more attractive entry point.
My verdict
If SIF was a discretionary portfolio, I wouldn’t buy this stock. But this is a rules-based fund. When I’ve used my veto in the past, I’ve usually missed out as a result. After all, it’s quite possible that trading will remain strong, providing attractive returns.
I will add Motorpoint to the SIF portfolio this week. But only with some misgivings.
Disclosure: Roland owns shares of H&T, Redrow, Standard Life Aberdeen and Harvey Nash.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

2 comments
Speaking to someone recently at a business in the south-east with what appears to be a similar model, they sell ex-lease cars at competitive prices, wafer-thin margins and with fast turnaround. Most of the profit comes from selling the finance deals, which is great when you go in as a cash buyer. I assume that MOTR is similar. I took a small stake in MOTR recently as I see this as a disruptive and growing model in the used car market, the risk as it appears to me is that if new-car lease deals decline, then that would adversely affect the supply 2-3 years down the line.
Hi whitmad,
That's interesting, thanks for your comment. I'm not sure how to predict what will happen to the used car market is new sales slow. I'd guess that it might depend on the state of the wider economy.
Regards,
Roland