SIF Portfolio: Should I revisit one of last year's success stories?

I’ve not yet bought the same stock twice for the SIF portfolio, but in this rules-based scenario there’s no reason not to. A number of stocks have popped in and out of my stock screen over the last year, and it’s just happened again.
FTSE 100 defence group BAE Systems joined the portfolio in June 2016. It was sold for a total return of 23% in December. Since then, BAE has issued a decent set of results and the stock has seen some mixed price action. The overall effect is that the shares now qualify for the SIF screen once more.
This week I’m going to consider whether to add BAE back into the portfolio. I’ll also take a look at a couple of more highly-ranked stocks I’ve rejected and discuss the thorny issue of pension deficits, on which my view is changing.
The also rans
My interest in BAE Systems is partly down to the defensive and diversification benefits I hope it might bring to the portfolio. But my screen results are always sorted by StockRank and BAE’s score of 78 means that it’s near the bottom.
Many of the higher-ranked stocks are already in the portfolio, or are duplicates. For example, recently-floated brick makers Forterra and Ibstock don’t appeal when I already have housebuilder Redrow in the portfolio.
I was tempted by gold miner Acacia Mining, which looks affordable and well financed. However, Acacia operates in Tanzania, where there is currently a ban in place on exports of gold/copper concentrate. This means that production accounting for 30% of the group’s revenue (c.$1m/day) is being stockpiled with no apparent route to sale. This ongoing problem puts the stock into the special situation category for me, so it’s not an investment for the SIF Portfolio.
Pension problems
Before I look at the latest Stockopedia figures for BAE, I’m going to approach the subject of pension deficits. Previously, I’ve tended to assume that rising interest rates and financial engineering would prevent them from becoming critical issues for most firms.
That’s why I was happy to add Hogg Robinson and Norcros to the portfolio last year. Both companies have big pension deficits, but excluding these they look like classic value buys. However, these stocks were among the worst performers in the portfolio last year. And unlike most of the other weak performers, things haven’t improved since.
This experience has made me think more carefully about the risks big pension deficits pose to smaller companies. Hogg Robinson’s deficit rose from £258.3m to £413.2m during the six months to 30 September. That leaves the group with a funding shortfall nearly double its £229m market cap, and more than 10 times 2016 operating profit.
If bond yields don’t rise and wipe out some of this deficit, Hogg Robinson could end up being run to provide cash flow for its pension fund. If this happened, I’d expect the firm’s stock to lose most of its value.
This worst-case scenario may well be avoided. But there’s no way to know how thing will turn out. So from now on I’m going to be classing companies with oversized deficits as special situations. Like Acacia, they’ll be ruled out of the portfolio.
Doesn’t that rule out BAE?
I’m comfortable taking a more lenient approach with big companies, as I believe their capacity for financial engineering and low-cost borrowing means that deficits are less likely to become critical.
In the case of BAE, while its £6.1bn deficit is high, it’s still less than one-third of its market cap. I believe the firm will be able to service this deficit without destroying shareholder value.
What’s changed since last year?
A blow-by-blow review of BAE’s finances would probably be pretty repetitive. You can see what I thought about the firm’s operations last year here.
What I thought might be more useful today is a review of what’s changed since BAE joined the portfolio in June 2016. The first things that’s interesting is that while BAE’s StockRanks have improved, the group’s profile as a quality-momentum play -- or high flyer -- is unchanged:
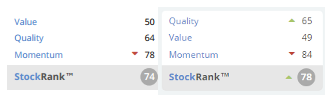
June 2016 (l) vs. April 2017 (r)
ValueRank: BAE’s looks slightly more expensive than it did 10 months ago. The P/E and P/S ratios have risen, while earnings and dividend yields have fallen. On the other hand, free cash flow has improved:
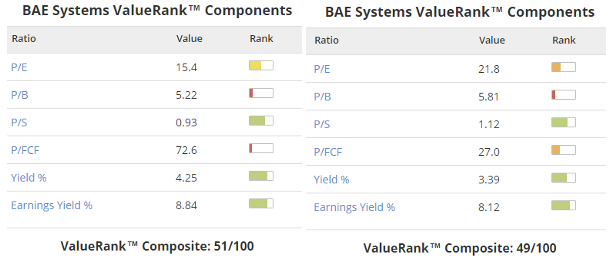
June 2016 (l) vs. April 2017 (r)
In my view, the main valuation risk is that currency gains seen last year will reverse sharply. BAE shares have risen by 28% over the last year, but the group’s 2016 underlying earnings of 40.3p were only 7% higher than in 2015. And this figure includes currency benefits worth 1.9p per share, according to BAE.
As with pension bond yields, I’ve no idea what exchange rates will do next. So on the basis that BAE’s earnings yield and dividend remain attractive, I’m prepared to accept the currency risk.
QualityRank: BAE’s QualityRank is almost unchanged from June last year:
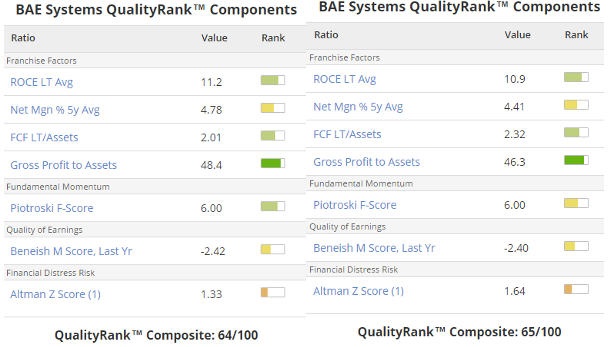
June 2016 (l) vs. April 2017 (r)
BAE’s quality performance was pretty stable last year, but it’s probably fair to say that there was a slight degradation in profitability, as measured by the four franchise factors.
Interestingly, this hasn’t pushed down the stock’s QualityRank, which is one point higher than in June 2016.
Indeed, it’s worth noting that the QualityRank is 33 points higher than it was 30 days ago. This appears to be because the Piotroski F-Score has increased from 5 to 6 during that time. I’m not sure why this has changed. As BAE’s results were published in February, the firm’s figures shouldn’t have changed since then.
MomentumRank: Momentum remains BAE’s strongest factor. There’s been a marginal improvement in a number of areas over the last 10 months:
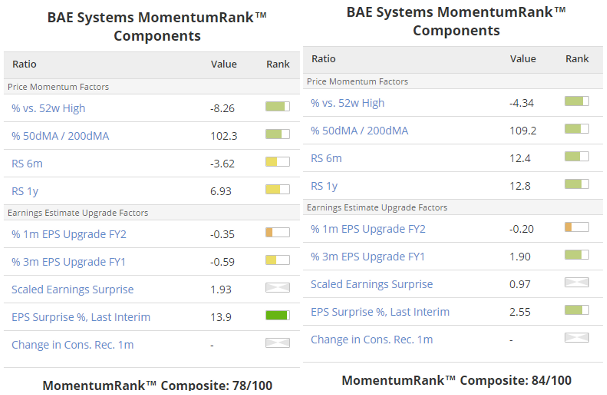
June 2016 (l) vs. April 2017 (r)
Earnings momentum appears healthy. Although the latest figures didn’t beat expectations by much, it looks as though broker forecasts were upgraded significantly after February’s results (the 3m EPS upgrade FY1 field).
Price momentum factors also seems strong and have improved over the last 10 months. Converting this into a picture gives the following chart, which looks encouraging to me:
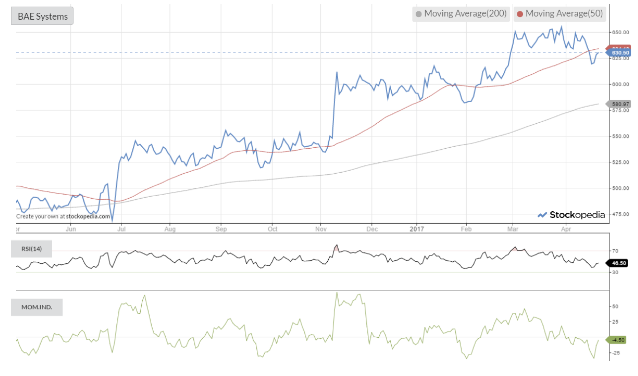
While BAE’s momentum remains strong, the stock could continue to perform well. Although the quality and value scores are not outstanding, I don’t believe that they highlight any serious concerns.
Broker forecasts put BAE on a rolling forecast P/E of 14 with a dividend yield of 3.5%. That seems fair for a stock that’s expected to deliver eps growth of about 8% in each of the next two years.
Although I am concerned that the supportive environment the firm is enjoying could change, BAE passes all of my rules and will benefit the portfolio’s diversification. So I’m going to rebuy BAE for the SIF Portfolio this week.
As always, please DYOR before making any decisions, and share your view in the comments below.
Roland owns shares of BAE Systems, Redrow and Central Asia Metals Limited.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

No comments yet
No one has commented here yet! Why not be the first one?