SIF Portfolio December review: Norcros, BAE Systems and Pan African Resources

The stock market generally goes quiet over Christmas, making it a good time to disconnect and focus on real life... But with nothing much happening from day to day, it’s also a good time to take stock of how your portfolio has performed, and consider your plans for the year ahead.
I’m hoping to take a detailed look at my personal portfolio over the New Year break, but before then it’s time for me to deliver the monthly review of the SIF portfolio. After a strong month for markets generally, who’s in and who’s out?
There are three stocks up for review this month. Each company name is linked to my original article on the stock:
- Bathroom fittings group Norcros
- FTSE 100 defence giant BAE Systems
- Gold miner Pan African Resources
Norcros and BAE have now been in the portfolio for six months, so are due an initial review. Pan African Resources has been held for longer, so is kept under review each month.
Norcros
Bathroom fittings group Norcros seems to be a perennial value stock. Always cheap, but always battling against poor sentiment (and a big pension deficit). Performance has stayed true to form during the stock’s time in the portfolio.
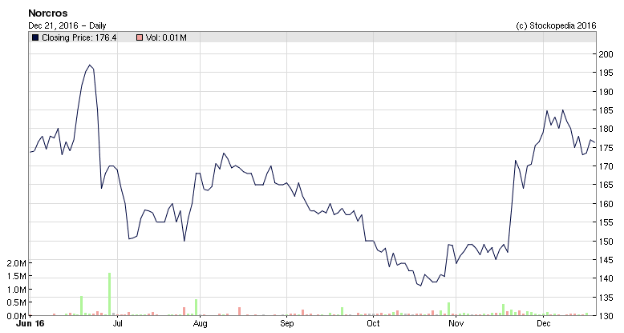
November’s interim results showcased a 10% rise in pre-tax profit and a 9.1% hike to the interim dividend. Norcros now trades on a rolling forecast P/E of just 6.6, and offers a prospective yield of 4.3%.
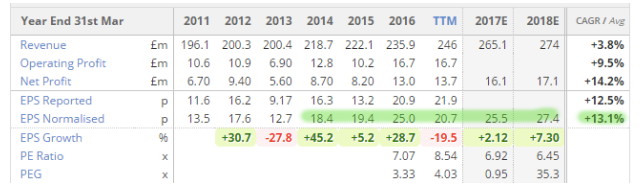
The market seems unwilling to give Norcros credit for steady earnings growth
Net debt is low and high single-digit earnings growth is expected next year. Higher bond yields could soon cut the pension deficit. But Norcros shares remain resolutely cheap, on a forecast P/E of just 6.5 for 2017/18. I’d be happy to continue holding this stock, but the company’s weak share price performance has left it with a negative 1year relative strength. As a result, Norcros has fallen out of my stock screen and must now be sold.
The group’s shares have fallen be about 1.5% during their time in the portfolio. However, July’s interim dividend payout of 4.4p per share was worth £1,214.27. This equates to a return of 2.4%, and lifts the total return from Norcros into the black (just).
Verdict: Sell
Total return: +0.9%
BAE Systems
The portfolio’s virtual investment in BAE has proved to be very well timed. Shares in the defence firm have risen by 20% since it was added to the portfolio in June. To some extent, I think I’ve been lucky.
June’s 9% surge was largely due to the devaluation of the pound which followed the EU referendum. The 11% rise seen in November followed the election of Donald Trump. Although BAE also announced a number of contract wins around that time, I suspect the market was responding to the US presidential election result more than anything else.
Earnings forecasts for the group have remained fairly constant this year, ranging between 39p and 40p per share. So BAE doesn’t as attractive as it did six months ago. The shares now trade on a forecast P/E of 15.2 with prospective yield of 3.6%. Back in June, they had a P/E of 12 and a forecast yield of 4.4%.
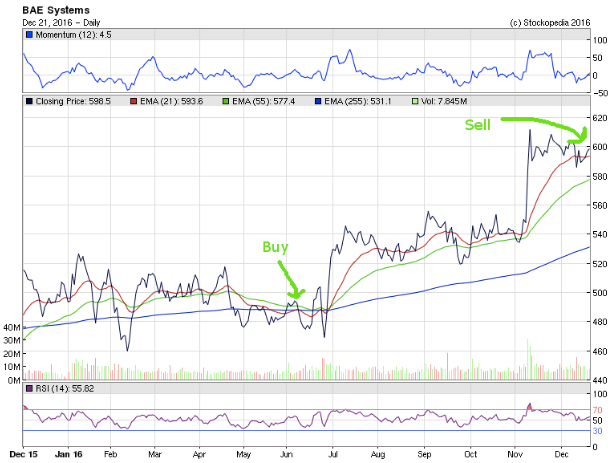
The chart still looks good and suggests further upside is possible, but the fundamentals suggest to me that the shares are now fairly priced.
I think most of the good news is in the price. While BAE remains a solid income stock (which I hold myself), I’m not sure there’s much near-term upside for investors seeking growth. BAE’s re-rating seems to have been the result of sentiment rather than an underlying change in the outlook for the group.
My screen results seem to confirm this view. BAE’s earnings yield has fallen below by 8% threshold and the group’s PEG ratio has risen above my limit of 1.2. As a result, the stock no longer qualifies for the SIF portfolio and will be sold.
Verdict: Sell
Total return: +23%
Pan African Resources
Pan African Resources has been one of the stronger performers in the gold sector this year. At the time of writing (just before Christmas) the shares are up by 76%, compared to gains of 36% for Randgold Resources, 115% for Highland Gold Mining and 93% for Centamin.
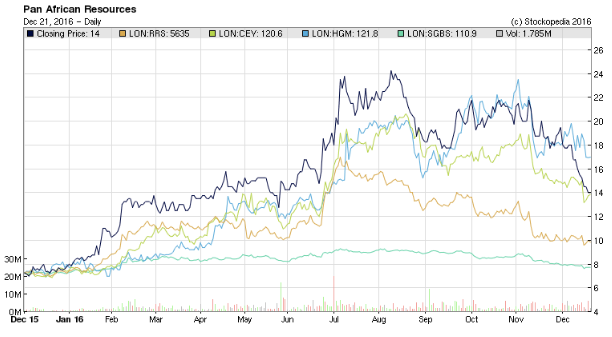
Pan African is the dark blue line. The pale blue line at the bottom is a gold ETF
To put the firm’s performance in context, the price of gold has risen by about 6% so far this year. This illustrates how mining stocks can be heavily geared plays on the underlying commodity. Unfortunately, profiting from this kind of gearing requires good timing. I didn’t really add Pan African to the SIF portfolio early enough.
The group’s shares peaked in August, less than two months after I added them to the portfolio. They’ve since gone into reverse, and the portfolio’s position is currently running at a loss of about 6%. However, December’s final dividend payment adds a useful £2,957 to my notional return, lifting the overall position to breakeven.
My personal view is that unless a profit warning is in the pipeline, Pan African shares have been oversold and are attractive at current levels. However, the stock’s position in the portfolio has become uncertain because it’s too cheap! My screening rules include a minimum P/E ratio limit of 5. Pan African’s forecast P/E ratio is hovering around five, causing it to dip in and out of the screen results.
A P/E of less than five is unusual for a healthy company. It tends to suggest that the market doesn’t believe profits are sustainable. I’ve no way of knowing whether that’s the case here, but statistically there’s a reasonable chance that it might be.
As I write, Pan African is still in the screen, so I’m going to hold on for another month at least.
Verdict: Hold
Total return to date: 0%
Roll on 2017…
I hope you’ve enjoyed my foray into rules-based investing this year. I’ve greatly appreciated your feedback and comments and am looking forward to continuing work on the SIF portfolio in 2017.
The portfolio’s first anniversary in April will give me the chance to tweak some of the rules. As a number of readers have commented, the most obvious area for change may be the minimum holding period. However, I’m going to stick with the rules until then, in order to give them a chance to prove themselves (or not).
All that remains is for me to I wish you all a very happy new year, and all the best for 2017!
Roland owns shares of BAE Systems.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

5 comments
What appeals to me is your rules-based portfolio is not very far off being self-selecting and self-regulating, and it seems to be doing very well. I was sorry to see Plus500 be ejected recently as that deviated from your current minimum six month holding rule.
Is it feasible that SIF 2.0 could run with zero personal intervention?
Another interesting read, thank you.
Hi shine66,
Thanks for your comments. I'm not planning to make SIF 2.0 completely self selecting, but I do plan to take a hard look at the subjective judgements I've made during the portfolio's first year. With stocks such as Plus500 (LON:PLUS) and XLMedia (LON:XLM) I've made decisions to buy and sell that would have been made differently if the portfolio was completely automated.
My original remit for the portfolio did allow me a 'manual override' facility (e.g. the recent sale of £PLUS), but I'd like to refine my stock selection criteria so that this is only required in more extreme scenarios.
More on this over the next few months, as the portfolio approaches its first anniversary.
Regards,
Roland
Roland, the Avesco (LON:AVS) takeover is complete should it not be removed from your portfolio now?
Hi Herbie,
Mistakenly, I missed the deadline to sell Avesco (LON:AVS) portfolio before it was delisted. I aim to find out this week what happens to delisted stocks in Stockopedia portfolios, as I'd obviously like to convert this holding to (virtual) cash.
I'll provide an update when I find out.
Roland
Interesting to read your comments on Pan African Resources as well as how their performance relates to RRS, HGM and CEY. All these are well established gold producers with their production costs well under control.
I don`t know much about the rules of your strategy but I expect they are fundamentals based.
I also look at the fundamentals but lean more to technical trading, I think all the above are predictable instruments to trade as outlined in my comment on Ben Hobson`s post of 26/10/16 about the Resurgent Mineral Sector here in Stockopedia.
Essentially it`s all about the gold price and the timing of entries and exits is critical.