Stock in Focus Portfolio: Will Pan African Resources deliver golden returns?

This year’s rebound in the gold market has an authentic feel, in my view. The gold downturn started much earlier than the slump in the oil and the general mining downturn.
Until a few months ago, gold mining stocks had been out of favour for some time. That situation now seems to be changing.
Gold miners that worked hard to cut costs during the downturn are now starting to reap rewards. While I’ve been writing this article, gold touched $1,300 per ounce. That’s a 22% rise so far this year.
While I’m not sure how long gold’s momentum will last, the evidence suggests that gold has now bottomed out and entered a new upcycle.
Gold miners rebounding
Shares in many gold miners have already risen by 50-100% this year. This week’s portfolio selection, Pan African Resources, is no exception. At the time of writing, these shares have risen by 92% so far this year. Yet unlike some of its peers, Pan African still looks good value.
The stock trades on a low forecast P/E with a generous yield. Pan African also benefits from a decent level of analyst coverage, which should help us to form a more meaningful opinion about the near-term outlook.
Pan African Resources’ StockRank of 98 means that it has risen to the top of the Stock in Focus portfolio screen this week, and will be the next addition to the SIF portfolio.
This could be a controversial choice and it’s certainly not without risk, as I’ll explain later. But now could be a good time to get back into the gold market, and I believe that Pan African could have the potential to deliver attractive returns for shareholders.
Deceptively good value?
A cyclical stock coming out of a deep downturn often looks expensive on a trailing P/E basis. According to Stockopedia, Pan African trades on a trailing twelve month P/E of 15.6 and on a 2015 historic P/E of 20.7.
I’m not too concerned by this, given the improving outlook. I’m also encouraged by Pan African’s other ValueRank metrics. The stock has a trailing dividend yield of 3.7% and an earnings yield of 9.3%.
The only real concern is that free cash flow was apparently negative last year. However, closer inspection suggests this is the result of an accounting quirk. Like Laura Ashley, Pan African includes dividend payments in the operating cash flow section of its cash flow statements.
This means that dividend payments are deducted before free cash flow is calculated (free cash flow = operating cash flow minus investing cash flow). Since dividends are normally paid from free cash flow, this seems illogical to me. Here’s an example from the firm’s latest interim accounts:
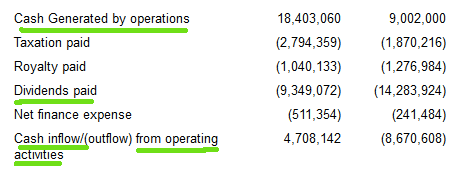
If dividends were accounted for in the normal way, I estimate that the dividend would have been covered by free cash flow last year, excluding acquisitions.
A cut above the rest?
Pan African scores highly for quality, with a QualityRank of 95. A look at the QualityRank breakdown shows several obvious reasons for this.
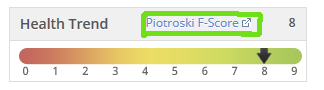
First up is a Piotroski F-Score of 8 out of a possible 9. This score is heavily weighted in the QualityRank calculation and has also become one of my own favourite metrics. It provides a useful snapshot of profitability, liquidity and cash flow. If you haven’t investigated the F-Score before, I’d highly recommend it. You can get a detailed breakdown for any stock by clicking on the Piotroski F-Score link on the Stock Report page:
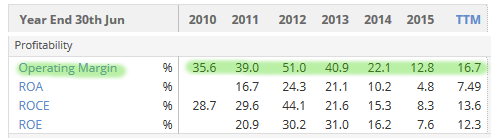
Another big plus is that unlike many miners, Pan African has a consistent history of being profitable! The firm’s five-year net average margin is 21.7%. Although profit margins did fall in 2014 and 2015, results for the first half of the current year suggest margins are now rising again:
I’ve already discussed the Pan African’s cash flow so won’t reiterate that here. The only additional point I’d make is that the firm maintained a net cash balance from at least 2010 until last year, when a modest amount of debt was drawn down to finance various acquisitions.
Momentum
Pan African has blistering momentum at the moment. A MomentumRank of 99 provides some clue to this and is the result of strong price and earnings momentum.
Obviously it’s not possible to tell when the current surge in gold and gold stocks will start to moderate. But in my view Pan African’s momentum metrics do suggest that the stock has both short and medium-term momentum:
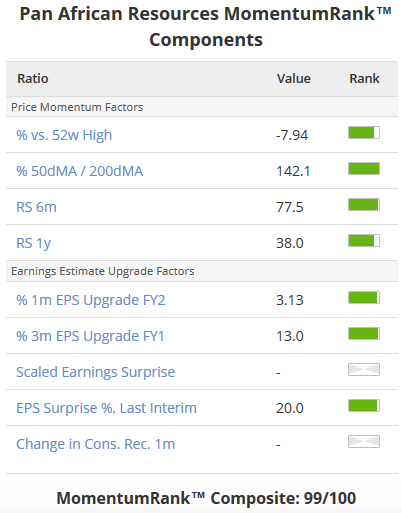
Earnings estimates have been upgraded by 13% for the current year over the last three months. This is largely the result of the price of gold romping higher. Next year’s earnings forecasts have also been tweaked up.
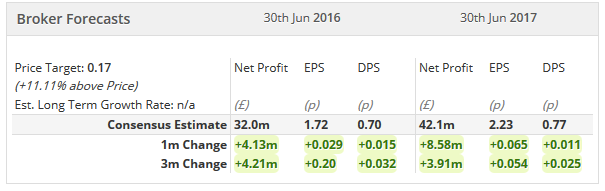
The shares now trade on a current year forecast P/E of 8.4, falling to a P/E of 6.5 for 2016/17. There’s a forecast yield of 4.8% for the current year, rising to 5.2% next year.
If Pan African can deliver on these forecasts without compromising its balance sheet, then I’d hope that these valuations might improve.
Interestingly, Pan African delivered a 20% earnings surprise during the final six months of 2015, when the gold price was much lower and quite volatile. This suggests to me that the company could perform well in a flatter market.
What could go wrong?
I mentioned earlier that Pan African carried certain risks. One of these is simply that the firm operates in South Africa. While Pan African appears to have made good progress with wage negotiations, as part of the local ownership requirements for its mines, this area is a moving feast. In my view it remains a risk.
A second concern is that currency effects could make it hard to monitor the firm’s progress. Pan African effectively works in three currencies. Most costs and gold sales are in South African Rand, but gold is sold based on its US dollar market price. The rand has weakened against the dollar over the last year, which has helped South African miners. But this trend could reverse.
A further complication is that Pan African’s reporting currency is the pound. We also need to consider the strength of the pound against both the dollar and the rand when interpreting the group’s results.
Finally, Pan African is listed on AIM. Solid companies shouldn’t be penalised for listing on AIM, but they are. Paul Scott highlighted this issue in Tuesday’s SCVR.
Bold or rash?
My experience suggests that mining stocks are not always popular with Stockopedia subscribers. Adding a gold stock to the SIF portfolio could be a mistake. I may also be too late to catch the bulk of the gains.
However, Pan African is a stock I’ve been watching for some time. I believe it’s a well run, profitable miner with good long-term income potential and a reasonable valuation. For these reasons, it’s now in the portfolio.
Disclosure: Roland owns shares of Laura Ashley.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

29 comments
this just come up on the winning growth and income screener today, so another positive perhaps.
Hi Roland, as you rightly say, this company does look attractive from the financial numbers. However, I recently sold my holding as I do not like the idea of the company being run by a new, young CEO who lacks a technical knowledge of mining. In addition, the company's recent purchase of a colliery seems bizarre to me as coal is a significantly different business to gold. Mr. Loots has described the collier as "accretive" to the the company's business but has not said it would be accretive to profits (I'm sure he knows the difference). For me, the resignation of the experienced and successful CEO (who has plenty of technical knowledge of mining) followed by this acquisition is a red flag and I wonder if he resigned because of this acquisition because it did not make commercial sense. Despite the excellent financial story I think the risks for this business are too high for me. You pose the question what could go wrong, well my fear is that the the acquisition of the colliery occurred as a result of political pressures and this will mop up some of the company's profits from its gold mining core business.
Thanks Peter, that is very helpful, I was tempted.
Ken
Thanks, Peter!
For other readers - I found this article, which discusses the points that Peter raises and alludes to similar concerns particularly the move into coal.
http://www.financialmail.co.za/moneyinvesting/2016/04/21/pan-african-resources-opportunistic-move-into-coal
Hi Peter,
You make a good point about the coal mine. I didn't have space to mention it in the original article, but I do find it a bit hard to understand. Even assuming that it is a cash generative asset which will add to free cash flow and earnings, it's a slightly odd move.
I'll give Pan African Resources (LON:PAF) the benefit of the doubt for now, but I do have some reservations about this.
Regards,
Roland
Thanks Peter, I was tempted by the SP quants, but I am more swayed by your qualitative comments. Thanks for the insights.
Also, thanks to the others who pointed out entry/exit cost implications.
I'll sit and watch this one.
Regards
Howard
I think PAF would be much more inviting for small investors if they had applied to remove the stamp duty like most AIM stocks have. Anyone any idea why they haven't done this? For me it basically doubles the costs of buying the shares, which, combined with the spread, means a big loss before you start.
Whitbyview,
Thanks for pointing this out, I didn't realise stamp duty still applied to PAF. Having said that, the spread shouldn't usually be too bad on Pan African Resources (LON:PAF) -- about 0.35% according to Stockopedia, anyway.
Regards,
Roland
No, neither did I until I got a quote online yesterday. I just assumed stamp duty had been removed on all aim shares but apparently it's something companies have to apply to have removed with CREST and for some reason, PAF have not done this. I'm sure it's more complicated than what I am making out but a shame. As for the spread, yesterday this was 0.5p on 14p which I make closer to 3.5%? Think you might have got an order of magnitude out there. Anyway thanks a lot for the thought provoking piece :)
Morning Whitbyview,
You're right, I was an order of magnitude out. A spread of 345bps is of course 3.45%. I blame the early hour...
Thanks for pointing this out!
Roland
Maybe they lose the stamp duty exemption because they're dual listed on AIM and the JSE.
I bought some Pan African Resources (LON:PAF) recently - the spread was nominal in case that helps, but it's a small stock so spread can vary quite a bit depending on volume.
Great article Rowland. By way of a coincidence I have been giving PAF the slide rule treatment to day and came to the conclusion I should have an initial small holding and if gold does decide to head north then add a few more!
Roland
Thanks for the article. I found it to be a useful education on how you are interrogating Stockopedia's metrics.
I have a question about the design of your portfolio.
As you are building a portfolio, have you got a pre-designed allocation of investments across sectors/industries in mind that you are eventually attempting to fulfil. Or, are you driving the portfolio build based solely on one 'attractive' investment at a time, disregarding cross-sector/industry allocations?
Regards
Howard
Howard,
Thanks for your comment. My approach to sector diversification will be flexible, but I do have two basic requirements I'll aim to work within:
- An approximate even split between defensive and cyclical stocks
- A minimum of four different sectors in the portfolio out of the ten main FTSE sectors (http://www.stockopedia.com/sectors/?region=&type=economicSector)
To some extent my choices will be influenced by the stocks that qualify for my screen. These are (currently) focused in 6-8 sectors, for example.
Hope this is of some help.
Regards,
Roland
Roland
Thanks for the explanation.
Regards
Howard
No moral concerns about investing in gold mining then?
Nope, why should there be?
So you invest in any company?
Yup,favourites are guns, drugs and tobacco! :)
What do you mean by "moral concerns about investing in a gold company?"
Something to do with low wages/worker exploitation?
Partly but far more, gold mining is one of the most environmentally destructive forms of mining. It creates massive amounts of toxic waste and causes more global mercury pollution than any other source. Also the workers are subject to dangerous working conditions for low wages, not just from the mining but from the cyanide and mercury used to extract the gold.
I would be interested to know exactly how gold miners have cut costs?
To be honest I hadn't really thought about the damage such mining entailed.
Given that much of it occurs in third world/poor nations I've always tended to place more weight on the provision of employment to the locals/and trickle down effects of their spending wages in the local economy etc etc than likely environmental concerns.
I presume the wages are "reasonable" whilst not being "extravagant" or "disgraceful sub market?"
In South Africa I think they earn about £300 pm. Others countries the wages/conditions maybe much worse with child labour being used.
If its listed its legal, so yes
Although the rising USD gold price certainly helps the sentiment it's the rand price of gold that makes the biggest difference. And although the conversion to reporting in GBP adds another layer of complexity it isn't too hard to model:
Note: EPS varies slightly to published figures due to accounting for depreciation etc. so the above is not intended to reproduce the accounts but model the impact of current prices.
If production & all in sustaining costs are flat into H2 then current average gold price & FX would see 1.3p EPS for H2 and a forward P/E of c.7.8.
If current prices remain the same going forward then FY17 would see 2.6p and a FY17 P/E of c. 5.6.
P/E's are not always a good way to model limited lifetime assets however given that Pan African Resources (LON:PAF) ' s assets have life of mines from 16 to 28 years this should go some way to mitigating this concern.
Very helpful info! Thank you!
dangersimpson,
Thanks for these figures. I agree that the rand price of precious metals is key for South African miners. Obviously this is a function of the ZAR:USD exchange rate and the USD price of gold, although the exchange rate has probably been the biggest help over the last six months.
My point was that both these factors have changed dramatically over the last year. These changes have largely been favourable for South African miners, but this won't always be the case.
Re. the P/E ratio, I think the lifespan of the Pan African Resources (LON:PAF) mines is sufficient to use this metric, especially as PAF's gold resources are c.30Moz -- around three times current commercial reserves. There should be scope to replace spent reserves with resources in the future, assuming market conditions are favourable.
I'm more concerned that P/E isn't always a great metric for heavily cyclical stocks, which look cheap near the top of the cycle and expensive close to the bottom.
Regards,
Roland
Great article, Roland!
Agree plenty of risk here, but also potential upside. A small cap Gold Miner listed on AIM would usually be the stuff of investor's nightmares, but I like the look of £PAF! Pan African Resources (LON:PAF) are audited by Deloitte, which may seem a trivial detail, but as a rule-of-thumb I try and ensure all the AIM stocks are audited by one of the big four. Not a cast iron guarantee of course, but I find it reassuring nonetheless. Coupled with a high QualityRank and Pitroski F-scores., I think there is potential here.
Thanks Tim.
Good point about the auditors, I'd not noticed that.
Roland