Small Cap Value Report (3 May 2016) - PLA, SDM, DPP, CRAW

Good morning!
UK Investor Show
What an enjoyable day Saturday was! I cycled from Islington down to Westminster for the show, on a Boris Bike, but unfortunately arrived late, and I missed the talks from Mark Slater & Nigel Wray.
However, the next session, from our own Ed, was just brilliant (and I'm not just saying that because he's my boss here!). Ed focused on investor psychology, and used some clever software to make it interactive. So he asked us a series of trick questions, we had a few seconds to respond on our smartphones, then he revealed how stupid we all were!! I got nearly every question wrong. Oh dear!
The key point was that Ed was highlighting how the quick, impulsive section of our brain (the old monkey brain which we share with animals) leads to us making terrible investing mistakes. Whereas the more we engage our higher level, slower, but more rational brain, then the better our performance should be.
Fascinating stuff. Also apparently it has been proven that women make better investors than men. I can quite believe that actually, as the female investors that I know seem much more level-headed than most male investors. We males are far too prone to make impulsive & reckless decisions - I could write a book about that for my own mistakes, and one day I will!
Isn't it strange therefore that it's nearly always the men who manage portfolios, despite being the wrong gender to do it well!? (Sweeping generalisation of the day no.1!)
I was delighted to meet literally dozens of my readers from here at the investor show. It was continuous all day actually, so in the end (well at lunchtime) I bowed to the inevitable and allowed my readers to start buying me pints of lager, and crisps at the Westminster Arms.
Peter quipped that he's going to wear safety goggles next time he buys me a pint & crisps, as I pebble-dashed him with small particles of salt & vinegar crisps, due to being unable to stop talking for long enough to swallow them!
I had to peel off back to the investor show at 2pm, in time to give a 20 minute talk to the audience in the Analyst Room. My stock picks from last year (WTM, something else, and AVS were up 17%, 17%, and 67%). So buoyed by this good luck, I decided to offer up some stock ideas for further research again, which were;
Avesco (LON:AVS) & Waterman (LON:WTM) again, joined by Restaurant (LON:RTN) (at 273p post profit-warning).
(please note that I hold long positions in all 3 of these companies)
I just started on my "worth a look" list, but only got as far as Flowtech Fluidpower (LON:FLO) (I do not hold any position in FLO) before the next speakers started hovering next to me, giving me that "stop talking and go away" fixed smile. It's easy to miss that smile though, as I discovered once at a Mello event, when Leon Boros resorted to making a throat-cutting gesture (complete with grimace) to force me off stage when I'd run 20 minutes over time & ruined the event's remaining scheduling.
I managed to grab Neil Catto, the CFO of Boohoo.Com (LON:BOO) (I hold a long position in this share) and have a quick chat with him. Everyone I met seemed to like him, finding him very straightforward & down to earth. I think BOO shares are fully valued for now, but it's very much a long term winner in my view. So trying to time the market by going in & out is a risky business.
I stressed to him that the Call Option over PrettyLittleThing.com is now the burning issue that needs to be resolved, to eliminate the conflict of interest between family and listed company interests. He took that point on board.
There was a strange twist to the day - I meandered over to Tom's old restaurant in Clerkenwell for the after-show party, now owned by the affable Darren & Martha. Whilst outside talking to Nigel Somerville, a drunk/druggie wandered down the road and deliberately walked straight into poor Nigel, sending him flying. He then started trying to smash up the restaurant, hurling objects (such as an A-board) at the shop front.
Next thing I know, Lucian Mears is outside, grappling the chap to the ground, explaining calmly to him why trying to smash up a restaurant really isn't a good idea. The police were called, and I helped Lucian restrain the chap until they arrived.
I did wonder if one of Tom's many enemies might have arranged this fracas by paying the chap to make mischief? All I can say is that the quality of the attacker matches the quality of the shares which Tom highlights.
ShareSoc Brighton
Oh dear, this is not going well. Only 7 people have signed up so far, when ShareSoc needs 20 for the event to go ahead.
The event is a week today, 10 May 2016. Booking details are here.
There are now 2 speakers, Avation (LON:AVAP) (I hold a long position in this share) and Fishing Republic (LON:FISH) (I hold no position in this share) - the latter in particular is potentially interesting, if they could get their inventories under control. So it will be very interesting to hear from management on that key point.
As this is the first Brighton event, if it's cancelled from lack of investor interest, then there won't be any future ones. So I'm desperate to see this first event get off the ground, as we can then build it into a regular thing. The ones I organised in 2014 were very enjoyable, and quite well-attended. However, it's so difficult to arrange them when people only seem to book in at the last minute, if at all.
So please do support this event by booking now, if you can, otherwise we'll lose it altogether.
ShareSoc vs Marcus Stuttard (head of AIM)
I'm delighted to see ShareSoc going public in its campaign to improve the standard of companies on AIM. An article was published recently in the Times, with Stuttard defending AIM.
This is ShareSoc's response, in a letter it has sent to the Times, in reply:
Dear Sir,
Thank you for publishing the article entitled “We’re no dodgy casino…” on 2nd May, containing comments I made at the AGM of the London Stock Exchange Group, on behalf of ShareSoc, and the response of Marcus Stuttard, head of AIM.
Mr Stuttard comments: “[People] wouldn’t invest if they felt there was any kind of problem…”. He is right. Many won’t invest in AIM companies, due to AIM’s reputation as a casino, thus depriving legitimate businesses of much needed capital via this route.
ShareSoc can cite a litany of frauds and abuses perpetrated on investors in the AIM market – many within the last year alone. Some of these were Chinese companies, which the AIM market sought to attract, and some home grown.
Without transparent and effective prosecution of the perpetrators of these frauds there is no deterrent – and that is why we continue to see them occurring time and again.
The LSE seems well satisfied with the listing and transaction fees it generates from its operation of the AIM market but does not seem to want the inconvenience of having to properly fulfil its role as regulator of that market. We therefore now call upon the FCA to step in and conduct a thorough review of the operation and regulation of the AIM market.
Yours faithfully,
Mark Bentley
Director, UK Individual Shareholders Society
Bravo to ShareSoc for taking up this issue.
My view is that the LSE's stewardship of AIM has been appalling. It's worse than a casino actually. It's a free-for-all, with no effective regulation, which has therefore become a magnet for fraudsters all over the world.
For this reason, I personally won't touch any overseas AIM-listed companies, apart from SKIL Ports & Logistics (LON:SPL) which is a rare exception to my self-imposed rule.
What a state of affairs, where many private investors need to rely on bloggers like me to expose the dodgy companies, because there is no effective regulation. If I can correctly identify the frauds (e.g. Quindell, Globo, etc), several years ahead of them imploding, why can't anyone at the LSE?
Also, the perpetrators of frauds are seemingly free to carry on with their lives! What punishment will the Chinese fraudsters face, after they successful used AIM as a vehicle to rip off British investors? Where is Costis from Globo? Why is Rob Terry free to continue with his next attempt at financial engineering (Quob Park)? The problem is that the bad guys get away with it, with impunity.
All of this is of grave concern. The trouble is, it's given AIM a terrible reputation, and many investors now steer clear of AIM stocks. That is such a pity, as AIM contains several hundred good companies too.
Time for a change I think. Stuttard should be sacked, and someone with a stronger moral anchor brought in to straighten out AIM. This is a good example of bad capitalism - people at LSE putting profit before ethics. They know the facts as well as we do, but turn a blind eye because LSE generates income from each company listed on AIM. It's not good enough.
BHS
There's a lot of comment about Sir Philip Green's involvement in BHS, which he owned from 2000-2015. I've had a look at the accounts for BHS Ltd going back to 2006, and I can't see any dividends being paid at all. The company was profitable until 2008, when it started losing money. Personally I'm amazed thst BHS lasted as long as it did - a redundant format that probably would have gone bust a lot earlier if Mr Green had not been involved and breathed fresh life into it.
Also, the pension deficit that he is being blamed for, was actually in surplus in 2008. The deficit which has since arisen was caused by Govt policy - ultra-low interest rates, and of course increasing life expectancy.
It seems to me that many people have pre-judged Green, and are not interested in the facts. They want him to be guilty of something bad, and are blurring the BHS issue with other issues such as his vulgar, conspicuous consumption, and his abrasive personality. The politics of envy are always so close to the surface in the UK, sadly. Would I prefer it if he spent his money on helping the poor, rather than ridiculous yachts & parties? Of course, but that's none of my business. In a capitalist system, he can spend his money on whatever he likes - and other people will judge accordingly.
Also, note that Green's companies pay full UK Corporation Tax. He could very easily have set them up using an offshore, private equity style structure, to avoid Corporation Tax altogether, but he didn't. He deserves considerable credit for this. He has however dodged UK income tax, by registering the company in his wife's name, and parked her offshore in the tax haven of Monaco.
Did Green cynically starve BHS of funding? Not that I can see from the accounts. He seems to have actually spent 15 years trying very hard to make it work - expanding product ranges, revamping the stores, etc. That's not at all how asset strippers usually behave, is it? So why do people think he asset-stripped it?
I'm not a fan of Green generally, but he's a smart retailer, and overall has probably done more good than harm for the UK retailing sector. If he's found guilty of any genuine wrongdoing with BHS, then fine, I'll stand corrected. So far though, I've not seen any evidence at all that he's guilty of anything. Just people who want him to be guilty. Also a lot of hindsight stuff - if a company pays out dividends when it's profitable, and has distributable reserves, then that's absolutely fine. If that business subsequently goes downhill, due to competitive pressures, then that's a completely separate issue.
The above is true of so many issues actually. It's pointless discussing politics with almost everyone, because they usually don't care about facts. They have pre-conceived ideas, and will twist or just ignore facts which disprove their existing view.
We're all guilty of this to a certain extent. It's particularly dangerous when this same human weakness crops up with shares. Have you noticed how we tend to give a company the benefit of the doubt, if we hold the shares? Then people often turn violently against a company once they have sold their shares. So in other words, people suppress any information they don't want to hear. Once they have detached from the share by selling it, they suddenly reverse their opinion and start slagging off the company they were defending to the hilt just days earlier! This is one of the reasons I rarely post any more on bulletin boards, as most people are mindless in their support for a share, simply because they want to talk up the share price, and are emotionally attached to it. So their views are worthless to me.
Also, I've found that if you become the public cheerleader for a particular stock (been there, done that!), then it's much harder to change your mind. You become locked into owning shares which you should probably be selling. These days, I have no trouble at all changing my mind, if the facts change. That approach has greatly improved my investment returns. It's a key skill for all investors to develop actually. Switching off the emotional part of the brain, and focussing solely on interpreting the facts & figures. Very much as Ed highlighted in his talk on Saturday.
EDIT: Incidentally, I was surprised to read in one sunday newspaper that there were "howls of laughter" at BHS head office, at the suggestion that Mike Ashley of Sports Direct is considering a bid for the whole of BHS (I hold a long position in SPD).
I suggest that staff at a company which has just gone bust are not really in a position to be howling with laughter at any potential rescue bid.
It will certainly be fascinating to see how the BHS situation develops.
Plastics Capital (LON:PLA)
Share price: 110p (up 6.8% today)
No. shares: 35.3m
Market cap: £38.8m
Trading update - an in line update for the year ended 31 Mar 2016:
Plastics Capital (AIM: PLA), the niche plastics products group, is pleased to announce that it expects trading for the full year ended 31 March 2016 to be in line with market expectations.
H2 was stronger than H1, and the outlook comments sound encouraging, particularly for the new products being developed:
Despite difficult macroeconomic conditions, which negatively affected certain parts of the business, new business wins have generally compensated for softer global markets. Moreover, during the last year, we have developed a pipeline of new products to be introduced during the next 12 months, which create the potential for strong organic growth over the next few years. We are also expanding capacity in industrial films, bearings and mandrels - all areas where we anticipate capacity constraints in the next 12-24 months. Finally, we continue to develop opportunities for acquisitive growth which remains an important part of our business strategy.
My opinion - this seems to be a small group which has plodded in the last 5 years or so, resulting in a lacklustre financial performance.
The dividend yield has been rising though, and is high now, at just below 5%. Mind you, I question the wisdom of paying out big divis, instead of the surely more sensible strategy or building up cash for further acquisitions?
It seems a bit pointless paying out big divis, but then effectively taking them back (through dilution) by doing Placings in order to fund further acquisitions.
I also have concerns about the extent of adjustments, non-recurring items, etc, in the accounts. I prefer to see clean figures with no adjustments. It's too easy to bury bad news in adjustments.
Having said all that, the update today is clearly positive, so maybe financial performance could start improving?
Stadium (LON:SDM)
Share price: 118p (up 0.4% today)
No. shares: 37.2m
Market cap: £43.9m
Trading update - this looks reassuring:
Trading in the first three months of the year has been in line with management expectations. Following a similar pattern as the previous year, we expect further revenue growth in the second half of the year and this is evident in our strong order book.
Normally I'm wary if a company says it expects stronger H2 trading. However, if this expectation is justified with evidence, of a strong order book, as in this case, then it's usually fine.
New facilities - the company is opening new facilities, including a design centre in Stockholm:
One of our strategic objectives, as outlined in the recently announced 2015 financial results, is to continue to develop the operating model to deliver the Group's customer focused, design-led technology proposition supported by strategically located design centres, manufacturing centres of excellence and regional fulfilment centres. Each of these developments will support further organic growth across the Group.
This worries me. The use of the word "centres" three times in the bit above, which I have bolded, could be replaced by the words: more overheads. Or more fixed costs rather. So if new orders fail to come through as hoped for, then this could become a case of operational gearing in reverse - i.e. lower profits, due to increased fixed costs.
2015 results - these slipped through the net - maybe I was having one of my rare duvet days when they were issued?
The P&L figures look good actually - adj. EPS rose from 7.8p in 2014, to 9.9p in 2015.
Balance sheet - not good. Taking off the intangibles, leaves NTAV of only about £0.5m. There's quite a bit of bank debt, and a pension deficit too. So it's probably too risky for me to consider buying any shares.
My opinion - things seem to be going quite well, but this type of business is very difficult to value. Orders can be lumpy. Products come & go, as technology moves forward at a seemingly ever faster pace.
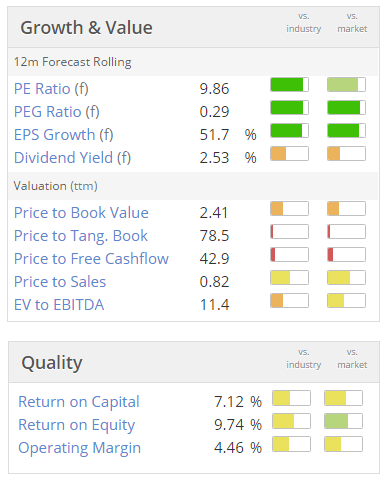
Based on the valuation graphics below, it looks good value on a PER basis. Although given the sector it operates in, and the rather weak balance sheet, I think this is probably priced about right. There could be some upside if the company meets or beats forecasts though. There's also the ever-present danger of a profit warning, if a gap opens up in the order book, at any time. Don't ignore that pension deficit either!
DP Poland (LON:DPP)
Share price: 27.2p (up 4.6% today)
No. shares: 130.2m
Market cap: £35.4m
AGM statement - considerable caution is needed when reading trading updates from this operator of Dominos Pizza stores in Poland. You can easily run away with the idea that this is a successful business being created, and that everything is going well.
Look at these positive highlights today, for example:
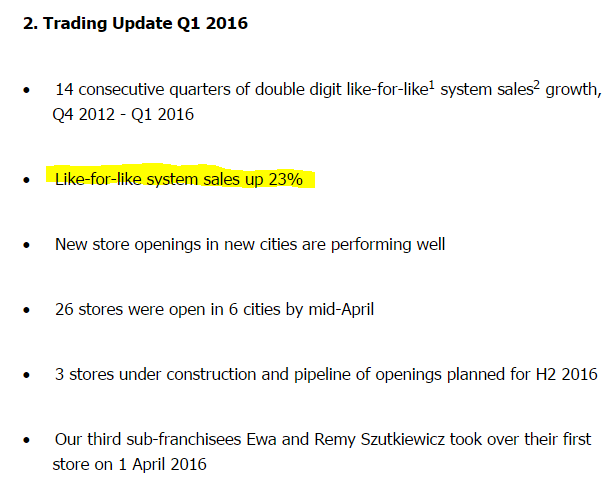
LFL sales growth of +23% does indeed look very impressive.
However, if you look back at the financial results for 2015, they're terrible! This company is still miles away from becoming profitable. The central costs are far too high, and the individual stores hardly make any money to contribute towards those central costs.
My opinion - I cannot understand why investors have kept refinancing this company, when after nearly 6 years as a listed company, it's still nowhere near profitability.
The whole point of a retail roll-out, is that you only do it once the concept is proven. The reality is that Dominos pizzas are too expensive for Poles - I know that because I went to Poland and asked some Poles what they thought of Dominos! That's why the company doesn't make any profit.
Compare that with a much better retail roll-out, Crawshaw (LON:CRAW) (I hold a long position in this share) which hits the ground running, with each new branch making a profit of £140k p.a. soon after opening. That's a format which is worth rolling out. Loss-making, expensive pizza joints, in a country which is already very well-served by cheaper pizza joints, is not a good roll-out.
Admittedly, CRAW is eye-wateringly expensive at the moment, and has been for a while. But there's a good reason for that - you can easily forecast greatly improved future profitability by simply multiplying £140k profit per branch, by the several hundred new branches planned. Sure, there will be increased central costs too. So maybe reduce the £140k to £100k, to be on the safe side, but it's still a very interesting roll-out, where profits are likely to rise rapidly.
I don't see anything like the same potential at DPP. Yet the valuation of DPP is far more bonkers than the valuation of CRAW. CRAW is expensive because it's a classic, profitable roll-out. DPP is expensive because investors are hoping for the best. £35.4m market cap for DPP is complete nuts. It should be fraction of that, in my view. I'm sure it will be again, when the latest round of cash has run out, and it needs to come back for more.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

36 comments
Yes I think a list of all Chinese companies for example who listed in the last 5 years together with list of advisors and list of what is current situation for the company would be very illuminating. And above board.
I agree that better regulation is the way to go, although as ever the combination of a lack of resources and the slow judicial process in this country compared to, for example, the US will make prosecuting white collar crime like this a low priority for the politicians.
Perhaps, in the meantime, investors could try and provide their own regulation by sanctioning the UK professional counter parties such as the lawyers, accountants, PR firms and NOMADs who sponsor fraudulent scams. We already have a few "rules of thumb" derived from bitter past experience, like don't touch AIM listed Chinese investments, but how about a central list of the various advisers to companies that have "gone bad" for reasons that competent advisers should have picked up on? These are presumably matters of fact - as opposed to opinion that might fall foul of libel laws etc. - and would hopefully choke off the fraudsters by blocking their access to the market. Over time, those persistently poor sponsoring firms with their hands in the cookie jar might become a bit more diligent if their reputation suffers and impacts their bottom line. Waiting for the regulators to catch up with the games being played doesn't have an especially good record in the UK, just look at the relatively few successes that the SFO has had.
gus 1065.....An excellent project and ShareSoc has considered this but the problem is that some of the process is linked to assessing whether the parties have been complicit or plain dumb ? ShareSoc can only show the facts and there would be legal threats if we suggested avoiding stocks with X as Nomad/broker or Y as the PR company as you can imagine. We need an investor with little to lose to take on the role and as many have seen only someone like Tom Winnifrith is generally prepared to put his neck on the line and battle against all the legal threats.
A simple list of all companies with the advisers would be enough. Then up to investors to do their own research. Quite a struggle for people to put the list together individually.
Thanks David.
In a way, whether they are "dumb" or "complicit" doesn't really matter. In both cases, as a PI I would be inclined to avoid these intermediaries and the companies they sponsor since they don't seem to be up to the job. It's a bit like a director of a company being held to account for negligence. The test is either that they know and do nothing about the scam, or they don't know and are negligent because as a competent professional, they should put themselves in a position to be able to know.
As the two subsequent posters point out, it should be sufficient to have a factual list of who advised AIM companies that subsequently went bust without trying to apportion blame/responsibility. Perhaps this is a resource that Stockopedia could host?
Thanks again.
Gus.
Well said David
I can't think of another arena where those who commit/assist Fraud can walk away scot free , if it was 10 grand nicked from a school trip fund we'd see jail time, this is different and in some ways worse as it purports to be a regulated market.
As you say it also ignores the scandalous waste of funds that could otherwise be funding worthwhile enterprises and those burnt will not be back.
UK Investor Show ?
I must pay more attention. I went along to the MasterInvestor show the week before to hear Jim Mellon and completely missed this other event, which also looks like it is worth attending.
Thanks for the nice piece of field research on DPP. The business doesn't work there and you found out why ! I suppose we could extrapolate that to some other price sensitive markets.
A better regulated AIM may be a mixed blessing: the junk means that good companies often trade at a discount, with the value usually realised some way or other if you're patient, and it's pretty fun to look for them. The odd Globo-style saga is quite fun to follow as well. In a perfectly fair market Paul would probably be reporting "all stocks reporting today priced to perfection, going back to bed" most days.
There will be good and poorly run companies with good and poor management and probably products and services that with the right management would have performed far better.
The fact is all companies are the wrong price until we know which way round they are all facing and performing in the AIM pack...However it is the fraudulent management, dodgy companies and out and out crooks that have managed to get on the market where prices are totally wrong because investors should never be able to invest in them and unwittingly line the pockets of those extracting the valuable investment funds out of the UK economy. Those funds are stolen away and preventing genuine early stage companies having the opportunity to grow and build future employment for our children and that is a total disaster for UK Plc.
Do we see any legal trials for these frauds ?, Any censures by the AIM team or even a mention of an investigation into all the Chinese scandals ? Not a whimper or whisper...All parties from LSE to AIM team to brokers to nomads to legal advisers all the way through to auditors and even the PR teams are so busy counting their fees they have no appetite to see justice for the wronged investors.
David
The thing is, would the money currently lost to AIM scams get reinvested in good companies if AIM was shut down and the good companies moved to main market standards? or would it move away to random other off-exchange scams? This sort of hot money is chasing wild dreams, that a carefully regulated market cannot provide.
It does not have to be shut down....just regulated properly and with a few serious investigations to catch the fraudsters whilst also netting all the supposed promoters and advisers living off these scams. It would not take long to decide if it was working and a few high profile cases would set the standard.
Hi Paul and all
As a relatively new investor I really enjoyed the networking opportunities provided by the likes of the UK Investor Show and no doubt the Mello event in Brighton could be the same (though a little too far away for me, but I'm a holder of AVAP after meeting Richard at a previous event). All thoroughly recommended!
Speaking to the likes of Neil CFO at Boohoo.Com (LON:BOO) (LON:BOO) was illuminating and hopefully profitable - he confirmed that they were looking into the opportunities for the baby/young child market which fits pretty well with their current demographic offerings!
Also it was a pleasure to meet with fellow investors and chew the fat, despite the hazards of projectile food! Paul, I can vouch, is a most humble individual and was extremely gracious in spending some quality time with me. Top guy!
Cheers!
Paul,
The sharesoc event in Brighton may be being held back because of the possibility of a train strike that day. I for one have registered for it on the basis that they will tell me if it is on or off. Other may gave just not booked because of this
Hope if goes ahead because I want to meet and hear the guy from Avation (LON:AVAP) as I am an investor
Sorry I missed the investor show but business came first
Steve
I know this off topic, in fact all topics but what does amp mean when Paul says .....amp
I'm thinking it's a "&" sign getting mangled between Paul and the website systems.
Paul,
When you say: "For this reason, I personally won't touch any overseas AIM-listed companies, apart from SKIL Ports & Logistics (LON:SPL) which is a rare exception to my self-imposed rule."
I think you are forgetting about Somero Enterprises Inc (LON:SOM) ?
Hi John,
Ah yes, I forgot about Somero Enterprises Inc (LON:SOM) . I've very relaxed about SOM, as it's American (which tends to have pretty good corporate governance), and a long-standing member of AIM. It also pays divis, and has a sound balance sheet. So there are no issues with that one to worry about, in my view.
I think you have to be very careful about particular continents when they bring companies to AIM - Africa & Asia as the ones I'd be extremely wary about, as so many have been frauds or semi-frauds.
Mr Stuttard 's lax governship of AIM has effectively closed the market to decent companies from Asia & Africa, because many investors, like me, simply wouldn't even consider touching any companies from those regions which come to AIM. Once bitten, twice shy, basically.
Regards, Paul.
Paul,
I missed you at the Investor Show, but I echo your comments on Ed's presentation - it was very good. It was also revealing to see Ed's bubble chart of the companies attending with stands (!) and I managed to say hello to him at the end of the day. I also found Mark Slater worthwhile and a several of the others. It was also interesting to spot some of the other attendees looking up companies on Stockopedia as they presented in the Dragons Den's and were mentioned in other presentations!
Thanks for the great analysis and insights and keep up the good work!
Yes Paul I would agree with your advised caution on reading DP Poland trading updates as they seem to think that by leaving the bad parts out, investors will think the company is doing better than it actually is. I have previously posted elsewhere about this after their most recent financial results and I note that today's trading update does not contain a single financial figure! The company needs to understand that a more open approach to presenting progress (or lack of it) is needed. They really need to learn how to communicate with shareholders otherwise they will continue to suffer from the lack of credibility implicit in your criticism. In actual fact the last results show the figures going in the right direction and they should have enough money for at least a couple more years at the present rate of losses, but the lack of financial information in the trading update would lead me to assume that they are doing badly, although the share price movement would suggest otherwise.
I have great faith that Deutsche Borse will clean up AIM. They just won't want the reputational damage. Despite appearances to the contrary (VW - but who really believes that they are alone in that scam?) Germans just look at things like this differently. They simply won't tolerate the sort of blatant fraud that the LSE is sanctioning
Without any comment on the merger or regulation generally, you are optimistic if you think the German stock market is different. They have had plenty of Chinese fraud stock delistings over the last few years.
I know the Germans have a reputation for scrupulous efficiency and straightness, but if you think they will be some sort of white knight, you are a touch naive.
Frankfurt has had it's own problems with Chinese companies. http://www.reuters.com/article/us-germany-deutscheboerse-china-insight-idUSKCN0HH2T020140923
I don't think the way the German regulators have dealt with allegations against Wirecard (I'm short here and have been short pre the Zaterra Research report) cast them in a particularly good light either. They do at least, belatedly, seem to have opened an investigation into the allegations. However their first thought seemed to be to try and shoot the messenger by investigating Zaterra Research.
Anybody who expects DB to be the solution to the myriad of problems on AIM, may be disappointed.
Great write-up... and well done on your bit of semi-police work!
Paul
I do hope the Sharesoc meetings in Brigton become regulars. I will definitely come when I can. But not Monday's or Tuesdays as I work till late in London on Mondays and Tuesdays. And maybe lots of us have already met the nice Mr Richard Wolanski from Avation. He does seem to attend lots of these events.
Julian
Hi Julianh,
I know, most people have met Richard from Avation (LON:AVAP) before, many times.
Unfortunately ShareSoc didn't realise that he did one of my investor events in Brighton 2 years ago. However, a 2 year update seems a reasonable thing.
The most important point however, is that there aren't going to be any more Brighton events, unless people get behind this specific meeting. The first one has to go well, or there won't be any more, probably ever, if it's cancelled due to lack of interest.
ShareSoc have also lined up a second company, Fishing Republic (LON:FISH) in response to investors not being terribly interested in hearing AVAP again. So they've really tried hard on this, and it hence deserves support.
I really enjoy having a meal & drinks with other investors, especially if it's on the doorstep for me. So it would be such a pity if it gets cancelled. Frustrating too, as loads of people asked me to organise another Brighton evening. Then when ShareSoc do arrange one, only 7 people actually book!
Regards, Paul.
Paul
Brighton isn't on my doorstep but it is much easier than London. And I am long on AVAP so happy to get an update. Unfortunately Tuesdays are impossible for me, otherwise I would come just to share thoughts and a nice meal with other investors.
So if there are any other Sussex investors out there, please go to this event. So that we have a next one.
Julian
AIM regulation imo is a national farce - and the authorities sit lamely by.
One thing that puzzles me is why the likes of ASOS remain on it - surely it woudl make sense to move to the main market?
I don't know the detail on ASOS, but there is a strong incentive for some companies to remain if they have shareholders who want to take advantage of the potential IHT relief.
http://www.londonstockexchange.com/companies-and-advisors/aim/publications/a-guide-to-aim-tax-benefits.pdf
Glad you raised the Boohoo.Com (LON:BOO) and PLT issue, Paul! Something that need clarification for the management.
Agreed on AIM - much needed reform here! The lack of regulation is terrible and is costing sensible investors money.
I think next year I shall switch my allegiance from the Master Investment Show (which was the previous Saturday) to the UK Investor Show, as the quality of the speakers and exhibitors sounds quite a bit better. It's a shame they come so close to each other as it makes it a bit awkward to attend both but I've no doubt there is a good reason for it.
Steve
I did both shows but I agree that the UK Investor Show was much better. I'll not bother with the Master Investment next year.
Try taking a Boris Bus not a
Boris bike!
Hi Paul,
It was great to finally meet you on Saturday. Sounds like I missed a good party over in Clerkenwell.
Keep up the good work.
Mike
Paul,
It was nice to be able to meet you briefly on Saturday. Shame I didn't know about the Westminster Arms trip. There was no obvious evidence that you'd been drinking when you did the 14:00 slot in the Stockopedia session. I know it has been said by others, but I am impressed at how modest and unassuming you are despite your obvious knowledge and talent. Keep up the good work.
Cheers
Geoff
Hi Geoff,
I deliberately limited myself to 2 pints before doing my 20 minute cameo appearance in Ed's "Introduction to Stockopedia" talk. That was enough to make it all flow nicely, but not enough to trigger the onset of slurring!
Modest & unassuming are not usually words used to describe me lol! However, I do think it's important to stay grounded by constantly reminding myself of all the dreadful mistakes I've made in the past - after all, how else can one learn from them?
All great fun anyway, I had a wonderful day at UKIS, I really enjoyed meeting so many readers from here. Also I had a good chat with Zak Mir, who I've only ever spoken to very briefly in the past, and he's great fun, a very nice chap. I'm still not convinced about the predictive power of charting, but I suppose as a way of measuring investor sentiment, it might have a place to help time trades?
Regards, Paul.
>>Whilst outside talking to Nigel Somerville, a drunk/druggie wandered down the road and deliberately walked straight into poor Nigel, sending him flying. >>
Was it Tom Winnifrith?