Stock in Focus portfolio: Norcros battles sentiment, is a re-rating likely?

I last looked at bathroom fittings firm Norcros in September last year. At the time I flagged up the stock’s apparent combination of strong value and momentum. I suggested this could deliver good results.
Nine months is a short timeframe, but the markets have not turned in my favour so far. Norcros shares are worth 11% less today than they were when I last wrote about them. So why am I planning to add Norcros to the Stock in Focus portfolio?
Firstly, I should point out that like my other SIF portfolio buys, Norcros qualifies for my Stock in Focus screen. In fact, this stock has been a constant presence in the screen since day one. With a StockRank of 91, the numbers suggest that there is a lot to like.
A second reason is that Norcros results in the period since I last wrote about the firm have been fairly decent. Paul Scott has reviewed November’s interim results and the more recent year-end trading update in detail. But in brief, trading appears to be solid. Norcros has made several attractive small acquisitions in line with its buy and build strategy. The firm’s figures haven’t flagged up any new problems and have included a welcome 10-year settlement relating to pension deficit overpayments. There’s no obvious reason why the shares should be worth less.
Institutional support is also pretty solid. Highly-regarded small cap specialist Miton Group is the biggest shareholder, with a 14.96% stake. Other big shareholders include Hargreave Hale and Fidelity. Chief executive Nick Kelsall has a 1.3% stake that’s currently worth about £1.4m.
A final temptation is that Norcros is the most recent stock to qualify for the Winning Growth & Income screen. Over the last three years, this has been the third-most successful Stockopedia Guru Screen, returning an impressive 80.9% plus dividends. Could Norcros be the screen’s next big winner?
Value in detail
At the time of writing, Norcros has a ValueRank of 87. Drilling down into this as I always like to do, we can see that the stock looks cheap across the board:
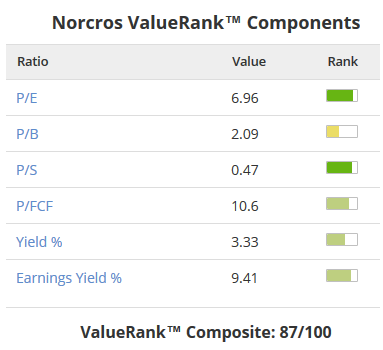
The only exception is the price/book ratio, which is not obviously cheap. I’m not too concerned by this. Norcros isn’t intended to be an asset play and a multiple of twice book value isn’t too demanding for a profitable manufacturer.
The numbers that really attract me are the low price to free cash flow multiple and the attractive 9.4% earnings yield.
One thing I should expand on at this point is the pension deficit. The current position is that Norcros has agreed a ten-year programme of deficit reduction payments with the pension scheme trustee. This will require the firm to pay £2.5m per year, index-linked, for the next ten years.
This is only a modest increase from last year’s payment of £2.1m. Given the firm’s current level of profits, I don’t think these payment will impinge too heavily on cash flow or dividend payments. Another consideration is that the pension scheme is mature. I’d expect liabilities to gradually fall over the next decade.
Is quality a concern?
Norcros scores well on quality with a Piotroski F-Score of 6 out of a possible 9. Of the three fails, my view is that only one -- increasing long-term debt -- is meaningful. Net debt has actually risen further to £33m during the second half of the year, thanks to the Croydex and Abode Home acquisitions. I can live with this level of debt, as it’s less than three times expected profit for last year. It should be easily manageable if historic levels of free cash flow continue.
My core concerns with a business of this kind is how profitable it is, and how sustainable those profits are. The Norcros StockReport shows that the operating margin has been fairly stable for a number of years:
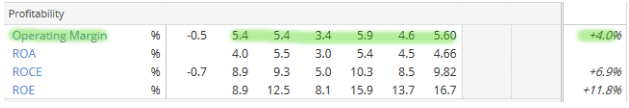
The current average of 4% is likely to rise, when the 2010 figures drop out of the equation and 2016’s results are included. In last year’s interim results, Norcros reported improved margins for the business as a whole.
What’s less obvious is how much potential Norcros has to defend and increase its market share. One likely advantage is that the firm owns a range of different brands, many of which are well established among customers. These should offer a reasonable level of defensiveness in their home markets. At the same time, it should be possible to improve market share using Norcros’ centralised and more powerful sales and marketing machine.
Sinking momentum?
All good investment stories need a dose of momentum to deliver results. Can Norcros deliver? The stock’s MomentumRank has been falling recently and is now down to 73. Although that’s still quite good, it’s the direction of travel which could become a concern.
Technical investors may be concerned that the 50-day moving average has now fallen below the 200 dMA. Six-month relative strength is negative, although the 1-year figure is much better.
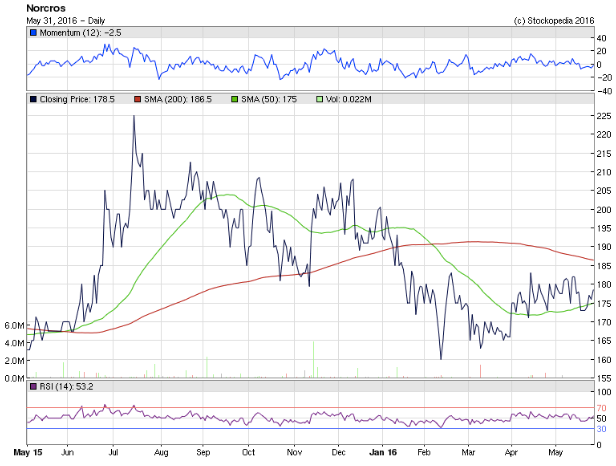
Luckily the earnings outlook suggests that this pessimistic view could eventually lead to a re-rating. Norcros looks cheap relative to forecast earnings, with a current year forecast P/E of 7.2 and a prospective yield of 3.6%. Earnings estimates have risen by nearly 5% over the last three months. An 11% rise in adjusted earnings per share is forecast for the current year.
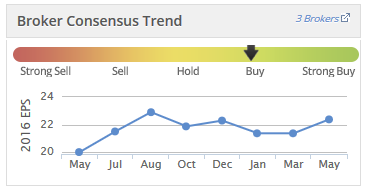
Although this does include the impact of recent acquisitions, I think that this is acceptable given that this is a core part of the firm’s strategy. On these valuation multiples, I don’t think there’s too much risk of overpaying for growth. In my view, a far bigger risk is that the firm’s desire to grow by acquisition will lead it to overpay for sub-par assets.
However, there’s no evidence of this so far. Indeed, I’m reasonably confident about the medium-term outlook for Norcros and may well add it to my own personal portfolio when funds become available. In the meantime, Norcros is joining the SIF portfolio.
As always, I’d love to hear your comments and views on this choice.
Are the cyclical risks too great? Should I be concerned about South African exposure? My view is “no” on both counts, but I could of course be wrong.
This article is purely my opinion and certainly not advice. Please DYOR before making any personal trading decisions.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

11 comments
As bsharmn says, organic growth will not be enough to reach £NXR's 2018 revenue target. Given that Norcros (LON:NXR) management have so clearly held to and restated the £420Mn target for 2018, I think we should expect them to have in view 1-2 substantial acquisitions to complement the smaller ones done to date (Coydex/Abode etc).
These deals have established managements reputation for competence in acquisitions and taught the group lessons on integration no doubt. Since another target is 50% non-UK revenue, perhaps this includes picking up a larger overseas businesses which could help Exports as well. A French one would also open up links to Africa for instance. The Gulf might be another risky but currently cheap target. Given the steadily increasing scale of free cash, debt should be dropping nicely again.
I think we could hear significant news around the end of 2016. In turn this could be the trigger for the re-rating if the deal is as sensible as recent ones (since extra scale will also reduce the risk around the pension and SA business still further as well as making them more noticeable as a group). In the meantime there is a solid, well covered dividend.
$NXR are a substantial holding for me and I am happy to hold.
Norcros (LON:NXR) definitely comes under my ‘most frustrating holdings’ category alongside IQE (LON:IQE) and Lavendon (LON:LVD)
However, having said that, I remain a holder because the management are demonstrating that they have the ability to buy decent and complementary businesses, which results in top line growth.
As discussed in your article above the business is very cheaply rated and offers a decent income yield, which is well covered.
I take comfort in the fact that Miton have been adding to their existing holding Gervais Williams has an excellent track record in the small cap space. He must agree that the shares are good value at the current price.
The number one strategic aim is to grow revenue to £420m by 2018 – so they are going to have to increase sales by almost £200m. How are they going to do this over such a short period of time? I’d say that this target is near on impossible to achieve – so why did the management set such an unrealistic target I wonder?
I would like to see them diversify geographically and enter markets across Europe. There is an ongoing process of product simplification by major retailers – cutting down on their product ranges and centralising purchasing across different markets, which results in greater purchasing power for the retailers and therefore higher margins for them. This could be an opportunity for suppliers such as Norcros (LON:NXR) to enter new markets. For example Kingfisher (LON:KGF) sell into Europe via Castorama and Brico.
In my opinion patience is one of the most important attributes of being a (successful) investor so I’ll continue to hold Norcros (LON:NXR) and wait the market to re-rate them!
Back in December I saiid
"One point to bear in mind is that the increasingly inept economic mismanagement in South Africa that has put the rand on the skids could very we'll force the SA government to introduce exchange controls that just might leave Norcros unable to repatriate any SA profits that it continues to make. Argentina and Venezuela are two examples;
http://www.americasquarterly.org/content/capital-controlsinvestment-flows-latin-america
Up until now few thought this likely but the recent ministerial reshuffle has caused a rapid rethink of just how bad things could get for business in South Africa.
I don't hold Norcros because of the South African exposure representing such a large part of their recent improved trading. - See more at: http://www.stockopedia.com/content/norcros-pension-problems-112809/#.dpuf"
I see no reasons to be more optimistic about SA today and the U.K. Businesses should be way more buoyant imho given what others are achieving and the macro environment.
Good luck to holders, I can see the attraction but the little man in my head says no
Or maybe Norcros (LON:NXR) is a classic boring and therefore overlooked company and we should be filling our boots.
I'm certainly no expert on Norcros (LON:NXR) but isn't it concerning that UK sales are falling a] despite acquisitions and b] at a time when the housebuilding and construction industries are generally doing OK (I'm happy to be corrected on this). C] Surely there is a danger that the brands they are buying have limited value. Does anyone actually say "I want to own a Triton shower?" I'm having my bathroom redone at the moment and I didn't specify a brand for any aspect of it.
I accept that the premium end of a market brands have value but surely the nondescript mid-market is simply stuck in the middle and vulnerable to being squeezed by design at the top end and price at the bottom end.
[Edit] This last point doesn't stand of course if the brands have value not for the consumer but to the trade?
Hi Roland -
I agree - and basically that why I have hung in there. If I could predict FX rates I would have been sat on the beach a long time ago!!
Regards, Paul
Hi Roland
I have ownded this stock for some time - my holding has gone up and down.
I like this company. In April the trading update said UK like for like revenues were down 2%, while SA was up 15%, but this totally eaten up by the fall in the value of the RAND. They have made a number of bolt on acquisitions, that look like good deals - theses have more than offset the like for like sales fallin the UK.
The pension contribution is also a drag on likely dividends.
Needs the RAND to stabilise and an improvement in the UK market - then the share price will do better.
Hi Paul,
Thanks for your comment. You're right that in the short term, the Rand exchange rate hasn't helped Norcros (LON:NXR) reported results. But I don't usually worry about FX effects, for three reasons:
1. In the long term these movements tend to cancel each other out, but companies only tend to shout about them when the effect is negative. When FX effects boost results, many companies seem happy to take the credit for themselves...
2. They're impossible to predict, IMHO.
3. FX effects are sometimes exaggerated by the requirement to convert trading accounts into the parent company's reporting currency. Larger companies tend to employ sophisticated financial engineering to manage and mitigate currency effects at a local level.
All of which isn't to say that exchange rates can't cause problems, but I think their significant is often overrated.
In the case of Norcros, I'm just happy to know that sales did rise by 15% in SA. With average luck, this should eventually be reflected in profits!
Regards, Roland
Roland,
Thanks for the article and from your SIF portfolio, Norcros (LON:NXR) is also another I hold. Having bought in last November slightly higher than now, my analysis to date has been that there is no published information to suggest any concern regarding the business over the past 6 months, indeed, the last trading update pointed to profits for the year to 31st March (to be announced on the 14th June) being "marginally ahead of market expectations". Given that it seems so well placed on valuation grounds, I am looking to the full year results and trading update to contribute towards a re-rating that seems more than justified. Time will tell if this is the way things will unfold but at present, this looks a good company!
You now have 2 shares with South African exposure. Also you seem very exposed to the housebuilding sector with 3 shares now. I did hold Norcros (LON:NXR) but sold @ 205p when I became concerned about the South Africa element.
Herbie,
Outside the mining sector, I don't see South Africa as an especially big risk (rightly or wrongly). SA revenue is only a minority (c.33%) of Norcros (LON:NXR) sales as well, so a localised downturn shouldn't create an existential threat for Norcros.
I don't plan to add any more exposure to this region, though!
Regards, Roland