SIF February review: Rio Tinto, Standard Life Aberdeen, RM & Redrow

Brexit is making headlines again this week, along with the ‘The Beast From The East’, a Siberian blast which appears to be bringing us another cold snap.
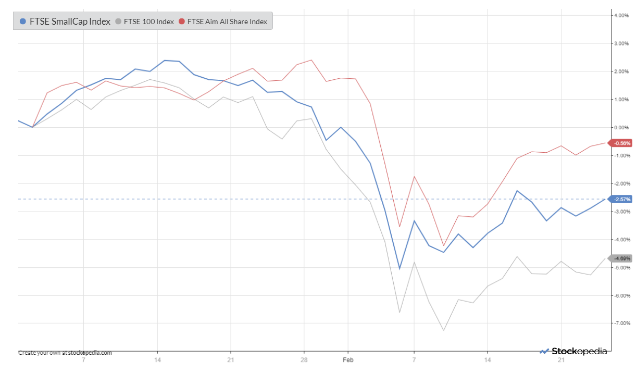
Appropriately enough, the stock market seems determined to ignore both the non-event of winter weather and the major but unknown outcome of Brexit. Instead, the major indices are making a steady recovery from the correction seen at the start of February, as this chart shows:
Several of the SIF portfolio holdings have benefited from this rebound. This includes those which are up for review this week, at the end of their nine-month holding period:
Mining giant Rio Tinto
Asset management group Standard Life Aberdeen
Housebuilder Redrow (held over from previous months)
Educational services group RM (held over from last month)
Here’s how these stocks have fared so far during their time in the portfolio:
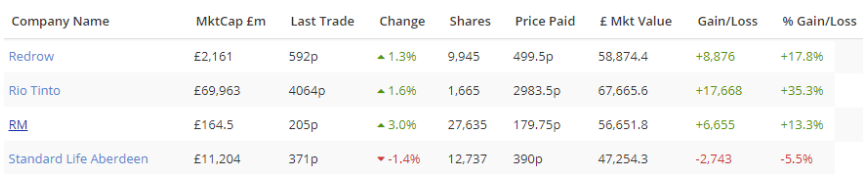
Three of these four stocks are showing profits from their time in the SIF, but only those which still qualify for my SIF screen will be allowed to remain in the portfolio.
Rio Tinto
FTSE 100 miner Rio Tinto has performed well during its time in the portfolio, rising by 35%. As I suggested at the time, the shares were cheap at under £30 in May 2017.
This month’s full-year results confirmed that the business is firing on all cylinders. Underlying free cash flow rose by 64% to $9.5bn last year, providing support for a record dividend of $5.2bn and share buybacks totalling $3bn. (There was also an additional $2.5bn buyback executed with the proceeds from the sale of the group’s main coal assets).
Net debt has fallen to $3.9bn, representing 0.2x underlying EBITDA. So borrowing is no longer a concern. Indeed, the group clearly has the firepower to start expanding again.
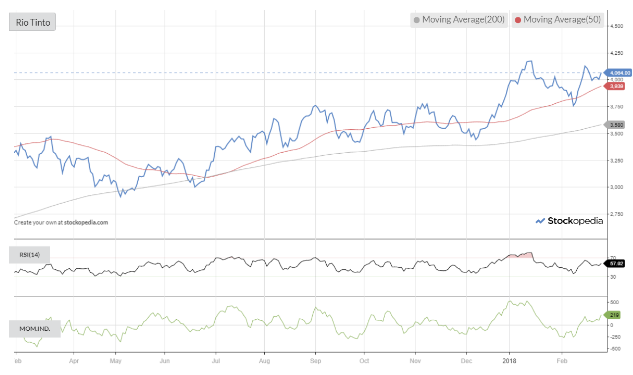
The shares also offer an attractive rolling forecast yield of 4.9%, and the technical picture also looks supportive to me:
What could go wrong? I think it’s worth asking if profitability is already peaking. Rio generated an operating margin of 35% last year. The group’s earnings yield, at 13%, is now higher than when I added the stock to the portfolio. How much higher can these figures go?
A return to expansion could put pressure on margins. The group’s valuation relative to net asset value is also quite high, at 2.2x. Rio now trades at a premium to BHP Billiton (2x net assets) and Anglo American (1.5x net assets). Although I’d argue that the quality and low cost of Rio’s core assets probably justifies this, the group’s profits are still heavily dependent on commodity prices. I’m not sure how much more of a premium can be justified.
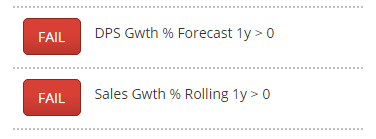
My decision: Analysts expect Rio’s sales, profits and dividend to fall over the next year. And despite a StockRank of 98, this negative outlook means that the stock doesn’t pass all of my screening tests anymore:
I’ll be selling Rio Tinto from the SIF portfolio this week. In the interests of full disclosure, I may retain my personal shareholding, which pre-dates the SIF and is a top 10 position for me.
Total return: +42.4pc
Verdict: Sell
Standard Life Aberdeen
Are the headwinds facing asset management firms stronger than I anticipated when I added Standard Life Aberdeen to the portfolio last year? Perhaps. Certainly the recent loss of a £109bn mandate to manage assets for Lloyds Banking Group was a bitter blow.
The loss (subject to a 12 month notice period) represents about 16% of assets under management, although it’s only said to account for 5% of revenue.
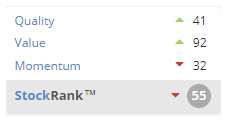
Leaving this aside, Standard Life Aberdeen’s recent results showed few signs of the hoped-for synergies from the merger of the two groups. Pro forma adjusted pre-tax profit fell marginally to £1,039m, while pro forma adjusted earnings were almost unchanged at 28.9p per share. Stockopedia’s algorithms weren’t especially impressed by the figures either:
The merged group’s start in life may have been made more difficult by net outflows of £31bn, some of which were triggered by former clients of both firms who didn’t want to put all their eggs in one basket.
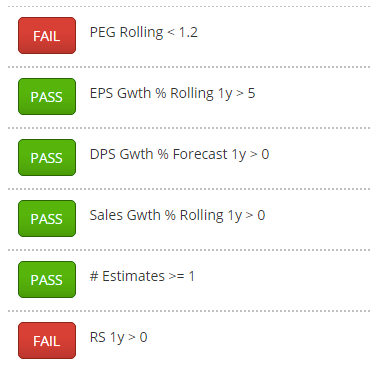
My decision: Things may improve. The forecast valuation looks undemanding, on around 12.5 times earnings and a 6.1% yield. However, weak earnings growth and a poor share price performance mean that Standard Life Aberdeen no longer passes all of my screening tests:
As a result, this stock will exit the SIF portfolio and my own this week.
Total return: 0pc (-5.5pc share price and +5.5pc dividends)
Verdict: Sell
Redrow
Housebuilder Redrow has now reached its first anniversary in the SIF portfolio. But this FTSE 250 firm continues to pass all of my screening tests. It remains a top-ranked stock, with a StockRank of 97 and Super Stock status.
Redrow also qualifies for no fewer than 11 of Stockopedia’s Guru Screens, placing it in joint third place in the top screened list.
February’s interim results confirmed that the business is still performing well. Legal completions rose by 14% versus the same period in 2016. Earnings per share were 27% higher, while return on capital employed rose from 23% to 25%. The interim dividend was increased by 50% to 9p per share, validating my hope that stronger cash generation would support more rapid dividend growth.
My decision: The business of housebuilding is heavily political. But this may be a situation where investors should keep dancing while the music is still playing. Although the shares have now fallen by more than 10% from their January high, Redrow will stay in the SIF portfolio for at least one more month.
Total return to date: +21.2pc
Verdict: Hold
RM
In my comments on education group RM last month I noted that keeping it in the portfolio for an extra month would give us “a chance to see how the 2017 figures affect RM’s StockRank and financial metrics”.
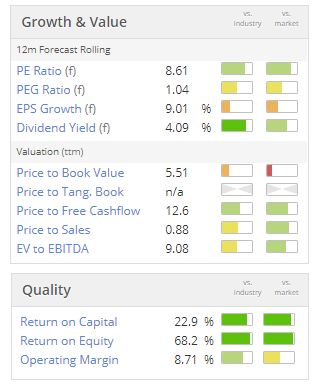
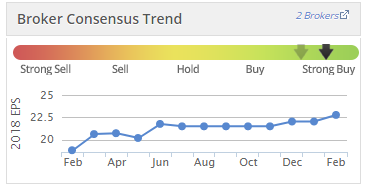
Those figures received a positive reception and the group’s shares have continued to rise. RM’s StockRank is unchanged at 98 and the shares continue to look good on all counts, in my view:
Unfortunately, the increase in borrowing required to fund last year’s acquisition of Connect Group’s Education business has affected the stock’s fundamental health score (F-Score). This has fallen from 7/9 pre-results to 5/9 today, below my minimum score of six.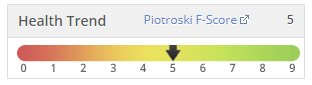
My decision: RM no longer passes my screening tests and so will be sold from the portfolio this week.
Total return: +14.3pc
Verdict: Sell
Once again I have run out of space to cover this month’s International SIF purchases. Apologies for this! I will add February’s stocks to this (virtual) portfolio this week and update you on my choices in next week’s article.
Disclosure: Roland owns shares of Anglo American, Connect Group, Rio Tinto, RM, Redrow and Standard Life Aberdeen.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

2 comments
Hi Melvyn,
You can see the screen I use for the SIF here:
https://www.stockopedia.com/screens/stock-in-focus-screen-113218/
Regards,
Roland
Hello Roland,
Very good article, is there anyware on the website that shows your SIF screen parametres.
Regards
Melvyngd