Super Stock Rio Tinto could be cheap after recent falls

Big cap mining stocks have been among the biggest fallers in the FTSE 350 so far this year. That’s not entirely surprising after last year’s gains, which saw the value of FTSE 100 giants Rio Tinto and BHP Billiton double in twelve months. Smaller companies delivered even bigger gains.
Some reaction was always likely, especially as the first part of the year has also seen the price of iron ore and coal fall. However, the big miners remain among the top-ranked stocks in the Stockopedia universe.
Rio Tinto is a case in point. With a StockRank of 98, Stockopedia’s new rating system classifies it as Adventurous and a Super Stock.
If you haven’t already checked out Stockopedia’s excellent new rating system, then I recommend you do now. There are two parts to the new classifications -- the RiskRatings (e.g. Adventurous) and the StockRank Styles (e.g. Super Stock).
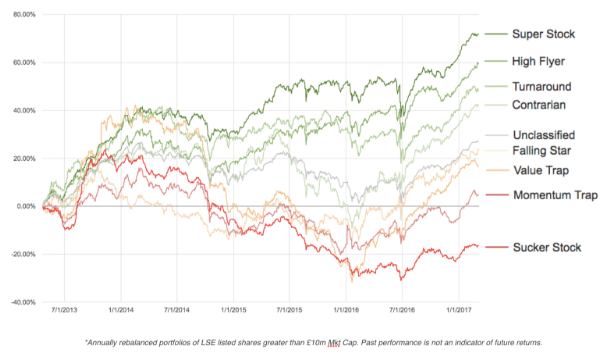
Super Stocks are statistically most likely to outperform, according to Stockopedia’s historic data:
Adventurous stocks also tend to do well:
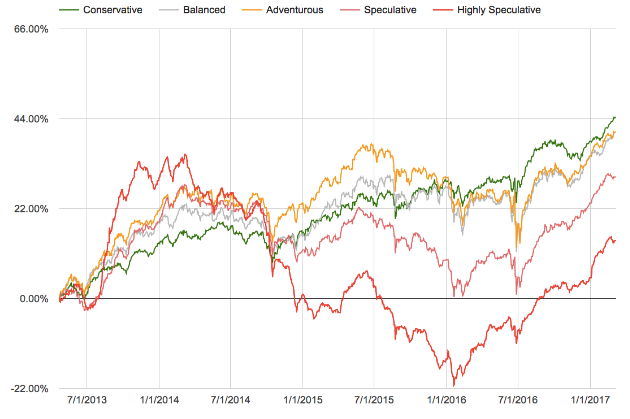
So in my view, it’s worth paying attention when a stock ranks this highly and falls into your potential buying universe.
This week’s new screen stock
If you pay close attention to the stocks that qualify for the Stock in Focus screen, you may be about to point out that Rio Tinto doesn’t currently qualify for the screen. Technically, you’d be right. Rio fails the screen checklist on one count:
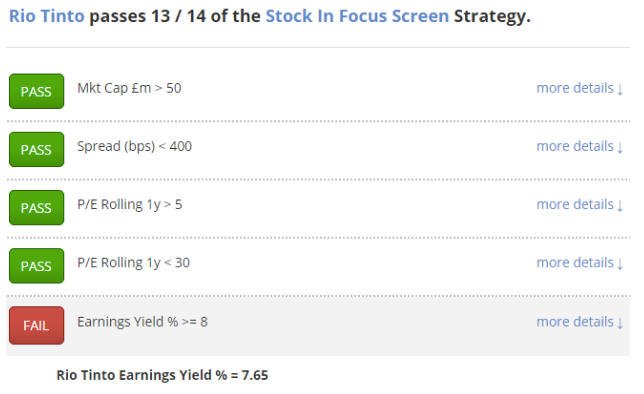
Earnings yield is a metric that was popular with US value investor Joel Greenblatt, who defined it as EBIT/EV in his excellent book, The Little Book That Beats The Market. I like earnings yield a lot because it offers a combined snapshot of profitability and valuation, factoring in both equity and debt capital.
In this case, we can see that Rio Tinto’s earnings yield is tantalisingly close to my screening threshold of 8%. So I decided to take a closer look. I stuck with Stockopedia’s enterprise value of £65.15bn, but I used Rio’s reported operating profit from last year of $6,795m in place of the Thomson Reuters datafeed figure of $6,471m. Doing this gives an earnings yield of 8.1%.
Having tweaked the numbers to allow Rio Tinto to qualify for the SIF portfolio, should I add the stock to my holdings this month?
Does cash generation = value?
Remarkably, Rio Tinto’s ValueRank of 80 is the lowest of the miner’s three ranks. On paper at least, this stock appears to have few weak points.
A closer look at the numbers shows that the stock’s ratios reflect last year’s rapid return to profitability:
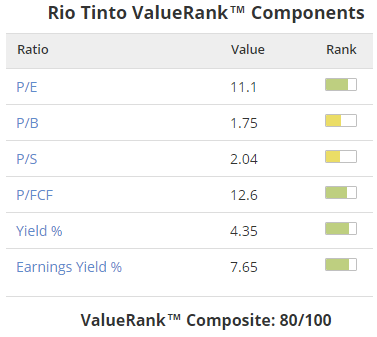
Rio Tinto is no longer a book value bargain as it was last year, but the benefits of the firm’s aggressive cost cutting and last year’s stronger commodity markets are clear. Rio reported post-tax cost savings of $1.2bn last year, outweighing the $0.5bn impact of lower commodity prices.
The stock now trades on just 12.6 times trailing free cash flow, with a trailing yield of 4.35%. These two figures together suggest to me that decent value is on offer.
Fundamental quality
Rio Tinto’s QualityRank of 87 seems fairly reassuring. In fact, the mainstay of this score is the stock’s Piotroski F-Score of eight out of a possible nine. Rio Tinto’s other quality factors are really pretty average:
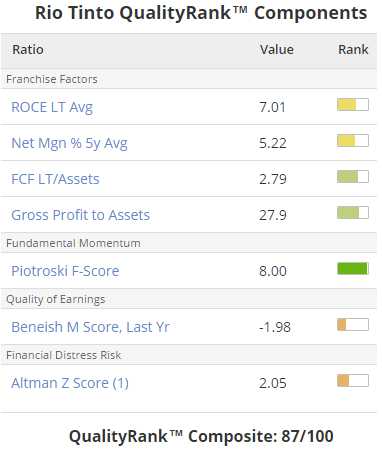
The F-Score is heavily weighted in the QualityRank calculation because it provides a good snapshot of a company’s financial health. Looking at the other factors, Rio’s franchise factors, which essentially measure its profitability, are acceptable but uninspiring.
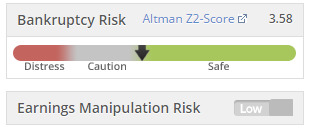
The Beneish M-Score and Altman Z-Score appear poor on the QualityRank breakdown. However, they’re not low enough to cause concern according to the StockReport:
Essentially, Rio Tinto’s appeal is that it can produce large quantities of high quality and low cost iron ore. It’s almost impossible to imagine a scenario where Rio’s iron ore production won’t find a buyer and cover its costs.
The group’s other assets, such as aluminium and copper, don’t have such extreme cost advantages. But they do have decent scale and are all profitable at the EBITDA level. So the worst that’s likely is that they will dilute the profit margins of the iron ore business.
In my view, the only real risk for shareholders is that management will return to its spendthrift ways, and repeat the mistakes of the past. However, with the mining recovery little more than a year old after a five-year decline, I think it’s too soon to start worrying about this.
Strong earnings momentum
Rio Tinto shares have fallen by 17% from February’s closing high of 3,679p. However, this fall hasn’t been matched by cuts to broker forecasts, which have actually risen slightly over the last three months.
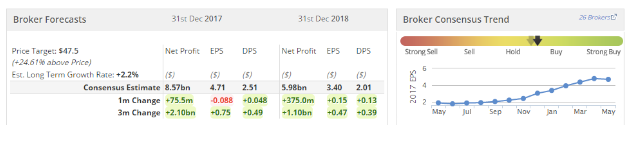
It’s fair to say that Rio stock is cheaper than it was in February. Why might this be? One possible reason is that brokers have pencilled in big reductions in earnings across the mining sector in 2018. Presumably they expect commodity prices to fall and costs or currency headwinds to increase.
Despite this, it’s worth noting that 2018 forecasts have increased over the last three months. Clearly the outlook is improving, as far as anyone can tell. This upward trend is likely to provide future support for the shares, in my view.
Although Rio’s MomentumRank has fallen recently, it remains high:
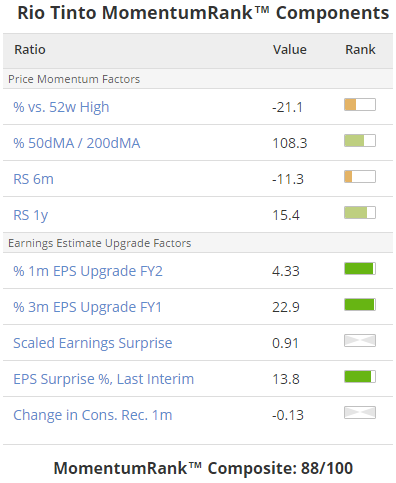
The MomentumRank is being supported by a strong and improving outlook for earnings. I’m prepared to overlook the recent share price weakness on the ground that the stock looks increasingly affordable.
Current forecasts give the stock a P/E of 8.1 for 2017 and of 11.2 for 2018. The firm’s new dividend policy means that payouts will vary with earnings, with the firm targeting a payout ratio of 40%-60% of underlying earnings over the cycle. That’s a splendidly vague commitment in my view, but as things stand the stock is expected to yield 6.6% this year and 5.3% next year.
On the basis that Rio looks affordable and that earnings momentum is still improving, I’m going to add Rio Tinto to the SIF portfolio this week. This stock is already one of my largest personal shareholdings so I won’t be buying more, but I do plan to continue holding.
As always, I’d welcome your views. Has the mining recovery already run its course, or am I right to hold on for more?
Disclosure: Roland owns shares of Rio Tinto and BHP Billiton.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

6 comments
Great report!
Besides the information provided by Stockopedia, I had a look at the 2016 annual reports of the four big names in Metals & Mining (Rio Tinto, BHP Billiton, Vale and Anglo American) in order to see diversification of revenue sources - just trying to avoid a pure bet on iron ore price development.
From that, Vale looks most vulnerable (74% of total net operating revenues coming from ferrous minerals operations, 57.4% from iron ore). Rio Tinto comes up with a pretty similar picture: 46.9% of consolidated sales revenues from iron ore business.
Anglo American and BHP Billiton show a more diversified picture and should be less dependent on iron ore price development (if commodity prices do not correlate too much).In contrast to the others, Anglo American has a significant revenue source coming from diamonds (De Beers), while BHP Billiton generates a 22% revenue share from petroleum business (e.g. shale oil).From that point of view, my personal favorite would be BHP Billiton due to good diversification - but not at the current share price. ;-)Other questions to be clarified: which one has best cost control (= most efficient operations), distribution networks/ client structure, debt load.
By the way: is there any chance to pull out such information from Stockopedia?
I was on the point of selling until I read this article. With the jury still out, I am suspending Rio`s execution!
Worth waiting on the down trend to reverse first which has not happened yet for RIO or BRWM for that matter..
Clearly the 50 day MA is on the wrong side of the share price.currently so a waiting game for an entry point in my view because it is undervalued currently and sooner or later it should reverse direction.
Perhaps SOLG is a good example of the 50 day MA in the right place at the right time.
Hi Roland,been watching Iron Ore for a while now for an entry into miners via BRWM around 14 % discount to nav.$60 on the Iron Ore price was a target for my 1st scale in( looked a good entry on the charts).May well be to early on my first tranche bearing in mind the sector is down trending.
Iron ore (62% Fe) has fallen from $87 a month ago to $59.5 and has dropped 2.8% in the last 24 hours. I'm keeping my powder dry for now.
Zoiberg,
Time will tell, you could well be right!
Although I think it's interesting how broker forecasts do not seem to have been tracking the price of iron ore lower. Will earnings prove more resilient than expected?
I'm going to suspend judgement until Rio Tinto (LON:RIO) H1 results are published in August.
Regards,
Roland