SIF Folio: Staffline blames Brexit for profit crash but are there other issues?

I had a very interesting time at Mello London last week. But my Friday morning didn’t get off to a great start when SIF stock Staffline (LON:STAF) issued a massive profit warning.
This week I’m going to look at what’s happened to this blue collar recruitment specialist and what I’m going to do next. I’ll also include some brief notes on a few of the companies I saw present at Mello.
STAF blames Brexit
Staffline rolled out the excuses on Friday, slashing 2019 profit guidance by nearly 50%. The shares are now down by about 60%:
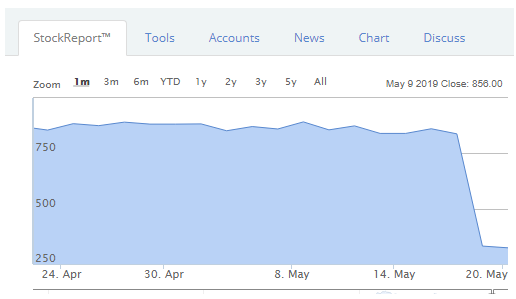
The firm says that Brexit uncertainty has caused employers to shift a large number of temp staff into permanent roles. Although this may be good news for the employees themselves, it’s bad news for Staffline, which has lost a significant number of lucrative temp contracts.
The company says that many of these ‘temp-to perm’ transfers have been in the “higher margin driving sector”. That makes sense to me. The UK is said to have a shortage of lorry drivers. According to one press report I’ve seen, about 60,000 drivers employed by British firms are from Eastern Europe. Putting them on permanent contracts is presumably a measure designed to enable them to remain after Brexit.
Is a cash crunch possible?
I was much more concerned by the second item in Friday’s update. This warned of “a slowdown in new contract momentum” which management attribute to the delayed publication of the firm’s 2018 accounts.
As Paul commented on Friday, it seems odd that companies wouldn’t sign up a temping agency because its accounts were delayed. However, I can see that clients might avoid signing new contracts if they were concerned that Staffline might be facing problems. This is purely speculation on my part, but I wonder if there’s a risk of a cash crunch here.
On Friday, an updated broker note on Research Tree suggested that full-year net debt could hit 3x EBITDA in 2019. I don’t know what Staffline’s banking covenants are, but I wouldn’t be surprised if this was close to the limit of what the firm is allowed to borrow. It’s certainly above my preferred maximum of 2x EBITDA.
This firm has historically been a cash generative business:
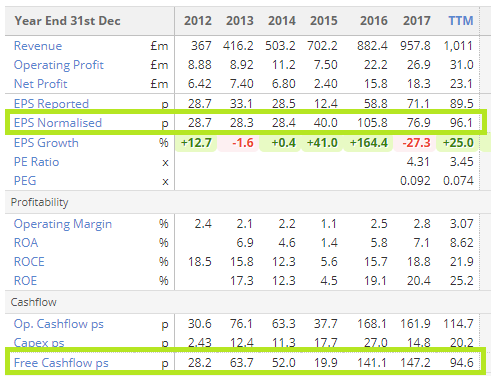
However, it also needs a lot of cash. Blue collar agency workers tend to get paid weekly, but my calculations show that Staffline’s clients take about 46 days to pay their bills, on average.
As one experienced investor suggested to me last week, if any of Staffline’s major clients delayed payments to ease their own cash flow problems, Staffline’s own cash position could quickly become stressed.
My decision
I could continue to investigate Staffline, but I’m not going to. I was wrong to give the firm the benefit of the doubt after the suspension earlier this year.
In six months, we’ve had £20m of unexpected exceptional costs, a historical accounting issue and a share suspension. These have been followed by a profit warning that’s cut earnings forecasts for 2019 by nearly 50%.
The firm’s most recent set of accounts date from 30 June 2018 -- nearly a year ago. Given all that’s happened since then, I’d argue that these accounts are of very little use in gauging current trading or understanding the group’s financial position.
Friday’s profit warning came just two weeks after a 30 April update which made no mention of 2019 trading falling below expectations. What happened during those two weeks?
My new rule on profit warnings means I must sell these shares immediately. This will mean taking a painful loss, as the SIF fund’s holding is down by more than 70%. My own holding is down by a similar amount. However, I’m confident it’s the right thing to do. Holding on for a recovery would be pure speculation.
They say that experience is what you get when you didn’t get what you wanted. Unfortunately, that’s what’s happened here.
I will sell Staffline shares from the SIF fund and my own portfolio after this article has been published.
Verdict: Sell
Total return: -74pc
Mello highlights (CTO, CCT, ZOO, CPP, MMH)
In the remainder of this piece, I want to take a quick look at some of the companies I saw present at Mello. This event gives private investors a rare opportunity to get direct access to executive management at good quality companies.
Alongside this, there are also presentations from top fund managers and other notable investors such as Lord John Lee, plus plenty of opportunities for networking. It was a terrific event and I certainly plan to go again.
T Clarke (LON:CTO) - I discussed building services contractor T Clarke in my piece last week. The firm’s presentation at Mello confirmed the appeal of this business, which has been trading for 130 years. Chief executive Mark Lawrence started as an apprentice 33 years ago, and the firm prides itself on its employed workforce, with 80% of work done in house.
The group sees data centres and smart buildings as major opportunities for expansion. It’s worked on a lot of major commercial and public sector projects and says 80% of revenue is repeat business.
A cash-rich balance sheet and (mostly) unused debt facility provides the headroom needed to fund projects such as data centres, where large upfront purchases of materials are required. Not all rivals can afford this.
Margins are rising steadily and I think there’s a lot to like at this specialist firm. Cyclical risks are my only major concern, but the shares remain a potential buy for SIF.
Character Group (LON:CCT) - this toy manufacturer and distributor is best known for holding the Peppa Pig franchise, but also produces a wide range of other branded toys. Character is an existing SIF holding and the presentation confirmed my positive view of the company and its management.
I was particularly impressed by the firm’s conservative approach to its finances, with no debt and freehold property.
One interesting comment was that the firm is “losing boys earlier”, at about age eight, as a result of computer games. Despite this, management remain confident of growth and are pursuing new online marketing strategies, including producing short-format videos.
Zoo Digital (LON:ZOO) - I know this is a popular one with subscribers. The shares have popped following Zoo’s appearance at Mello, where the founder gave a well-attended presentation.
The business model essentially seems to revolve around bringing a capital light, gig economy model to the market for television/film dubbing and subtitle services. Instead of running its own studios, it has a computer system that allows actors to work remotely in their own facilities/adapted spare rooms.
The key advantage for Zoo’s clients is said to be speed, more than cost -- the company isn’t aiming to undercut the market as this could be self-defeating. In my view, a lot depends on the success of the newish dubbing service. I see the stock as fully priced for now, although with plenty of potential.
CPP Group (LON:CPP) - I felt that the firm’s turnaround is still unproven. Profits are being supported by the UK legacy business, which is in managed decline as part of its agreement with the UK regulator. Margins on newer ventures are much lower, albeit with the potential for strong growth.
Marshall Motor Holdings (LON:MMH) - I was impressed with the evolution of the business since 2008 and comfortable after talking to management. The firm’s argument is that PCP sales lock new car and (increasingly) used car buyers into regular vehicle replacement cycles and high margin dealer servicing.
However, we’re in a downcycle for new car sales and the firm admitted that it has seen some slippage from new to used sales. I’m not sure if now is the right time to buy.
As always, these are only my personal opinions. Please do your own research before making any trading decisions.
Disclosure: At the time of publication, Roland owned shares in Staffline and Character Group.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

11 comments
Yes, but the point is, it does not seem to explain a downturn in current year revenues and profits which should receive a boost from the placement fees, whatever the long term effect.
I think perhaps people may also be under estimating legislation that is being brought in by the Govt in 2020 for private contractors, and the measures companies and agencies have to go through to prove to the Revenue they are not in effect disguised employees.
Whilst this should not in principle technically affect temps hired through agencies, agencies in their t&c's will usually try and pass on the risk of any tax liability to the employer, so there is reduced benefit to companies, and increased risk, so it may be easier in a tight market just to employ those people directly.
Ouch after bilby, although those shares seem to be improving
Hi Andrew,
Indeed, I seem to be suffering a bad streak at the moment with Bilby (LON:BILB) and Staffline (LON:STAF)
I guess what this does show is the value of diversification and position sizing. Even though I closed SIF's Staffline position at a 74% loss, this only represented a hit of about 3% to the whole portfolio.
SIF positions are sized to allow for 20 stocks. Although I've been below this target for a while now, I'm happy I've maintained this sizing discipline and allowed the cash balance to build.
Best,
Roland
Hi roland,
We all have those times. I was tempted into the falling knife syndrome and bought in with bilby close to bottom when they hit 25p going against all of my rules. However it worked out somewhat as
I sold out today at 46p , but still licking my wounds .
Like your blog very much and good luck for the future
Hi Andrew,
Thanks and congrats on Bilby (LON:BILB), good timing!
Roland
I'm afraid that I feel the writing has been on the wall with Staffline (LON:STAF) for quite some time, with one catastrophe after another as well as lacklustre trading results. I much prefer Pagegroup (LON:PAGE) (I hold) which has recently made a positive trading update and, I feel, has a much more global presence.
I have held Marshall Motor Holdings (LON:MMH) for a long time, though I have traded in and out and my current holding is residual. I feel they are the best of the bunch, but at the present time I think trading is very tough and now is not the right time to accumulate any more.
When a contract worker takes a permanent job at the company they are working for there is usually a commission paid to the agency. Most employment agencies welcome this, it's quite lucrative for them.
Hi Blissgull,
That's interesting, thanks for highlighting this.
Roland
This is true but on the downside - It's a one off !
Revenue from a one-off perm placement is multiple of temp revenue. As such this year should have seen a bump in perm revenues with the obvious drop in future temp revenues. Also, perm revenues are free from any other COGS, so revenue hits GP, pound for pound (after sales commissions). With this in mind, I am scratching to marry up their excuses with the 50% profit downgrade. I think there are more profit (potentially cash) warnings down the line.