SIF Folio: Synthomer could be too cheap

FTSE 250 chemicals group Synthomer (LON:SYNT) describes itself as “one of the world’s foremost suppliers of aqueous polymers”. The firm’s polymers are used in the production of products including adhesives, carpet, paint and -- of course -- latex gloves used in healthcare.
Sales of such nitrile butadiene rubber (NBR) products have rocketed during the pandemic. Operating profit from Synthomer’s Performance Elastomers division rose by 800% to £209m during the first half of 2021, compared to the same period in 2020.
This surge in demand has somewhat distorted the company’s financial performance. But the City consensus view seems to be that much of this growth will be retained to form a new baseline for sales.
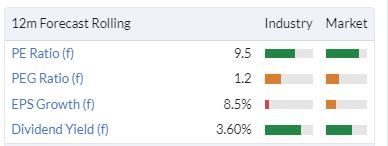
If this view is correct, Synthomer shares look potentially cheap to me, on 10 times rolling forecast earnings.
Synthomer published its interim results last week and the shares now qualify for my SIF stock-buying screen. This seems to support my view that this stock could offer the kind of affordable growth I’m looking for. This week I’m going to take a closer look at Synthomer to decide whether to add the shares to SIF and my personal holdings. (For a quick summary of how I run the rules-based SIF virtual portfolio, click here.)
Synthomer (LON:SYNT)
Before I look at the numbers, I think it’s worth understanding a little more about Synthomer. This business produces specialist polymers that are used by clients in a wide range of industries. You can see an overview of all the markets served by Synthomer here.
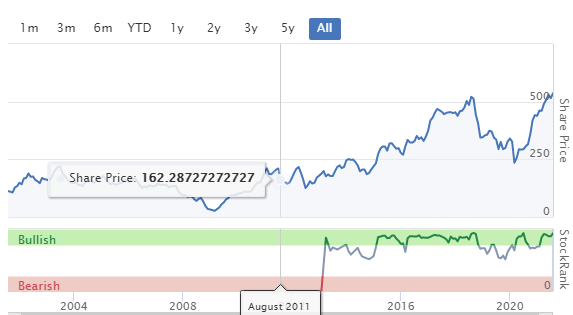
The business can trace its roots back to 1863 and was previously known as Yule Catto. This business had ties to rubber and oil plantations in Malaysia. This link remains today - plantation owner Kuala Lumpur Kepong Berhad has a 21% stake in Synthomer. The shares have tripled over the last 10 years, providing attractive returns for long-term holders:
In 2020, Synthomer decided to scale up with a £654m deal to acquire rival Omnova Solutions. The transaction was funded with a £204m rights issue and new debt, leaving the group with leverage of 2.5x EBITDA. Strong cash generation - and the Covid-19 profit surge - means that this leverage ratio is now down to 0.8x EBITDA.
The company hasn’t broken out the revenue and profit contribution made by Omnova since the acquisition completed in April 2020. This means we can’t get an idea of the split between acquired growth and organic growth. However, management have said that Omnova’s performance is currently ahead of the acquisition investment case.
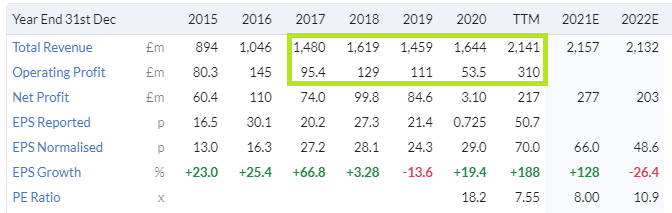
Revenue growth has certainly improved since the Omnova acquisition, as I’ve highlighted below. The trailing 12-month (TTM) numbers also reflect the H1 2021 boost provided by Covid-19 demand. Interestingly, these numbers do seem to suggest that performance was stagnating somewhat before the acquisition:
One final point of interest is that Synthomer is about to get a new chief executive and a new chief financial officer. Both departures seem to be orderly and amicable, so I don’t see any concerns. But history suggests that if there are any hidden problems with Omnova or any other part of the business, we’ll find out about them when the new boss takes charge in November.
Growth outlook: Looking ahead, profits are expected to return to more normal levels in 2022, after the Covid-19 boost. However, Synthomer expects the underlying NBR market to keep growing by at least 10% each year over the longer term. Management cite the “hygiene megatrend” and growing emerging markets demand.
To capitalise on this apparent structural growth opportunity, Synthomer is currently adding 200,000 tonnes of new NBR manufacturing capacity in Asia.
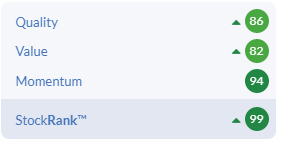
So far, I have a favourable impression of Synthomer. Stockopedia’s algorithms like Synthomer too, awarding the stock a near-perfect StockRank of 99:
Let’s take a closer look at the numbers.
Value: Peak profits?
Synthomer’s ValueRank of 82 suggests the shares could offer good value. They score well on most counts:
Trailing P/E: 7.6
Trailing P/FCF: 12
Trailing dividend yield: 3.3%
Earnings yield (EBIT/EV): 11.6%
Balance sheet: There are a couple of points I’d like to make about Synthomer’s balance sheet. These are highlighted by the TTM valuation metrics:
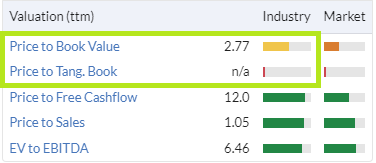
Synthomer stock trades on a price-to-book value ratio of 2.8 and its tangible book value is negative. Looking at the balance sheet, I can see several reasons for this:
£163m pension deficit
£355m net financial debt
Goodwill and acquired intangible assets totalling £799m. Stripping out these and other intangibles leaves the group with a NTAV of -£17.3m
I’d prefer to see a little more asset backing here. But given the group’s modest gearing and solid cash flow and profitability, I’m not too concerned.
I think a more important question to ask is whether Synthomer looks cheap because the current level of profitability is unsustainable. It’s certainly true that management and City analysts expect profits to fall next year. That’s a risk. But as I’ll explain, I think the company’s quality and momentum metrics could justify the current valuation.
Quality: Back on track?
Synthomer’s QualityRank of 86 looks promising, but the company’s performance has been a little mixed since 2015. Margins and return on capital have varied from year to year.
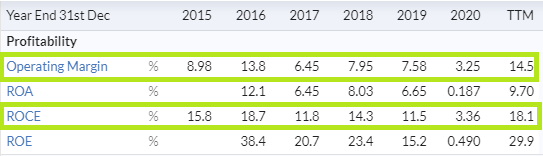
Without further research, I’m not sure of the reasons for this varying profitability. This might be worth investigating in more detail, to understand the dynamics behind the company’s mixed performance in recent years.
I’m not going to do that here - my rules-based approach involves a certain amount of tactical ignorance. But I am reassured to see that the trend appears to be improving. This is emphasised by Synthomer’s high Piotroski F-Score:
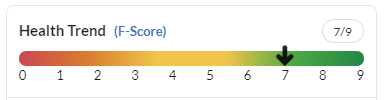
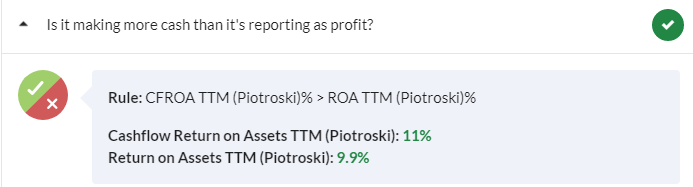
The F-Score looks at a number of metrics relating to profitability, cash flow and leverage. To pass each test, a company must show an improvement relative to the same period last year. I find the F-Score a very useful tool - you can see full details of a company’s results by clicking on the F-Score link. Here’s an example:
On balance, I’m comfortable with Synthomer’s quality metrics, given the positive outlook for the business.
Momentum: a top score
A MomentumRank of 94 suggests a strongly positive outlook. Broadly speaking, I think that’s a fair view of the situation here. As usual, let’s split Synthomer’s momentum into its constituent parts.
Price momentum: The shares have risen by 80% over the last 12 months:
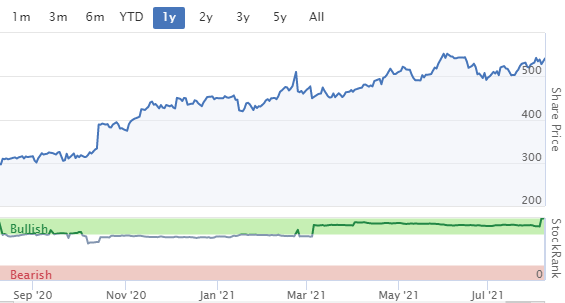
Synthomer stock continues to display positive relative strength characteristics and show strong volumes:
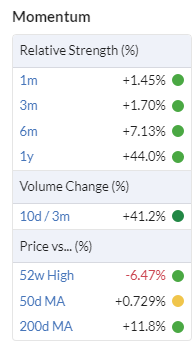
Positive relative strength over 6m/1y is generally seen as a good leading indicator of medium-term performance, according to Stockopedia research.
Earnings estimates: We know that profits are expected to fall next year. Broker consensus currently suggests that earnings will be around 25% lower in 2022:
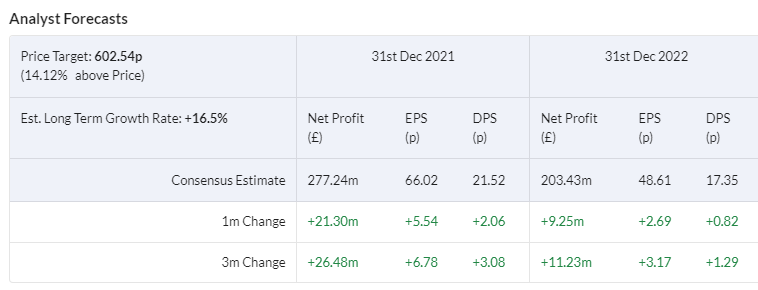
However, based on 2022 forecasts alone, Synthomer is still only trading on 11 times earnings, with a 3.3% yield. That doesn’t seem excessive to me for a profitable, specialist manufacturer.
My main concern is that I can see a lot of moving parts that could affect performance over the next 18 months. I don’t think the net effect of these changes will be easy to predict:
Organic growth
Omnova contribution
Covid-19 contribution
My decision
I’m not sure how confident we can be in broker forecasts for Synthomer. My feeling is that there’s a higher-than-usual chance the business could outperform (or underperform) over the next 12 months.
Despite this, I can see a lot to like here. The core business appears to be reasonably profitable and cash generative. The group’s leverage is not excessive and cash generation is generally good.
Omnova appears to be making a positive contribution, ahead of schedule. Meanwhile, bumper profits from Covid-19 sales are helping to repay debt from this deal more quickly than planned.
Synthomer stock passes all of my screening tests and looks affordably valued on a 12m forecast view.
For these reasons, I’m going to add Synthomer to the SIF Folio and my own holdings this week. As always, I’ll execute these trades after this article has been published.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

17 comments
I would just take care here about raw material costs.
Think monomers. The building blocks for the polymers they make. Oil price driven.
No position myself
But that will affect many companies, won't these just get passed on to the buyers? Unless there are cheaper alternatives.
Chemicals are very cyclical though, it could be approaching a peak soon.
That’s a fair point. The competition will be using the same monomers. However, margins are pretty thin in this business and so any failure to sell a full price increase can have a large impact. It’s also going to depend on what their contracts with the monomer suppliers are like. Just thinking that, if I was holding this share, I would be a bit nervous about that.
Blimey there's a good following for Synthomer (LON:SYNT) here on Stocko... on the community rating, its got a 58% Buy, which is one of the highest I've ever seen for a share (normally its in the 10% to 25% Buy range).
Hard not to like. Great stockrank. Broker forecasts are at a 6-8x PE ratio.
Marshall Motor Holdings (LON:MMH) is 65% but it does not mean 65% of subscribers hold it.
Agree with analysis
Hi Roland,
Where did you get SYNT from as I cant see it in your SIF screen or your relaxed screen.
Best wishes
Melvyngd
Hi Melvyngd,
Good question! Synthomer (LON:SYNT) has been dipping in an out of the screen recently, but when I used the Tools/checklist facility on the StockReport on Monday (9/8) to check if the stock was compliant it passed all tests. The only borderline variable was the PEG ratio which was exactly on my limit of 1.2.
However, the situation has since changed. The rolling PEG ratio shown by Stocko has risen to 1.6. As the share price has been steady this week, I'd guess this change relates to the impact of the H1 results being processed by Stocko's algorithms.
For me, this doesn't matter - a stock only has to qualify at the time my article is published. I'll then add it to SIF and hold for nine months unless it warns on profits.
Hope this all makes sense, happy to answer any other questions that crop up.
Regards,
Roland
(Disclosure: I hold Synthomer)
Thanks for the information, I did buy anyway so I will wait and see.
.
Best wishes
Melvyngd
Synthomer (LON:SYNT)
Read what you like in charts. Good uptrend halted in 2019. Has picked up to where it was so 500p could be a new support to reach 600p. Sorry about the CCI I'm still working on how useful it is. The MACD though says we are in high territory - at the moment.
Synthomer (SYNT) I also bought last week after great h1 results. Based on H1 producing £322m EBITDA & £254m nett profit, with the company forecasting £500m+ EBITDA for full year 2021, my estimate of nett profit for the full year 2021 is over £400m. Whilst demand for nitrile butadiene rubber for PPE has been boosted by Covid, stockpiling and stock replenishing of PPE is not going to disappear in 2022.
Hi Roland,
Good article, echoes my thoughts
Synthomer (LON:SYNT) was brought to my attention in the last StockSlam and it took a week or so to look into it. Having put the numbers from the RNS about forecast EBITDA into my calculator it looked like a PE of around 6 which I agree is far too cheap compared to its competitors. Much is said about reducing demand but in the recent HY results the Co says it expects continued growth. Since these HY figures I recast my numbers on a slightly reduced growth curve only to find a PE rising slightly but still under 9. Stocko's figures for PBT still look too low.
Good acquisition plus organic growth plus growing dividend added to reducing debt and reducing pension deficit makes this stock a good medium term buy - or keep buying if you already hold.
Please keep on producing these excellent articles Roland
Steve
snap roland i thought the same as you i bought this morning
I'm new here. What is the SIF Folio and where can I see that?
Reassured you are buying. I bought myself last week. There are so many uses for synthetic rubber that even though the COVID bonus is a one off, there is also an argument that other uses will benefit beyond covid recovery. That along with the fundamentals was good enough for me. Not easy to find such quality at such a reasonable price these days.
Hi Bronstein,
I run the SIF portfolio as a Folio in my personal Stockopedia account. I include a snapshot of all positions in my monthly review - you can see the last one here:
https://www.stockopedia.com/co...
Regards,
Roland
Thanks Roland - great insights. I see Hon Hai Precision Industry Co in you SIF, do you have a view on this business?
Hi Andrew,
I understand that Hon Hai Precision Industry Co (LON:HHPD) is the formal name for electronics group Foxconn - a major supplier to Apple, among others. However, the UK listing is a secondary listing - the company's primary listing in Taiwan.
I'm afraid it's not a business I'm familiar with, as I don't generally invest in overseas stocks in SIF.
My SIF buy screen doesn't explicitly exclude dual listings, as there are some I will consider, typically those with listings in two western markets (e.g. UK/EU or UK/US).
Regards,
Roland