SIF March review: Taptica International, Harvey Nash, IAG and Redrow

We’re getting close to the end of the tax year, and to the SIF portfolio’s second year of trading. To mark this anniversary I’ll be considering whether to make any changes to the screening rules I use to select stocks.
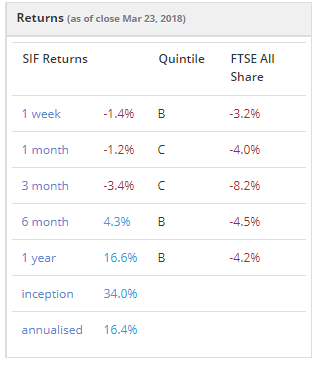
Any changes I do make are likely to be small and incremental. The portfolio has outperformed the benchmark FTSE All-Share index by 20% over the last year, so I’m fairly happy with the way it’s performed:
Profit in uncertain markets
As Graham Neary discussed on Friday, the FTSE 100 has fallen below 7,000 for the first time in 15 months. A deeper correction seems possible at some point.
Like many portfolios, SIF hasn’t yet been tested in a real bear market. I have no idea how it will perform in more difficult conditions, but I do have a view on what I hope will happen.
The portfolio’s focus on affordable growth within a limited holding period means that momentum is also a key requirement for each stock pick. This is likely to be in short supply in a real bear market. So my hope is that in really bad conditions, the portfolio would move progressively into cash as fewer stocks would qualify for my screen.
I’ve seen some evidence to suggest that this could happen, but it’s not conclusive. One aim of my review this year will be to consider whether I need to tweak the screening criteria to move closer to this goal.
This week’s stocks
That’s all to come next month. This week it’s time to review the portfolio holdings that are at least nine months old. There are four contenders:
Internet marketing group Taptica International
Recruiter Harvey Nash
British Airways and Iberia owner International Consolidated Airlines Group
FTSE 250 housebuilder Redrow
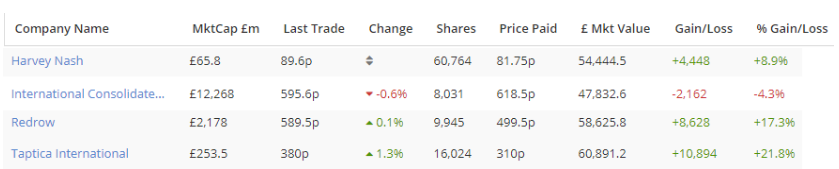
Here’s how they’ve performed so far:
Taptica International
Internet marketing specialist Taptica International has been a strong performer for the portfolio, although the shares are now well below the highs seen over the last nine months.
In January the company said that better-than-expected progress integrating the Tremor Video DSP acquisition meant that 2017 earnings would be ahead of expectations.
These results were released on Monday, giving me chance to take a quick look and to decide whether to keep the stock in the portfolio before submitting this article.
Revenue rose by 68% to $210.9m last year, helped by acquisitions. Profit growth was weaker. Even using the company’s favoured measure of adjusted EBITDA, profits only rose by 33% to $34.2m. The firm’s adjusted EBITDA margin fell from 20% to 16%.
Prior to today’s results, Taptica failed my screen on four counts:
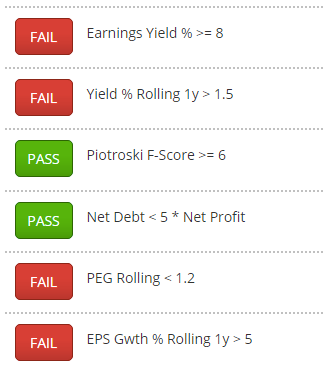
Monday’s guidance is for 2018 to be in line with market expectations. This implies broadly flat earnings, and a forecast yield of 1.35%. These forecasts don’t seem likely to satisfy the four ‘failed’ tests above.
My decision: From what I can tell, Taptica isn’t likely to qualify for my screen when its StockReport is updated with last year’s results. So it will be sold from the portfolio this week.
Total return: 22pc
Verdict: Sell
Harvey Nash
The small-cap recruitment sector looks cheap at the moment. Harvey Nash is no exception, trading on a rolling forecast P/E of 6.8. Although the cyclical nature of the business means that a high rating probably isn’t appropriate, I’m attracted at these levels.
The firm’s recent year-end trading update was fairly upbeat, confirming an expected 22% increase in adjusted pre-tax profit. As Graham Neary pointed out in his review of the figures, this performance may have been flattered by currency movements. But it seems a solid result and I believe last year’s restructuring should support future profitability.
Net debt is modest and the house broker is forecasting EPS growth of around 20% in 2018. The shares also offer a well covered dividend yield of 5%.
My decision: I don’t see any reason to sell at this time. Happily, Harvey Nash still passes all of my screening tests. So this recruitment group will remain in the portfolio for at least one more month.
Total return to date: 11pc
Verdict: Hold
Redrow
In my February review, I commented on Redrow’s recent interim results. These confirmed my view that the company is now starting to produce the high returns and strong free cash flow we’ve seen elsewhere in the sector. I don’t see any reason to sell while market conditions remain stable.
Redrow stock currently has an earnings yield (EBIT/EV) of 16%, double my minimum requirement of 8%. The rolling forecast dividend yield of 4.5% is also very attractive, and earnings momentum still looks strong.
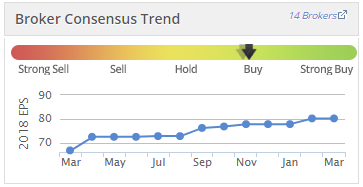
Redrow currently qualifies for 10 Stockopedia Guru Screens, has a StockRank of 96 and is a Super Stock. So if I get it wrong, I’ll be in good company!
My decision: Redrow still satisfies all of my screening criteria, so will remain in the portfolio for at least one more month.
Total return to date: +20.7pc
Verdict: Hold
International Consolidated Airlines Group
British Airways owner IAG’s recent 2017 results showed that operating profit rose by 9.8% to €2,727m last year. However, revenue growth was just 1.8%. And passenger revenue per available seat kilometre (ASK) fell by 1%.
The firm’s revenue seems to have been supported by continued expansion and fuller flights. Available seat kilometres increase by 2.6%, while load factor rose by 1% to 82.6%.
In contrast, I believe profit growth was mostly generated by lower costs. Fuel costs per ASK fell by 7.8% last year, while non-fuel unit costs fell by 1.3%.
IAG’s share price has been broadly flat since it joined the portfolio in June 2017. At that time, I wrote that the stock traded on a trailing P/E of 7.9 with an earnings yield of 14.7%. The firm’s latest results mean that it now looks even cheaper, with a trailing P/E of 6.6 and an earnings yield of 18.1%.
Although the level of competition in this sector could make it hard for airlines to pass on cost pressures through higher ticket prices, this doesn’t yet seem to be a problem. Earnings are expected to rise by a further 8% or so this year, leaving the stock on a forecast P/E of 6.2.
My decision: IAG still passes all of my screening rules and so will remain in the portfolio for at least one more month.
Total return: c.0pc
Verdict: Hold
Next time
I’m quite pleased that my screening rules are allowing me to keep three stocks this month. The trading costs of a high turnover strategy such as this one can be considerable for smaller portfolios. Increasing the average holding period is one way to reduce costs.
I’ll be back next week in search of new stocks for the portfolio and with details of the latest stocks to join the International SIF. Until then, all the best for the long weekend.
Disclosure: Roland owns shares of Redrow, Harvey Nash, International Consolidated Airlines Group and Taptica International.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

1 comment
I like Roland's sentiments.