SIF Portfolio: Norcros looks tempting following recent changes

The outlook for consumer spending and the property market remain wildly unpredictable, if January’s rash of trading updates is anything to go on.
Data from the Office for National Statistics last week showed that retail sales growth by volume slowed to under 2% last year, from more than 4% in both 2015 and 2016. Post-Christmas updates from the supermarkets were fairly solid, but trading statements from other retailers have been more mixed.
Niche firms Carpetright and Bonmarche Holdings (a portfolio stock) have both slumped on falling sales. Graham Neary covered both of these on Friday. At the big cap end of the market, Marks & Spencer did relatively poorly, but Next and Dixons Carphone both did quite well. Budget retailers have also performed strongly.
Although we’ve had a big profit warning from estate agency group Countrywide, we’ve not yet heard from B&Q owner Kingfisher. Nor have we had updated from builders merchants such as Travis Perkins. That’s a shame, because these are probably the nearest proxy to today’s stock, shower and bathroom fitting specialist Norcros.
New-look Norcros returns
Perennial value stock Norcros has often cropped up in my screen, and makes frequent appearances in the SCVR.
However, it’s reached the top spot in my screening results this week, forcing me to take a closer look. The last year has brought some changes I’m keen on, and one or two that I’m not. So let’s take a closer look.
Still good value
Norcros has always appeared to be cheap, and that hasn’t changed. A ValueRank of 86 and a swathe of green bars highlight the firm’s value credentials:
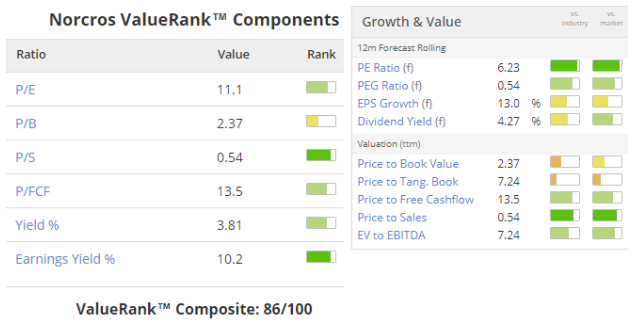
The earnings yield (EBIT/EV) of 10% is well above my screening threshold of 8%. This suggests Norcros could be attractively priced, relative to its capacity to generate profits.
Meanwhile, the trailing price/free cash flow ratio of 13.5 implies that the dividend yield of 3.8% is covered twice by free cash flow. (Inverting the P/FCF gives a free cash flow yield of 7.7%).
However, the £60m acquisition of Irish shower enclosures group Merlyn is big enough to potentially change the picture. So I think it’s worth taking a closer look to see if the price paid for this business is consistent with the valuation shown above, which excludes the impact of the Merlyn deal.
A wizard deal?
As this is such a large acquisition, I think it’s worth asking whether Merlyn meets some of my basic screening criteria, based on the information at the time of the acquisition. Here are some key numbers:
Enterprise value of acquisition: £60m
EBIT/operating profit FY17: £6.4m
The good news is that the £60m price tag for the acquisition equates to an earnings yield of 10.7%. This is in line with Stockopedia’s current earnings yield for Norcros, so I wouldn’t expect this deal to dilute the group’s margins.
One potential concern is that the transaction was funded with £30m of new debt and £30m of fresh equity. What effect will this debt have on the combined group’s debt ratios?
I like to measure net debt against net profit. My screening limit for net debt is five times net profit.
Using the Irish corporate tax rate of 12.5%, I’ve estimated that Merlyn’s £6.4m operating profit last year might have represented a net profit of about £5.6m, excluding interest costs. Adding this to the equivalent Norcros figure of £8.5m, and rounding down, gives us a pro forma figure of £14m.
Norcros had net debt of £20m at the end of September, and the Merlyn deal in November added a further £30m. So I’ve estimated the combined group’s net debt at £50m, which represents 4.5 times trailing net profit.
I should emphasise that my profit figure is a rough estimate. But it seems likely to me that Norcros now has net debt at the upper end of what I’d allow. I’m inclined to accept this, in part because forecast net profit for the year to 31 March is £29.4.m. Even allowing for some adjusting factors, that ought to bring the firm’s debt ratio comfortably below my limit.
What about pensions?
No discussion of Norcros would be complete without mentioning the group’s giant pension scheme. This has assets of around £400m, compared to a group market cap of £150m.
There’s a sizeable deficit, but this has fallen by almost half over the last year and is starting to look quite manageable, hence why I’m considering this stock:
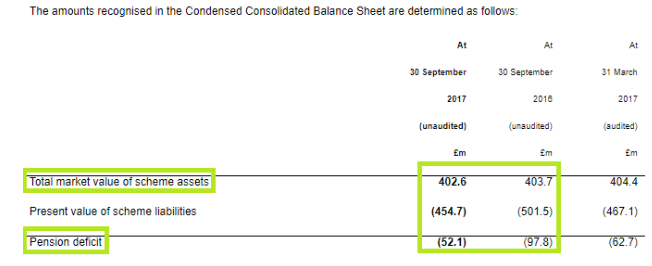
The discount rate used to calculate liabilities has risen from 2.25% to 2.7% over the last year as bond yields have strengthened. This is why the scheme’s liabilities and deficit have fallen. I’ve no way of knowing if this will continue, but with the US Federal Reserve and other central banks now scaling back quantitative easing in earnest, it does seem possible to me that we’ve seen the bottom for bond yields.
On balance, I think the much-reduced deficit looks like an acceptable risk. Norcros expects to contribute £2.5m in reduction payments this year, which also looks tolerable to me.
Quality may be improving
Norcros's QualityRank of 77 is strong and while not quite top notch, doesn’t seem to suggest any real problems to me:
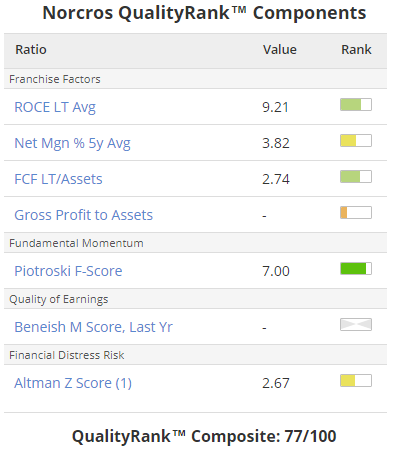
The firm’s growing portfolio of brands such as Triton, Vado and Croydex ought to provide a degree of competitive advantage. I’d imagine that the group’s large distribution network is also useful in trying to take market share from smaller, independent firms (of the type Norcros acquires).
Although the long-term ROCE is fairly average at 9.2%, this figure has risen to 10%-11% over the last couple of years. I note that management also expect a ROCE of more than 13% from Merlyn in the 2018/19 financial year, which is encouraging.
On the financial front, a Piotroski F-Score of seven is fairly reassuring. Coupled with the improved performance forecast for this year, I don’t see any particular concerns at the moment.
The right time to buy?
For a stock that’s looked cheap for a long time, Norcros now has a very strong momentum score:
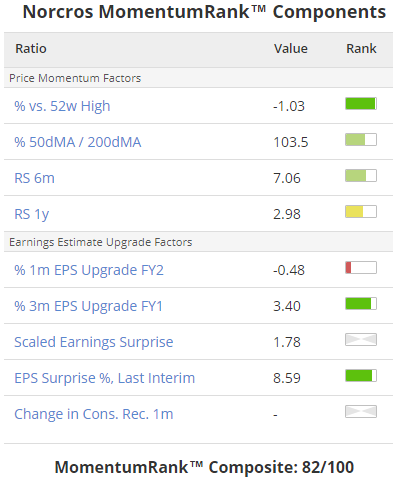
Stockopedia’s algorithms have also awarded a StockRank Style of Super Stock and an risk rating of Adventurous. That’s a combination which has performed strongly, in aggregate, over the last few years.
I’m not betting on a massive re-rating of Norcros stock. And I hope that management resist the temptation to load up with much more debt.
But the outlook for this group does seem positive on several fronts. I can’t help but think that the forecast P/E of 6.5 seems too cheap. With this in mind, I’m going to accept the cyclical risk of this stock and add it to the SIF portfolio this week.
Disclosure: Roland owns shares of Bonmarche Holdings and Dixons Carphone.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

18 comments
Re Norcros (LON:NXR), I am another long term (now multi-year!) holder waiting for it to re-rate. Going to buy more today after spikedown to 170ish following another bunch of badnews stories about South Africa. Hope/expect to see 250p sometime in next 18-24months - just dont know when!
Personally, I think the risks (UK consumer/housing recession, pension size, SA business) are in the price and management are slowly doing the right things where they can control it (re-set of Tiles, Merlyn acquisition to dilute SA/pension) whilst macro environment will be more good (new housing drive, interest rates rising helping pension, new SA president) than bad (UK consumer recession). However, next 12 months has to be digesting/exploiting Merlyn and paying down debt. So another year of slow burn and steady dividends seems likely. It is operating like a decent family business. That's not bad but it won't result in huge moves.
To really move forward Mgt need to attract in some serious buying from some institutions - private investors too small and just circulating shares between themselves. What could trigger a big re-rating?
Perhaps a coming recession will throw up some more material opportunities. I had had crazy hopes of a tie up with Topps Tiles until that re-rated recently! Alternatively, like others I would like to see some more international ambition to diversify away form UK (&Eire)/SA.
Both Sub-Saharan Africa and The Gulf region would be Brexit neutral and whilst risky could be built with relatively low levels of cash investment - at the end NXR is a small cap. Access to these markets might provide the story needed to entice institutions. Less exotically, a significant foothold in a big European market would also signal ambition/help diversity but I doubt this could come now until 2019.
In the meantime, we wait.
Norcros (LON:NXR)
Thanks for the detailed fundamental analysis; as more of a technical analyst , ( & getting much more into fundamentals with the help of Stocko), I would expect the price to retrace to 185-180 before starting what would quickly become a positive uptrend with a target of 222. The reasoning is that the current price trend is a narrow channel the top of which it reached, could break through or fall back, so certainly wait to see. The price has only recently broken the 'Most Recent Active High' of the Down Trend which may become Support in not then back to the bottom of that narrow channel. I appreciate that your Rules don't allow for this but otherwise it is a 23% rise & not 13%.
Ah cool, thanks Gus
Sorry, probably just being a little thick but where can you see a company's value rank components like you have in the screenshots there? Couldn't spot what you click to see the rank breakdown like that. Thanks!
Not sure if it is the only/best way to do it, but if you put the stock into a portfolio and select the Value Screen and then click on the Value Rank circle score this will pull up the constituent elements of the ranking. Same goes for the other Stock Rank scores.
Gus.
Another way to do see the breakdown of the rank components is to go to the sector page for a stock - e.g. click on "Homebuilding & Construction Supplies" at the top of the Norcros page - and then click on the rank numbers.
Cheers,
Roland
I don't particularly think the South African business is an issue.
As announced at the interims the revenue grew from £42 million to £51 million - an increase of 21% or 4.8% (constant currency) - having said that I would like to see them diversify their revenues.
Aah Norcross ya wee beastie (its Burns night) I have held before and I am tempted again. should I shouldn't I? I think it has to go back on the watch list as down slightly today. It should fly, most of the metrics are good including Discounted Cash Flow forecast yet it just won't take off. I think others are right it is the SA business and consumer slow downs that are holding it back. I'm having great difficulty finding good stocks at the moment. Hey ho, Charles
I have also held Norcros for some time, and am impatiently waiting for the re-rating.
I remain concerned about the South Africa connection. I agree that recent political news from there has been positive, but fear that it will take a long time for the market to change it's views of that part of the world.
I to have held Norcros for sometime and think that the management have done a very creditable job given the hand they were dealt when the company relisted. The Merlyn acquisition and rising bond yields, albeit slowly should dilute/erode the pension deficit. Also the political climate in S Africa seems to be improving; Zuma is all but gone, and the incoming regime seems to have hung its popularity on reducing corruption and nepotism. Also Mugabe has at last been deposed in neighbouring Zimbabwe. So all in all the political climate seems to have turned very much for the better and with that hopefully the economic outlook. Fingers crossed off course!
The above coupled with rising momentum gives me some confidence that value in the Company will at last start to be realised. Provided that Norcros can continues to trade in line with expectations and the markets don't fall off a cliff, a forward PE 10 appears more than reasonable.
I don't think that I am given to confirmation bias but please feel free to chip in if you feel I have got it wrong.
Good luck to All
Jonno
Theres no doubt this is a excellent value share, and I believe where growth is at all time high in the markets the trend will now turn towards value shares like this.
It broke its 50d ma last May I believe and there has been a slight rise upwards in the share price.
Also a lot of its profits have come from South Africa which as a market has been performing extremely well compared to other regions in the world. This previously was also causing a lot of uncertainity as SA was considered a volatile region to invest in. (btw Nigeria is also another market which has been the 3rd best performer in the world at the moment).
The divended has also been increasing slightly as well which is a positive sign. There share price needs to break past at least 200p for it to gather further momentum. I personally am tempted as this share could surprise after having its price go no where for ages. Watching closely from sidelines as for the moment I'm only interested in value shares as I dispose of all other stocks I have that do not have a value bias.
Norcros is currently at the top of its price range and I have noticed that several of your recent acquisitions are also at the top of theirs. I have a feeling we are going to see a major correction within the next six months so how would this help your stocks which you normaly keep for approx. nine months.
I would be interested on your veiws of the markets at the moment and your current advise on stocks as regards the possible correction of the markets.
Please dont take this as a criticism as some of the stocks you have advised recently have done very well thank you.
Melvyngd,
Thanks for your comment. I agree that a correction does seem possible at some point, although the timing of these things is always fairly unpredictable.
Regarding the timing of my recent additions, I have also noticed that several seem to be at 52-week highs. However, I'm adding stocks to the portfolio based on the rules (which I review annually, in April). In my defence, I'd also say that momentum can be a surprisingly powerful force on stocks whose financial performance is also improving. So a recent high isn't necessarily a problem.
Ultimately, though, I have to accept the timings because the SIF portfolio is a rules based portfolio. Essentially, this is an ongoing experiment to see I can make a rules-based portfolio that beats the market.
It's still too soon to say whether I've been successful, but I would add that I also own most of the portfolio stocks myself, so I do have an interest in trying to make it work!
If a correction happens then I'd expect to get hit along with the wider market. But historically, good, reasonably valued companies tend to bounce back quite quickly. My belief is that the portfolio contains some of these.
Finally, I'd like to reiterate that don't offer investment advice of any kind. Everything I write is my opinion only. Sometimes it will be wrong! My aim is to suggest ways in which investors can do their own research using the excellent data and facilities offered by this site.
Cheers,
Roland
Thank you for a very prompt. reply with an understanding of your policy's towards the Sif Portfolio.
Very enlightening.
Cheers
Melvyngd
Thanks for the article. I have been a holder for years and have been very patiently waiting for it to re-rate upwards. I would like to see the group diversify geographically but also start to pay down some of their debt. It pays a good dividend and is undervalued IMHO.
Good assessment of the pros and cons - thank you.
I think the other elephant in the room with Norcros (LON:NXR) (aside from the large pension liability) is the significant South African element in their revenues and profits. For better or worse, every time the ANC has another brain-f**t the Norcros share price gets pegged back. Hopefully the Merlyn acquisition dilutes the S.A. association but I suspect it will continue to be a lead weight against any short to medium term re-rating. In the meantime, I’ll keep compounding the decent dividend yield.
Gus.
Been waiting years for this to rerate...hope I live long enough to see it.
I have been watching Norcros also. For me the trigger point is if it can break above 190p - it is trying - ideally with some decent volume. Whilst it remains below 190p there is a real risk that it will drop back to the bottom of its price channel.