SIF Portfolio: Spectris measures up nicely + 3 new foreign stocks

The Stockopedia investment philosophy is all about letting the numbers talk. History suggests that this is one of the most effective ways to invest, but it’s still a tough sell for many human investors. As thinking, emotional beings, we’re hard-wired to enjoy a good story.
Luckily, I believe this week’s stock has a good story and a tempting set of numbers. FTSE 250 instrumentation and control firm Spectris exists to help other companies make more money, more reliably. This group’s wide range of products all have one goal - improving efficiency and productivity.
By investing in Spectris kit, companies can improve the quality and reliability of their products and services and perhaps make them cheaper. Given the constant need for industrial businesses to manage cost, quality and automation, I think this market should continue to expand.
A strong year
Recent performance has certainly been encouraging. Sales climbed 13% to £1,526.6m last year, while adjusted earnings rose 14% to 145.1p per share, beating expectations. Improved guidance on cost cutting earned the stock a boost from the broker community and the StockRank has risen by 41 points to 95 over the last month.
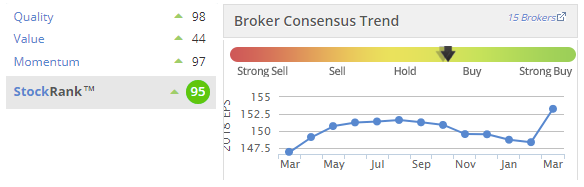
These much-improved figures have also resulted in Spectris qualifying for my screen since its 2017 results were published in February. Although the portfolio does contain some other industrial stocks, there’s nothing of this kind, leaving the door open for Spectris to join the SIF portfolio.
Valued for growth?
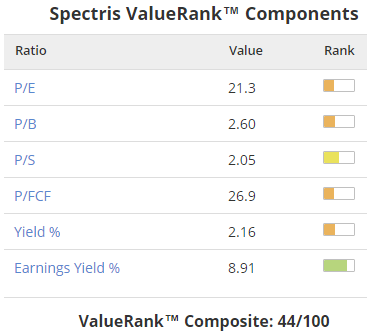
Value is by far the firm’s weakest suite, with a score of just 44/100:
(You can see these breakdowns by going to the sector page and clicking on the ranks)
But even so, there are several things I like about these figures.
P/E versus P/FCF: Spectris’s trailing P/E of 21.3 is quite close to its P/FCF of 26.9. This tells us that free cash flow per share is similar to earnings per share, a good sign of earnings quality.
Earnings yield: The only splash of green in the ValueRank breakdown is the earnings yield. This is one of my favourite metrics as it combines profitability and valuation. By comparing EBIT to enterprise value, a potential buyer gets an idea of how much profit the business generates, relative to its overall valuation. For a business owner, it’s similar to the rental yield on an investment property.
My screen looks for an earnings yield of at least 8%, so Spectris is ahead, although not massively so.
These value metrics suggest to a stock with strong foundations, but a growth valuation. The price/book value of 2.6 would provide little support if earnings collapsed, but as yet there’s no sign of this. Further earnings growth is expected over the next two years. As such, the valuation seems reasonable to me.
It’s all about quality
The firm’s quality metrics seem to support my view that this is a quality business with some moat-like qualities:
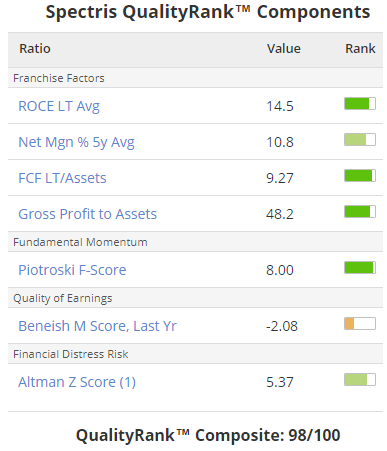
The five-year average return on capital employed of 14.5% and five-year average net margin of 10.8% suggest to me that Spectris products have some degree of competitive advantage. This enables the firm to maintain very attractive margins and generate an attractive return on new investment.
Spectris’s Piotroski F-Score of 8/9 confirms the overall health of the firm, highlighting strong cash generation, improved profitability and a strong balance sheet. The overall picture looks good to me, if earnings momentum can be maintained.
Surging momentum
Spectris shares spiked higher after the firm’s 2017 results were published on 19 February, but they’ve since slipped back to the 50-day moving average. The overall chart picture looks positive to me:
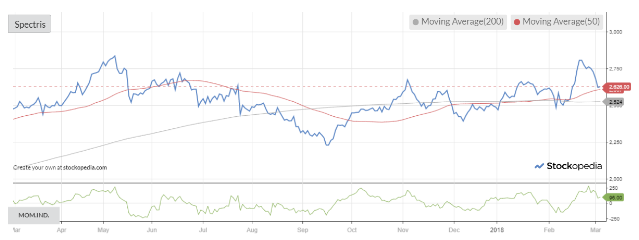
My reading of the chart is that the stock could be moving into a new uptrend. The broader momentum picture also seems positive, earning Spectris a MomentumRank of 97, and increase of 57 over the last 30 days.
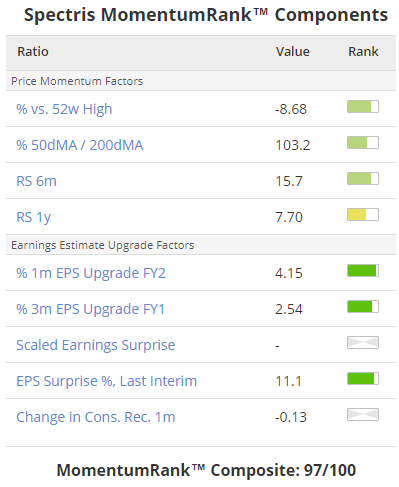
The price momentum is reassuring, but it’s the earnings upgrades which are of most interest to me.
The Stockopedia ‘EPS Surprise’ statistics reflect the earnings beat in the recent results (versus Thomson Reuters consensus forecasts). Meanwhile broker consensus forecasts for 2018 (FY1) and 2019 (FY2) have inched higher in recent weeks.
It’s hard to find anything to fault here. Although broker forecasts do tend to lag reality rather than anticipating it, there doesn’t seem any reason at the moment to expect company-specific or macro headwinds.
On that basis, I’m going to add Spectris to the SIF portfolio this week. I’ll also add it to my own portfolio after this article has been published.
3 new foreign stocks
I ran out of space to include these in my month-end review last week, so here are the three new foreign shares I added to my International SIF in February.
As usual, my research was minimal and I simply selected three reasonable diversified stocks from my international screen and added them to this virtual portfolio. See what you think of the latest additions.
Globaltrans Investment (LON:GLTR): A London-listed, Cyprus-based firm which operates and owns rolling stock in Russia, CIS and Baltics.
The firm’s biggest customers appear to be miners and oil producers. The shares have looked cheap for some time, despite doubling over the last year.
Net debt has halved from its 2014 peak and is now around one times net profit, so isn’t a concern. The rolling forecast P/E of 9 and forecast dividend yield of 9.7% seem attractive, if a little too generous.
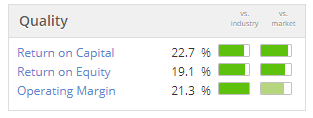
However, the forecast dividend does appear to be supported by a trailing price/free cash flow ratio of just 7.4. Operating margin and return on capital employed are also both high, despite this being an asset-based business:
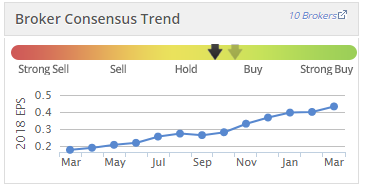
Ence Energia y Celulosa SA (MCE:ENC): This Spanish company operates pulp mills, forestry operations and is involved in biomass energy. Its shares have doubled over the last year, during which its seen very strong earnings upgrade momentum:
The fundamentals, look good, with good cash generation, a rolling forecast P/E of 11.8 and well-covered 4% yield. This £1bn firm also boasts a Piotroski F-Score of 9/9 and qualifies for seven of Stockopedia’s Guru Screens.
Inghams (ASX:ING): This is an Australian poultry producer with a market cap of £792m. My hope is that this business will add a nice defensive element to the international portfolio. I’d imagine that chicken consumption doesn’t vary much, even during a recession.
Inghams has a StockRank of 99 and Super Stock status, which is encouraging. The shares have an earnings yield of 10.5% and offer a well-covered 5.4% yield. Trading on a forecast P/E of 12, the valuation seems affordable.
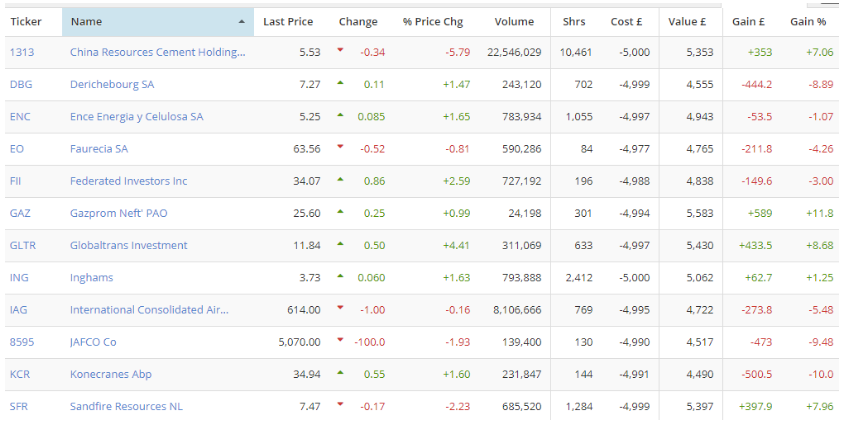
I added all three of these shares to the International SIF last week. Results so far are mixed - the portfolio is running roughly at breakeven.
Here’s how the portfolio looks as of 5 March 2018 (apologies if it’s hard to read):
That’s it for this week, I’ll be back next week, hopefully with another new stock.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

5 comments
Rowland,
I recently acquired some Spectris (LON:SXS) too, but it was the big ranking improvement for Momentum from 46 to 87 that initially caught my eye. In addition when the other rankings were refreshed, the SR increased by 37 to 94, VM up from 51 to 81 and QM up +30 to 100. Promising. Ian
Very interested you have picked up on Globaltrans as I have been an investor for some time and they are rarely mentioned positively. I also invested in UPM - Kymmene Corp and Raute OYJ on a similar basis. All three have been lurking on or around the screen of screens (where I picked them out for further investigation) for a while and I considered them to be worth a go for investment on fundamentals.
Both Globaltrans and UPM are very big companies but I don't recall them being covered much in the media. . That said I recall a number of people on this site (Nov last year) were concerned about the structuring of Globaltrans doing business in russia and located in Cyprus. Also, I gather that some brokers can't trade them, why,I don't know.
Hi Will,
Thanks for your comment. I've noticed Globaltrans Investment (LON:GLTR) performing strongly for some time. I think the reason some brokers can't trade them is that the London-listed shares are GDRs (Global Depository Receipts) - http://www.globaltrans.com/investors/shareholder-information/ownership/
I'm not an expert, but from what I understand, not all brokers can/will handle these in the same way as standard LSE-listed shares.
The company's Cyprus base and Russian operations might deter some investors. I don't know the history of this but I suppose it does make things a bit more opaque than they might be otherwise...
So far, so good, however.
Regards,
Roland
Hi Roland
FYI - Good results from Globaltrans today
Will
Hi Will,
Thanks for flagging up the Globaltrans Investment (LON:GLTR) results. I've not had a chance to go though them in detail but they do look fairly good to me.
I quite like the style of presentation as well -- management appear to have a good grip on important metrics and present them fairly transparently.
Good luck with your holding.
Roland