SIF Portfolio: Taptica International could be the perfect replacement for XLMedia

Last week saw internet marketing group XLMedia exit the SIF portfolio with a tasty total return of 24% in seven months. Bangladeshi pharma group Beximco Pharmaceuticals also headed for the door, leaving the portfolio with a tidy 69% gain.
These virtual sales mean that the SIF portfolio’s cash balance has now been restored to a healthy level. So now I’m on the hunt for new stocks.
The question is whether there any stocks are available which pass my screening rules and qualify for the portfolio.
Unusual stability
I usually check the Stock in Focus screen most days, not just on Tuesday when I write this weekly piece. What I’ve noticed recently is that the shares qualifying for the screen aren’t changing much. Most of the qualifying stocks have been regular fixtures in the screen results for weeks or even months.
As a result, a significant proportion of these stocks are already in the portfolio. At the time of writing, 17 stocks qualify for the screen. Of these, eight are already in the SIF portfolio. The majority of the others are sector peers that I’ve excluded on the basis that they don’t meet my criteria for diversification.
However, last week’s portfolio sales have opened up two new slots in the portfolio. That means I’m free to consider adding Taptica International, an Israeli mobile marketing group I rejected on diversification grounds in April.
Why Taptica?
When I last looked at Taptica International, I noted that this AIM-listed digital marketing group looked potentially attractive but overlapped too heavily with fellow Israeli marketing firm XLMedia.

However, whereas much of XLMedia’s profit comes from the gaming sector, Taptica works with some of the biggest consumer brands in the world. Here’s a snapshot of a few of the companies featured on its website:

Source: www.taptica.com
Taptica operates in more than 15 countries with over 600 apps and brands. The company’s user database handles more than 22bn requests each day and contains 220m user profiles with more than 100 data points for each user!
It seems to me that Taptica must be becoming a significant player in this sector, providing tailored marketing for big brands, mainly through targeted mobile advertising.
Do the numbers stack up?
Taptica’s sales have risen from $20.3m in 2011 to $125.9m in 2016, giving a compound average annual growth rate of 44%. Net profit growth has broadly matched this, rising by a CAGR of 42% over the same period (although the figures for 2011-2013 are pro forma, as Taptica only floated in London in 2014).
The firm’s 2016 results were certainly impressive, as Paul Scott commented at the time. Revenue rose by 66% to $125.9m, while gross profit rose by 118% to $46m, thanks to an improvement in gross margin from 27.8% to 36.5%.
Taptica ended last year with net cash of $21.5m, despite spending a total of $16.5m on acquisitions, share buybacks and dividends. This is clearly a cash generative business and I’d expect this to continue. In my view, the group’s data-driven marketing approach is likely to become more effective and efficient at larger scale.
Scope for re-rating?
The market appears to remain sceptical about Taptica, probably because it’s an overseas company listed on AIM. The only time Taptica’s share price climbs is following a broker upgrade and/or a strong set of results. To highlight this I’ve placed the chart for the last year above the broker forecast trend for the same period:
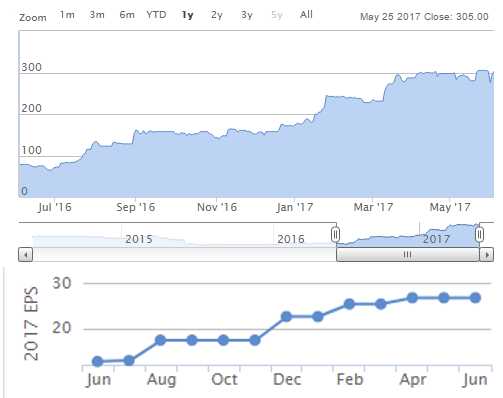
Despite this, the shares have enjoyed a significant re-rating over the last year.
The consensus earnings forecast for 2017 has risen by 110% since June 2016, from 12.7 pence to 26.7 pence per share. Over the same period, the share price has risen by about 280%. So we can see that Taptica’s 2017 forecast P/E ratio has risen from 6.2 to 11.3 over the last year.
As Taptica reports in US dollars, the precise level of re-rating may have been affected by the depreciation of the pound. But the trend is unmistakeable.
Affordable growth?
With a StockRank of 96 and a StockRank Style of Super Stock, the omens are good. However, Taptica’s strong growth last year means that the ValueRank, which uses trailing figures, is a relatively weak 53.
That’s not necessarily a problem, as the group’s trailing valuation figures are still relatively appealing:
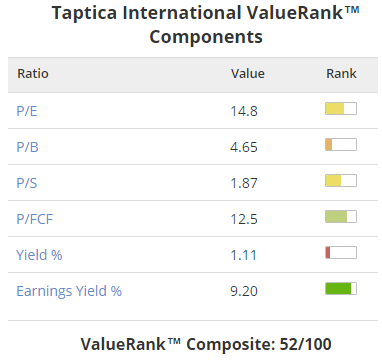
The highlights for me are Taptica’s trailing price/free cash flow ratio of 12.5 and its earnings yield (EBIT/EV) of 9.2%. These two figures alone suggest decent value to me. After all, inverting the P/FCF ratio gives a free cash flow yield of 8%. That represents money which can safely be returned to shareholders or used to invest in growth.
Taptica’s high price/book ratio doesn’t concern me, as this is a business built on people and intellectual property. Its value lies in the earning power of the complete package.
Overall, I’ve no concerns about Taptica’s value scores, given its current growth rate.
Top quality
Taptica’s QualityRank of 99 suggest a near-perfect set of figures. The reality certainly looks promising:
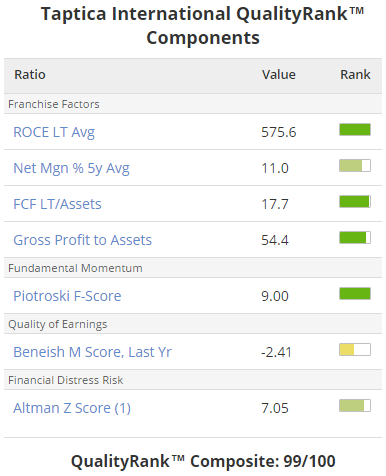
I think it’s worth noting that the six-year average return on capital employed (ROCE) is probably being skewed by the presence of pre-IPO figures in the Stockopedia data:
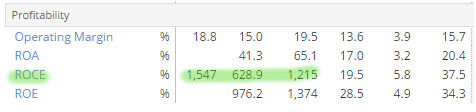
Did Taptica really generate a ROCE of 1,215% in 2013? It seems unlikely. However, the group’s post-IPO average ROCE of 20.9% is far more credible and still very high.
All the other figures in the QualityRank calculation seem fine to me. One particular attraction is the Piotroski F-Score of 9/9, which confirms the wholesale improvement in the company’s performance seen in 2016:
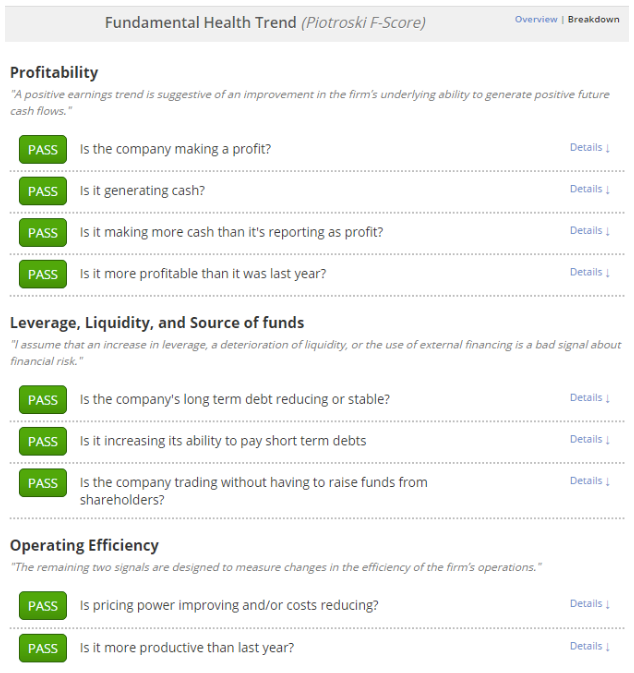
The F-Score is a great way to get a snapshot of a company’s financial health and recent performance, in my opinion. It’s also heavily weighted in the QualityRank calculation, so high quality stocks usually have high F-Scores.
Does Taptica still have momentum?
Taptica’s habit of only making gains after a positive update hasn’t prevented the stock from earning a MomentumRank of 91. Price momentum factors are particularly strong, as the screenshot below shows:
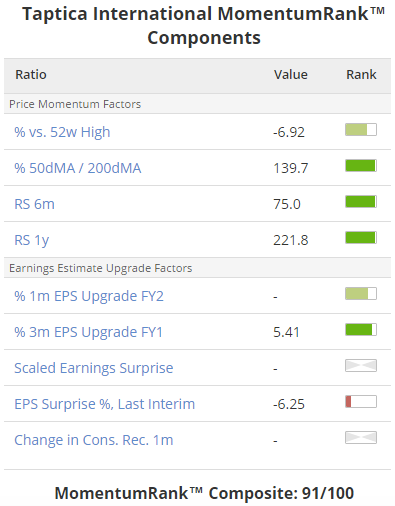
Looking ahead, earnings per share are expected to rise by 30% to $0.34 this year, putting the stock on a fairly undemanding forecast P/E of 11.3. The dividend payout is expected to rise by 65% to 7.1 cents or 5.5p. This should give a more attractive 1.8% yield, while still maintaining dividend cover of about 4.8x. Although stingy, this payout ratio should mean that Taptica will still have the firepower needed to make acquisitions or buyback shares without using debt.
My verdict: I can’t see any obstacles to further growth for Taptica. The valuation looks reasonable and the firm’s financial performance seems excellent. I’m going to add Taptica to the SIF portfolio this week. I’ll also buy for my own portfolio after this article has been published.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

3 comments
Roland
Taptica International (LON:TAP) up 10% today (at time of writing). Some buy/sell trades scraped off Hargreaves site
RECENT TRADES TRADES BY VOLUME
Time / dateBuy / sell
Volume Price Value
08:37 - 13/06 Buy 100000 310.00p £310,000.00
08:37 - 13/06 Buy 100000 310.00p £310,000.00
13:50 - 13/06 Buy 50000 335.00p £167,500.00
12:46 - 13/06 Sell 10060 333.00p £33,499.80
11:18 - 13/06 Sell 10000 320.00p £32,000.00
I hold.
Regards
Howard
Hi Adrian,
Thanks for your comment. I've no particular thoughts on the change of broker to finnCap, I can't see any reason for it to be a concern.
I know what you mean about the niggling doubt, I felt like that about XLMedia (LON:XLM). But the reality seems to be that Israel has some good businesses in the tech sector. As far as I can see, neither XLMedia or Taptica International (LON:TAP) have yet given investors any reason to doubt their credentials.
Cheers,
Roland
Thanks Roland, appreciated.
I recently bought in and topped up on the now recovered drop. I came to similar conclusions and whilst the market may still have some reservations, the SP should still progress at a reasonable rate with such strong fundamentals. Have you any thoughts on the broker change?
That said,I still have a niggling doubt that I have missed something (other than the overseas element) but haven't found it yet!
Cheers and good luck,
Adrian