SIF September review: Bonmarché, Motorpoint and a bid for Jardine Lloyd Thompson

Last week came to a profitable end for the SIF folio, when specialist insurance broker Jardine Lloyds Thompson received a takeover bid from US heavyweight Marsh & Mclennan. This week I’ll take a look at this news and explain what I’m going to do next.
As it’s the end of the month, I’ll also review any stocks which have been in the folio for at least nine months. Checking back through my trading records, I can see that two stocks were added in December 2017, so must be considered for eviction this month:
Motorpoint: I’ve become something of a reluctant convert to the attractions of this business. The stock’s performance has been good during its time in the portfolio, but does it still pass all of my screening tests?
Bonmarché Holdings: This small-cap womenswear retailer has the credentials I tend to look for in value investments. Low valuation, strong balance sheet and a high yield. Performance so far has been promising, but I think there’s more to come.
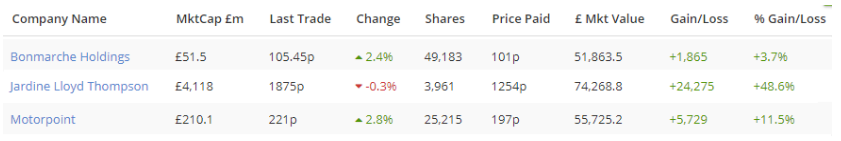
Here’s a snapshot of how these holdings have performed so far. Both positions are in profit and have also paid dividends (not shown here). I’ve also included Jardine Lloyd Thompson in this screen grab so we can see the effect of last week’s bid on the SIF holding:
Bonmarché Holdings
When I added Bonmarché Holdings to the SIF fund in December 2017, I was particularly keen on the stock’s value credentials. This is something Graham and Paul have also commented on in their coverage.
I think it’s worth revisiting this and seeing how the situation has evolved since then:
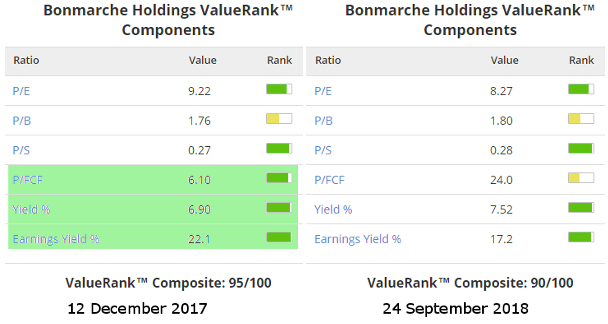
Most of these value ratios remain similar to when I bought the stock. They certainly still look attractive to me, when combined with a StockRank of 96.
The only exception is the shares’ price/free cash flow ratio. A sharp increase from 6.1 to 24 suggests that cash flow has markedly worsened. However, I don’t think this situation is as bad as these numbers suggest.
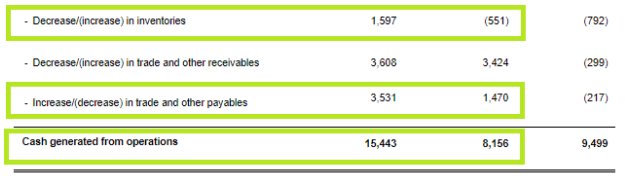
Last year, H1 free cash flow was boosted by a £1.3m reduction in inventories and a £2m increase in trade creditors (payables), combined with a big increase in half-year profit:
Source: Bonmarche FY18 interim results
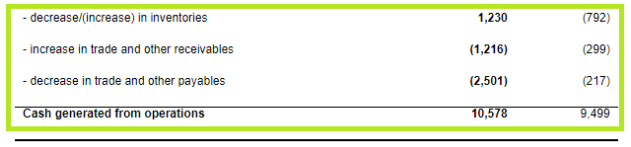
As I predicted at the time, such large gains were unlikely to be repeated. The group’s latest results confirmed this. Although inventories continued to fall, receivables increased and payables fell. The overall result was a more modest increase in operating cash flow:
Source: Bonmarche FY18 full-year results
I expect these working capital movements will settle down over time, as the changes implemented by CEO Helen Connolly bed in.
In the meantime I’m pleased to see that group sales rose by 2.7% during the first quarter. A reduction in store LFL sales was offset by a 27% increase in online sales. The group’s net cash balance of £4.3m continues to provide a useful buffer to support the dividend and the ongoing turnaround.
Looking ahead, earnings per share are expected to rise by about 10% during the year to 31 March 2019. This puts the stock on a forecast P/E of 7.2, with a twice-covered yield of 7.7%.
That seems cheap to me, given the progress seen so far. Happily, the shares continue to pass my screening tests as well.
Bonmarche will remain in the folio for at least one more month.
Verdict: Hold
Total return to date (inc. dividend): +12pc
Jardine Lloyd Thompson
When I added Jardine Lloyd Thompson to the SIF fund in April, I commented that a cyclical upturn could make the shares cheap at the purchase share price of 1,254p.
Apparently I wasn’t the only one to reach this conclusion. Last Tuesday brought us the news that US insurance broker Marsh & McLennan had made a £4.9bn bid for this FTSE 250 firm.
The offer equates to £19.15 per share, a 33.7% premium to the previous day’s closing price. JLT’s main shareholder, Hong Kong-based Jardine Matheson Group, has given an irrevocable commitment to support the offer with its 40.2% shareholding. So I think it’s almost certain to go through.
I understand from the trade press that there are some concerns that this will reduce the level of competition in the marine insurance broking market. That may be true, but from a shareholder perspective this seems a good offer, so congratulations to any holders here.
This bid is certainly a good result for SIF, as it provides a total return of 51% in just five months.
The deal is expected to complete in spring 2019. However, I will sell the portfolio’s holding this week as Stockopedia’s Fantasy Funds don’t automatically handle delisted stocks. I’ll also sell my own position this week in order to free up cash for new opportunities.
Verdict: Sell
Total return: +51pc
Motorpoint
This car supermarket group only sells cars under three years old and with less than 25,000 miles on the clock. Most stock is newer still.
The group has performed well since its flotation in 2016, benefiting from continued expansion against the backdrop of a strong UK car market. Motorpoint’s business model also seems to be popular with car buyers. Repeat customers accounted for 26.2% of sales last year, up from 25% the year before.
I suspect part of the appeal for customers is the ability to seamlessly roll over finance to a new model and drive away the same day. Browsing the website also suggests that the firm’s stock is of good quality and fairly priced, making the buying process easy.
From a financial perspective, what works so well is that this business combines a limited amount of tangible equity with a stock purchase (credit) facility to generate very high returns on capital employed:
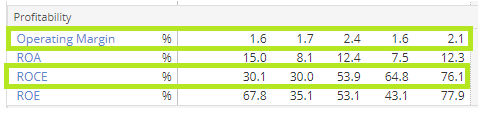
This model has worked well in favourable market conditions. I think it’s also fair to assume that management execution has also been pretty good.
I’m not sure how things will change in a cyclical downturn, but for now there’s little sign of this. The firm’s most recent trading update reported solid Q1 trading “for both sales and profit”.
Full-year expectations were left unchanged, giving the stock an attractive forecast valuation:
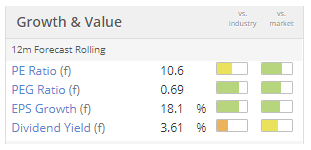
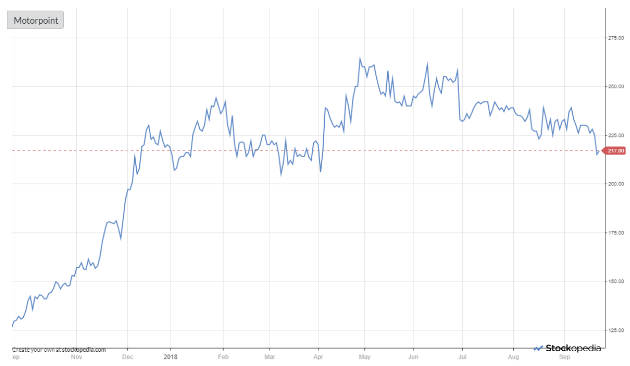
Motorpoint’s StockRank has fallen from 91 to 81 since it joined the portfolio. This is mainly because the share price has been weaker in recent months despite continued profit growth.
Broker sentiment has also become more cautious:
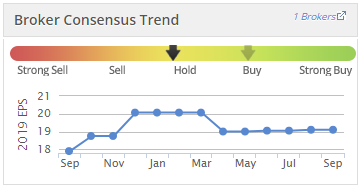
Despite this, Motorpoint shares continue to pass all of my screening tests. The valuation looks reasonable to me and as yet there’s no sign of cyclical problems.
This stock will stay in the SIF fund for at least one more month.
Verdict: Hold
Total return to date: +15pc
Next week...
My screening results currently include a number of interesting new stocks. Barring any surprises changes, I hope to be able to add one of these to the portfolio next week.
Disclosure: Roland owns shares of Bonmarche Holdings, Motorpoint and Jardine Lloyd Thompson.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

3 comments
Nice write up on bonmarche. Thanks Roland.
Been considering adding to the holding especially now that online is meaningful to total sales, and as an accountant, I tend to quite like when CFOs move to CEO (less salesmanship and better balance sheet management) both of which are helpful for a contrarian pick
Rod, that's a good point about Fantasy funds can't handle delisted shares, they can't handle share splits either so if know about one I would sell and then buyback after the split is complete, I had a 1 for 3 share split, complete mess, went from 35% profit to 55% loss.
True, but every cloud.
My Fastjet (LON:FJET) shares went from 99% loss to 1000% gain!
Was painful adjusting on sale to say I received -xx for the shares.
Still got those warrants though so sure I will make it all back!
It's easyJet for Africa after all!