Small Cap Value Report (13 Apr 2015) - GTC, TCM, SYM, UNG, SSTY

Good morning! I'm starting to worry a bit about the outcome of the General Election, so have opened up a short position in the FTSE 100. Yes, I know that most of the FTSE 100 earnings are now overseas, so it's not a very good proxy for UK earnings, but the election outcome is more about sentiment than earnings. People are (rightly) starting to worry about a weak Labour Govt being propped up (i.e. held to ransom) in coalition with the Scottish Nats.
Casting my mind back to the 2010 election, I recall that the big worry then was the risk of a run on the pound, and Gilts. Here we are, with the National Debt far higher, and nobody seems to be worrying any more. There again, economic recovery seems fairly well established now, when it wasn't in 2010.
I won't be adjusting any of my long positions, as it's too expensive with small caps, to trade in & out, due to the wide bid/offer spreads. So having a short on the FTSE 100 will help me sleep at night, and will provide a cash buffer if the market as a whole does go into panic mode. After all, you need cash to be able to buy at the bottom.
I wonder if other people might now be reluctant to open any new positions until the General Election uncertainty has passed? It could throw up some interesting buying opportunities, if good companies drift down in price due to a buyers' strike.
Laura Ashley Holdings (LON:ALY) issued their results mid-afternoon on Friday last week, which was a bit of a nuisance, so I had to do a write-up on them here. Also I slotted in another interesting company, OMG (LON:OMG) - I hold long positions in both, as is always disclosed within each section of each report - and I think both look excellent companies, so if you haven't seen that report then the link is here.
Getech (LON:GTC)
Share price: 60p (up 12.5% today)
No. shares: 30.3m
Market Cap: £18.2m
Contract win - this is an interesting one. The company says it has won a contract with a national oil company, but on closer inspection it sounds as if they have actually made it onto a preferred supplier list, and will now be invited to tender for various work, in competition with two other companies. So not quite the same thing as having won the contracts!
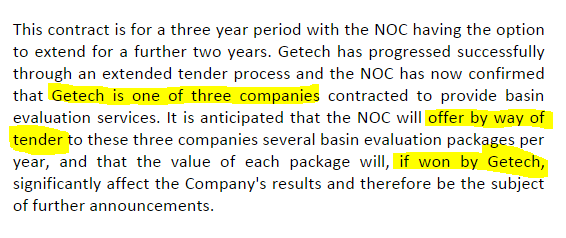
So perhaps early buyers this morning might not have read & digested this announcement carefully enough, who knows?!
My opinion - checking the archive here, I last reported on Getech on 24 Mar 2015 when they published interim results which were remarkable good, considering how difficult market conditions must be in their sector (Getech provides seismic data to oil companies for exploration purposes).
So far so good anyway, the company's strategy of focusing on larger oil companies seems to be working out well.
Telit Communications (LON:TCM)
Share price: 238.5p (up 1.3% today)
No. shares: 114.3m
Market Cap: £272.6m
Q1 trading update - for the three months ended 31 Mar 2015. This sounds encouraging;
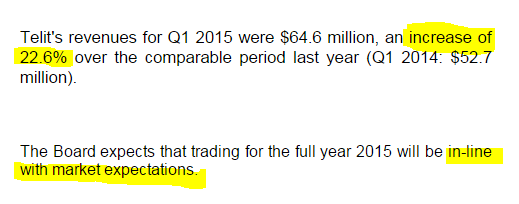
The Stockopedia historical graphs provide some interesting pointers;
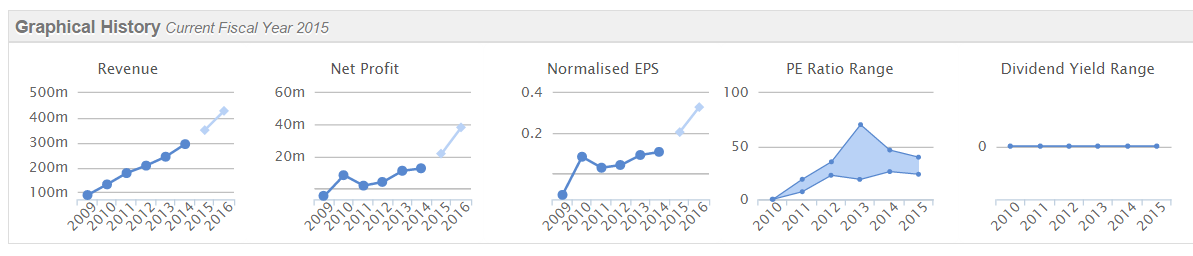
Revenue has been rising impressively, and there's been some growth in profit & EPS too. Although checking some of my previous comments on this company, I think some of the growth has come from acquisitions - which is inferior to organic growth, obviously.
Valuation - note how broker forecasts assume a considerable increase in profitability & EPS both this year (calendar 2015) and particularly next year. Given that the company has today said that it's in line with forecasts for the current year, then this is starting to look potentially interesting.
Broker forecast is for a near doubling of EPS this year to $0.21, so that puts it on a PER of about 16.8 for this year, dropping to just 10.4 for next year. Although aggressive growth in broker estimates for future years can often be pie in the sky.
Dividends - there aren't any, so a negative mark there. I like to be paid to wait for shares to go up.
My opinion - I don't know anything about the technology this company sells, other than that it's a trendy area - the internet of things - so it seems to be hardware/software to let your fridge order milk for you, and things like that.
The company is apparently headquartered in London, but the Directors' names all sound foreign, so I would need to check where the company's operations are based, as generally I am not keen on overseas companies listed on AIM (there's often something wrong with them). Although this one is reasonably large, and profitable, so that helps.
Have any readers looked at Telit before? It looks potentially interesting to me - worthy of further research anyway.
Symphony Environmental Technologies (LON:SYM)
Share price: 8.4p (down 21% today)
No. shares: 144.6m
Market Cap: £12.1m
Preliminary results - for calendar 2014 are out today. As a general point, I think we're getting to the time of year where decent companies really should have already reported their 2014 figures. Especially small/micro caps where, let's face it, it should be a doddle to produce the annual figures for such small businesses, for any half-decent accounts team.
I'm speaking from experience here. My accounts team used to have finalised figures ready for audit within about 5 weeks of the year end, and that was in the 1990s (when some reconciliations were still being done manually), for a group of companies with about 150 branches in the UK & abroad. The audit was wrapped up in 2-3 weeks, max, because there were never any audit adjustments, because I made sure the figures were 100% correct from the start. So having done the job properly myself, I've not got much patience for companies which are putting out results in Q2 of the following year - that's just sloppy.
Anyway, going back to Symphony, the figures don't impress. Turnover is actually down (never good for a purportedly growth company) by nearly 12% to just £6,352k for the year. So a tiny business.
It generated an operating loss of £265k against a comparable of £159k last year. Note also the £126k of finance costs in 2014, indicating that there is some debt, It looks to be expensive debt too, with a balance of £1,153k outstanding at the year end, so looks as if they're paying c.10% interest, roughly.
Although the debt is almost offset by £938k of cash at the year end, which came from an equity fundraising during the year.
Outlook - the Directorspeak here is promising jam tomorrow, saying that legislative trends are pushing the use of biodegradable plastics. Although the expectations of growth seem to be founded on expressions of interest, and small initial orders, rather than a bulging order book.
My opinion - the cash burn here looks very modest, so because of that it is probably not as dangerous as most jam tomorrow shares. However, turnover falling, and a lot of commentary about lengthy trials with customers, etc, puts me off. I'd have a flutter if the market cap dropped to about £4-5m, but at £12m, for an essentially unproven business model, with (so far) limited growth, that is now actually going backwards, it's difficult to get excited about this one.
There must be thousands of other companies also doing biodegradable plastics all over the world too, so why is this one likely to succeed in particular, I wonder?
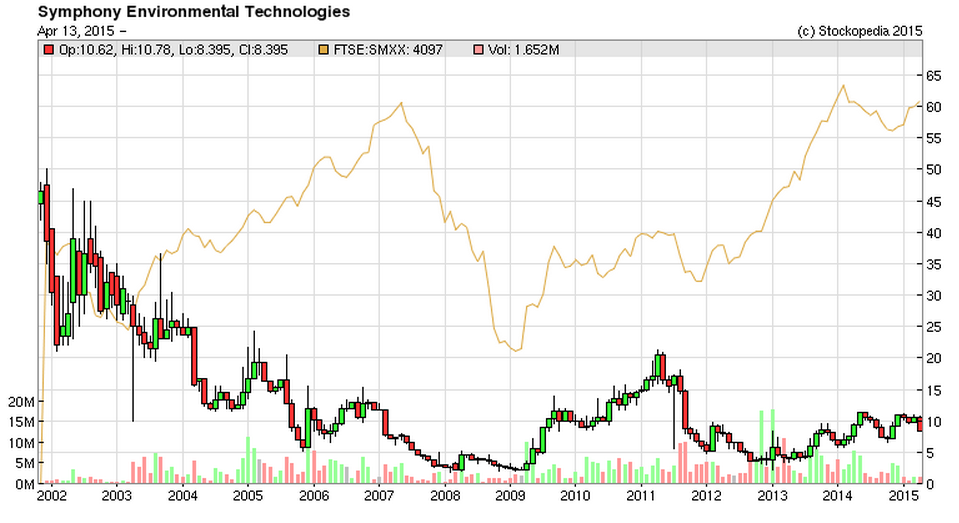
Also, this stock seems to have been around for many years, with the odd flurry of interest, but no sustainable profits emerging. So it looks a very stale story stock now, as the long term chart below suggests. Maybe it will have another short-lived burst of excitement at some point, who knows?
Universe (LON:UNG)
Share price: 7.7p
No. shares: 220.3m
Market Cap: £17.0m
Preliminary results - for calendar 2014. Turnover and profit are usefully up, which they say is due to 16% organic growth, plus acquisitions made in 2013 kicking in.
Broker consensus is for 0.75p EPS for 2014, with the result coming in a bit below, with "underlying" EPS of 0.71p.
Outlook - there's nothing specific, but generally positive noises are made in the Directorspeak.
Balance sheet - not great, but not alarming either. Net tangible assets are just about positive, at £2.0m. The current ratio is 1.18, which I could live with, given that inventories are very low. There is a modest amount of debt, c£1.8m, which was more than covered by year end cash of £2.1m, although one would expect the year end cash balance to be untypical, as most companies like to window-dress the year end figures.
Cashflow - net cashflow from operating activities is very good, at £3.0m, however don't get too excited because they spent £1.1m of that on capitalised development costs - so the usual issue with IT companies in that the headline EBITDA figure is not a reliable way of measuring genuine profitability.
Dividends - none, unfortunately.
My opinion - the price looks about right to me. This company has performed fairly well in the last two years, and so the price of a PER of about 10 looks about right. Investors should remember that small companies like this really should be cheap - as their profits tend to be volatile, and the company is often heavily reliant on a small number of key customers, staff, and contracts. So a single digit PER is the right sort of price, stretching up to about 10 if the company is performing well, as in this case.
If there was some catalyst for a big increase in future profits, then I might be interested, but there's nothing of that nature in the narrative that I can see. Therefore it's not of any interest to me - I think there are better growth opportunities elsewhere.
It comes up with a good StockRank of 88 mind you, and the operating margin is quite good now too, so maybe I'm being too pessimistic about it?
Safestay (LON:SSTY)
Share price: 69.4p
No. shares: 19.2m (NB. Thomson Reuters data on this appears to be incorrect, so I have used the correct figure here, as stated in note 5 to today's accounts. I have flagged the issue to Stockopedia for correction)
Market Cap: £13.3m
(at the time of writing, I hold a long position in this share)
Final results - for calendar 2014 - well I say that, but the company listed on AIM on 2 May 2014, and that was also the date it acquired its first premises, being the former Labour Party HQ at Elephant & Castle. Safestay are now using the building (freehold) for something far more useful, I am pleased to say - as an upmarket hostel for budget travelers.
So these are part-year (8 months), maiden results, and therefore need to be viewed as being the starting point around which a hopefully much bigger company will be built. The company acquired a second freehold site, in York late in 2014, and a third site in Holland Park (which sounds very interesting, as it looks to be a historic building, on a 50-year lease), due to open in summer 2015 after a £2m refurbishment.
Profitability - the 8 month figures show turnover of £1.9m, and a very impressive £580k operating profit. However, this is for the elephant & castle site, which is freehold, so there's no rent cost. However, the interest charge (for debt to finance the freehold) is very high, at £444k. This leaves behind only a profit before tax of £137k.
Whilst that may seem disappointing, you could regard it as being rather encouraging that the company is able to cover all its central costs from the profitability of only one site. It's not often you see a roll out type investment stack up with just one site.
For that reason, I don't think earnings metrics make any sense at this stage, but for the sake of completeness, diluted EPS was 1.18p, so the PER works out at 58.8!
Individual site performance/potential - this all sounds positive;
Elephant & Castle - "trading performance... continues to improve". Note that the pro forma results for this site were impressive at £972k EBITDA for the 12 months to 31 Dec 2014, which is about double the likely entire company's interest charge for 2015 (£9.3m debt at avg interest rate of 5.26% = £488k).
York - "We are delighted with the results of the refurbishment and the first year of trading as Safestay York is comfortably on track to meet management's expectations"
Holland Park - scheduled to open in summer 2015. "...we are confident that the hostel has excellent trading potential given the building's aesthetic appeal and its highly convenient location in a very desirable central area".
Outlook - this all sounds upbeat;
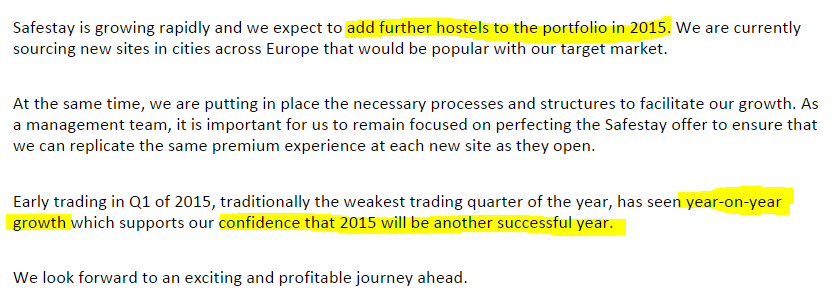
Living Wage - I'm really pleased to read in the narrative that SafeStay has signed up for the Living Wage Foundation, and pays staff a living wage. I think this is very important, as staff who are paid fairly are more motivated, and tend to stick around. Let's hope more companies follow suit, instead of trying to exploit low paid staff for lowest pay they can get away with.
On a commercial level, I also think that making a big song & dance about paying a Living Wage should help Safestay attract customers, generally younger people, who will see the living wage as something they aspire to themselves, and hence a very good thing to support.
The more brutal capitalists amongst the readership here may not agree with me on this point! Usually on the basis of, "I had to work for tuppence ha'penny a day when I were a lad, so why should today's youth be molly-coddled?!"
Balance Sheet - this is dominated by the £15.0m freeholds (which are revalued upwards, based on independent valuations from a respectable firm that I've come across before, Edward Symmons LLP).
The freeholds are financed by bank debt, which was £9.1m gross, a little on the high side perhaps. Although bear in mind that the company did an equity fundraise in late 2014 to finance the refurb of the new Holland Park site, so it had £3.3m in cash at 31 Dec 2014, bringing net debt down to £5.8m, which looks OK to me, given the cash generative nature of the hostels which are already operating.
Overall NAV is £8.7m, and there are no intangibles capitalised. The market cap of £13.3m is therefore a 53% premium to book value, which sounds fine to me, as I'd expect the existing (and new) sites to be revalued upwards again as trading improves.
My opinion - as regulars here will know, I'm pretty good on value share stock picking, but my more speculative stock ideas are usually rubbish! So it might be safest to ignore me on that front!
However, in this case, Safestay is one of my favourite long term, somewhat speculative stocks. I've held since just after the IPO, and intend holding for 5 years+, as I really like the concept, and the fact that it is already profitable despite only just starting out.
The whole concept of an upmarket hostel is a clever idea, and searching the internet for customer reviews, it's clear that the customers like it. Here is Safestay's website, to get an idea for what they do. So repeat business is building, and more sites will be opened. With Europe still economically depressed, there should be plenty of good value sites to secure on favourable terms, so I hope Safestay really get cracking with the roll out to more sites asap.
The main downside is that the company will need to do repeat fundraisings to raise the cash to secure sites and refurbish them. That said, management are experienced property people, so seem to know what they are doing, and so far, so good.
I don't see any particular reason for the share price to go any higher in the short term, but am hoping to see steady appreciation over a number of years here as the roll out gathers pace.
Regards, Paul.
(as mentioned above, of the companies discussed today, Paul has a long position in SSTY and no short positions. A fund management company with which Paul is associated may also hold positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

42 comments
"If it's not the outcome you want you should probably be up in Scotland campaigning for the Labour party to reduce any SNP influenceafter the election :-)"
Prefer Scotland leaving the UK thanks. So I'll be campaigning for anotehr referndum as soon as possible so this farce can be put to rest.
They may have a bit of influence, but that's just how our democracy works. The Lib Dems were in the same position in the last parliament. Whatever happens they'll still be a small party, and will be easily outvoted on issues where the other parties agree - such as most likely on a Trident replacement.If it's not the outcome you want you should probably be up in Scotland campaigning for the Labour party to reduce any SNP influenceafter the election :-)
"I love Scotland and Scottish people,"
As indeed did I, until this rather distasteful last couple of years. It's certainly done English/Scottish relations plenty of harm and I see such deteriorating further.
" I certainly wouldn't vote SNP, but democracy is democracy."
Not sure how you think it's democratic, or fair, that a party with such a small share of the national vote is going to be wielding so much power come May election - a country of only 5.29m dont forget, waging the tail of a country of 55million.
Personally Scotland's secession from the UK is preferable to a coalition of Labour/SNP imo, and I'm sure I'm not in a minority when it comes to that from an Englishman's POV.
"Please can we zip the anti-Scot rhetoric and crass generalisations as it's not helpful and off-topic."
Fine.
We'll let events play out....
"I clicked on your name to see who you were, in order to try to understand why you were posting these comments. Maybe that's the wrong way to do it, I don't know, but I never sent you any messages."
No biggie. I did wonder why they were coming to my inbox.
Election is only 23 days or so away. And a Labour/SNP is the likely outcome, which will be a disaster this country cant afford. Not sure why you'd need to read my profile though to understand why I have the opinion i do. The empty treasury in 2010 and there's no money left was,I thought, evidence enough! :)
@PhilH,
Cheers. Tend to just comment and submit rather than using reply button myself.
You got a message from stockopedia saying someone had replied to your post. On the last occasion Jane just added to the thread rather than replying to your comments.
I clicked on your name to see who you were, in order to try to understand why you were posting these comments. Maybe that's the wrong way to do it, I don't know, but I never sent you any messages.
"I haven't messaged you direct.What on earth are you on about?"
So how come I didnt receive this message in my email inbox then, but I did your last two?
Anyway, I'm not interested in having any discussion on an investments site with someone so abusive of others whose political views differ from theirs.
Enjoy!
" I'm not interested in having any discussion on an investments site with someone so abusive of others whose political views differ from theirs."
Huh who was abusive?
I merely said Sweaties which is no worse than you telling me TWICE to take my opinion elsewhere because you clearly disagreed with it - who put you in charge to censor what is, or what is not, commented on.
Not Scottish are you?
And anyone voting Labour after the financial mess they left this country in is pig ignorant.
There is no other reason for someone voting for a party that effectively holed this country below the waterline - as indeed do nearly all Labour governments. Time and again the Tories have been called in to clear up the mess - this time they were unsuccesful - ie it was that bad.
I'm not a Conservative voter either before you accuse me of partisanship - just a realist.
Fangorn. I'm proudly born & bred in Scotland - born in Ninewells Hospital, Dundee, went to school in Brechin and then in Dunbar and still visit my siblings in Edinburgh and Glasgow annually.
I love Scotland and Scottish people, I'm not that sweaty and I'd have voted no if I'd been given a vote. I certainly wouldn't vote SNP, but democracy is democracy.
Please can we zip the anti-Scot rhetoric and crass generalisations as it's not helpful and off-topic.
I haven't messaged you direct.
What on earth are you on about?
Given that the first paragrapgh was veryr much "Politics" inclined
Good morning! I'm starting to worry a bit about the outcome of the General Election, so have opened up a short position in the FTSE 100. Yes, I know that most of the FTSE 100 earnings are now overseas, so it's not a very good proxy for UK earnings, but the election outcome is more about sentiment than earnings. People are (rightly) starting to worry about a weak Labour Govt being propped up (i.e. held to ransom) in coalition with the Scottish Nats.
And was started by the landlord to boot, i felt my response, to him, were perfectly aceptable.
"No politics unless relevant please."
And you then immediately follow with
"Is anyone else trying to keep some cash back for potential heightened uncertainty closer to the election?"
Which surely MEANS talk about ELECTION result, ergo politics, is indeed VERT RELEVANT to your decision making investment side?
Hypocrisy?
Politics ARE relevant.
Referring to a people as 'sweaties' and our fellow citizens as displaying 'pig ignorance', probably not.
I used to keep pigs, by the way. They are exceptionally smart creatures. (But the bravest are the ducks, despite the fact they have no real means of defence at all!)
Given that nearly 50% of that country's population dont want to be "our fellow citizens", and the fact that it will be THIS segment that will be dictating the terms of any Labour coalition government, thereby garnering them with far more power than their actual vote justifies are you happy with that? Scots have gone down in my estimation - wont buy Scottish produce anymore as they're in the same category as Argentina for their blatant anti Englishness.
Perhaps "bloody ungrateful Sweaties" migth be more appropriate. :)
Viz pig ignorant labour voters.Are you really disputing that the majority of the electorate,(of the 34-36% that are planning on voting Labour) that have probably always voted Labour regardles are not pig ignorant when you see what 13 years of Labour in power did for this country.The scale of the mess they left was clearly irreparable, one the LibCon coalition has merely added to - austerity, what austerity? National Debt has been increasing £100bn per year for ecvery year of this parliament more or less.
Do you honestly trust that shower that is Milliband, Balls, Cooper and that slippery Chuka?
Re Ducks - agree.Prefer Geese myself as a duck isnt a deterrent whatsoever.
p.s I feel for the poor soul that is so thin skinned that they have claimed my prior message was "abusive". Hilarious,
Please, take this elsewhere!
I am as entitled as you to respond to a comment aimed at myself...especially as the impact of this election will be quite severe.
If you dont like it, tough.
Stop messaging me direct.
PP.
I think a Labour coalition is all but guaranteed - With those awful sweaties getting a disproportionate say over how England is run - personally I was all for them going Independent as it'd end any chance of this very outcome.
Given the financial mess Labour left this country in in 2010 (a mess LibCon have added to the tune tune of £700bn to National debt - what austerity?) its very surprising that they STILL garner 34% of the poll vote. Absolutely sholing indictment of the pig ignorance of a significant slice of the country's population.
This country cannot afford anothe Labour government so soon. But how we get out of this financial mess (National debt continuing to rise) with Debt Service interest costs c £50 billion per year, at such low rates beggars belied. What we dont need is more borrow and spend.
May I ask that we keep politics off this site, please, however strongly some may feel about the upcoming UK general election. There are loads of other sites more suitable for that purpose.
Agreed. Well said Jane. No politics unless relevant please.
Is anyone else trying to keep some cash back for potential heightened uncertainty closer to the election?
Ram & Cig, Thanks for your feedback. Experience with some Chinese stocks are quite scary.
Hi sirsege
Re. Galasys (LON:GLS) I had a quick look at Galasys and like most Chinese companies, it shows sparkling reported net profits but cannot convert this to cash. Free Cash Flow was negative in 2013 and looking at today's 2014 report, FCF is still negative. So the dividend they are proposing to pay is actually coming out of the net cash they raised last year.
IMO Chinese companies are best left alone. Going from recent history, the credibility issue is just too big.
Regards, Ram
Hi Paul, I know you are never interested in Chinese stocks. However, going through the RNSs from Galasys Plc today, 3 things caught my eye. 1. They seem to exceed broker forecasts for the year. 2. A subscription for its shares at 33% premium to its price yesterday. 3. The company that subscribed for the shares has some tie-up(awaiting ratification) with the online retail giant, Alibaba.
Your usually useful insight will be appreciated as usual.
It could be true, but:
- Exponential receivables: tick
- Insider control: tick
- Listed on wrong side of planet: tick
- No way to check the announcements are truthful: tick
Thanks for your thorough analysis of Safestay Paul, always appreciated. I'm going to go away and do a bit more research, do feel tempted to dip my toe in the water on this one.
James
Thanks for your report on Safestay today Paul - this is a new one to me, but looks like a fantastic growth company prospect. The thinking man's Snoozebox, I would probably say!
Francis
Hi Francis,
"The thinking man's Snoozebox" - brilliant! I like that description!
I think Safestay (LON:SSTY) is a much better & more reasonably priced growth prospect than easyHotel (LON:EZH) which was another not dissimilar IPO last year, but one where I think they were much too aggressive in valuing it, and pinned the valuation on Stelios's celebrity status, rather than hard facts.
Regards, Paul.
Why did the brokers cut their 2015 EPS forecast for Telit Communications (LON:TCM) from 0.27 in March 2015 to 0.2 in April?
This profile of the CEO of Telit Communications (LON:TCM) gives some history of the company. It's from their website - which is very informative.
---------------------------
Oozi Cats
Chief Executive Officer
Telit Communications PLC
Founder
Member of the Board of Directors
Mr. Cats, aged 53, has 25 years of experience in creating and leading business ventures. In 2000 Cats founded Telit, then an Israeli start-up for high level engineering and distribution in the field of wireless communications. In 2001 the machine to machine (m2m) department was born and first products have been engineered.
In 2002 Cats led Telit to acquire a bankrupt GSM/GPRS handset company in Italy and restructure its human resources & strategy to become an m2m platform. In 2005 Cats took Telit Communications PLC public on LSE (AIM) raising about GBP 20M. With the funds in place Cats globalized the company by adding to its cellular GSM/GPRS core competence also CDMA, EVDO, UMTS and later also HxPA & LTE. In 2006 Cats opened the APAC market, leading Telit to acquire the Korean market leader and started Telit USA in North Carolina. In 2008 Telit acquired a short range technology developer and is currently mastering also ZigBee and Wireless Mesh technology.
In 2011 Cats led Telit to a quantum leap with the acquisition of the Motorola m2m division, making Telit the largest Industrial m2m provider in the world. Later that year, Telit laid the foundation for its Platform as a Service (PaaS) division by acquiring Global Connect, then a tiny broker for connectivity services. In 2012 Telit acquired Navman Location Based Technology in California, adding another important and extremely synergetic technology to its varied portfolio. Before 2012 ended Telit acquired Chicago based CrossBridge Communications Inc., topping the already existing PaaS with additional substance. In 2013, the last piece in the PaaS puzzle was been put in place by acquiring Florida based ILS Technology, a unique Cloud based back-end service, making Telit a true Global leader in m2m One Stop One Shop.
Still in 2013, Telit announced the acquisition of the ATOP business from NXP, thereby establishing its global leadership in Automotive communication enablement.
Hi Paul,
on Symphony. I have never met them, but heard from a small cap fund manager who had met them, that the management were really poor, I believe his exact words were "if you could arrange for mgt to be accidentally run over by a bus, I might buy some of the stock."
There was also something odd about it, because it was winning contracts in countries that you would not associate with being at the cutting edge of environmentally friendly policies (eg oil rich Gulf states). I don't own it and haven't looked at it for several years.
Hi Paul -
I have been a long time fan of Telit Communications (LON:TCM) as it is the only major UK quoted player in the M2M (Machine to Machine) and smart sensors space. M2M and smart sensors are finding their ways in home appliances, cars and general gadgets. Personally I think the future is very bright for this technology. ARM Holdings (LON:ARM) 's sales of microprocesors for mobiles are levelling off and the company has started to develop processors for smart M2M devices.
DYOR.
Regards, Ram
Hi Paul, thanks for covering Universe (LON:UNG) Your thoughts are always interesting and informative.
re. Getech (LON:GTC) I like the argument put forward by a recent Sunday Times article on oil shares. The mega-merger of Shell/ BG will trigger more consolidation in this sector. The first step that the combined operations do is to cut costs and that means making less use of oil services.
I was already cautious about oil services shares before this. Now I am keeping double the distance and will wait until there is a visible sign of recovery before buying into the likes of Getech (LON:GTC), nothwithstanding how cheap they appear.
Regards, Ram
Hi Paul, any thoughts on Safestay (SSTY) would be very welcome. It's been on my watchlist for a while, just posted results today.
Thanks
James
The pollsters seem to think that we're in for a hung parliament. If so with that result and a period of horse trading likely before a government is formed it sounds like a recipe to create market volatility. Great for traders but a pain for everyone else until the market stabilizes.
Hi Paul,
Telit first started in Israel and have operations all over the world. They have focused on the IOT M2M since 2002. So they are no Johnny come lately to the party. I think acquisition wise they have been pretty smart. The company has a long term vision and until recently has been pretty lucky in picking up companies at a reasonable prices. I am not sure how cheap all those M2M IOT companies going forward considering the hype currently surrounding the sector. Most of their acquisition recently have been bolt on types helping to in niches and complimentary to their product lines.
The market leader Sierra Wireless , listed on the Toronto Stock Exchange, and company that most resembles Telit is not currently profitable making a loss of 37 (USD) cents a share. Estimated EPS for Sierra Wireless is $1.10 for 2015 and $1.53 for 2016. So we are looking at a prospective P/E 42.99 and 30.9. Relatively speaking I think Telit’s long term focus and good management makes a pretty inexpensive way to invest in a potentially enormous market. I also like the fact that the market seems pretty unenthusiastic about the shares.
I’s be curious to read your thoughts if you have a look at it.
Cheers,
The Brown government was borrowing 11% of GDP.
The previous Labour government in the 1970s required an IMF bail out.
That's a dreadful track record. A huge risk.
Mr Cameron should be shouting this from the rooftops. What are they waiting for?
Its interesting that market followers seem increasingly cautious with the FTSE etc at elevated levels and although I can appreciate this, the recent previous sell off's have usually rebounded well and I think that has a lot to do with the 'where else to i but my money' argument as no yield anywhere else really.
Paul are you concerned only with the election result or is there a bigger issue going forward that you see?
I've not remembered a period where everyone has felt quite so comfortable owning stocks and that should raise a red flag.
In my trading account I'm heading towards long/short at the moment. There's a concern about bull market age / lifespan as we've had an uninterrupted bull for the best part of 6 years now. I'm not very concerned from a valuation perspective in the UK or Europe, but I am about the USA... & when the USA sneezes everyone else follows - so there's definitely a risk of downside volatility.
On the other hand there is a lot of strength in breadth across the board in European equities, so I'm thinking of gradually becoming predominantly short USA stocks and staying predominantly long UK & Europe.
DYOR etc.
Thanks Ed. Im long to the gunnels on Europe and am dipping into Latam and Russia now as I think both a bit overdone on the downside. Funds only for the wild ride on EM but happily long of decent small caps with the usual strong characteristics of divi's decent cash flows etc.
The US isn't a particular worry for me personally as I don't have much on there at mom however the low oil price must be good.
cheers
I've made a conscious decision to ignore all general market predictions - why bother when it's nigh on impossible. Seriously.
To the best of my ability, I have a simple documented reason for holding every stock in my portfolio, including a basic risk analysis. When volatility comes along it's an opportunity to top up, or buy something new.
So there.
PS a CEO named Oozi Cats must rate Telit a screaming buy. DYOR etc.
The biggest factor on all portfolios is the impact of the overall market beta. If you are net long you are exposed to the market, so in a way you expect (predict) the market will rise.
Going long/short shifts portfolio bias away from being exposed to the overall market, to being exposed to the relative performance of longs vs shorts. I'm just happy to reduce my market exposure at the moment without reducing my QVM exposure.
Well the notional exposure to the market is only really relevant if you plan to liquidate the portfolio for spending soon. If you plan to spend in 20 years from now, you care about the price then, not the price now.
It's possibly relevant in opportunity cost terms (what else you could buy to replace stocks), but there's hardly any mainstream investment that's cheaper than stocks at the moment. Good take from Aswath Damodaran in that area:
http://aswathdamodaran.blogspot.com/2015/04/dealing-with-low-interest-rates.html
(Also his latest on the small cap premium, or lack thereof, may be of interest to the crowd here.)