Small Cap Value Report (Mon 8 Jan 2018) - HAT, SYS1, AVG, MTC, CRW, TST

Good morning!
Lots of trading updates today, so I will prioritise the companies I'm familiar with and which are most heavily requested in the comments.
I'm planning to start with:
- H & T (LON:HAT)
- SysGroup (LON:SYS)1
- Avingtrans (LON:AVG)
- Mothercare (LON:MTC)
Regards,
Graham
(Please note that I own shares in H&T)
H & T (LON:HAT)
- Share price: 338p (+3.5%)
- No. of shares: 37.4 million
- Market cap: £126 million
Another positive update from this pawnbroking group which I have held in my portfolio since 2013.
Profit before tax for the full year will be ahead of current market expectations.
The Group has delivered another good performance in its lending operations. The pledge book increased 11.6% to £46.1m (31 December 2016: £41.3m) as a result of the higher gold price, the concession format and an increase in loans on quality watches. The Personal Loans book has increased by 94.7% to £18.3m (31 December 2016: £9.4m) as a result of the expansion in our longer term, lower interest rate loan product.
Like its smaller rival Ramsdens Holdings (LON:RFX), H&T realised there were major opportunities in products related to pawnbroking. As you can see, its personal loans offering has taken off very well. I'm hoping to see it keep growing in size and maybe even start to rival the pawnbroking pledge book in the years to come.
Jewellery retailing is reportedly also going well, including through the development of click-and-collect online sales.
Finally, the outlook statement is confident. CEO comment: "Demand for our products remains strong and we look forward to the future with confidence."
You can see for yourself the evolution of H&T's earnings forecasts over the past year:
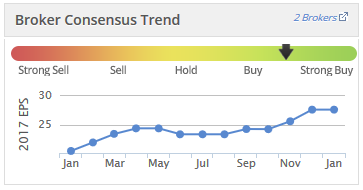
The updated EPS forecast now is likely to be pushing 30p, based on increasing another 7-8% from here.
Checking some gold/GBP charts, the average price of gold in 2017 was indeed materially stronger compared to 2016.
H&T has a lot more going for it, though, than just the price of gold.
The personal loan product (see here) is very competitive for that segment of the market which has been shut out by the banks. Daily bank overdraft fees can also have a huge implied APR, something which is easily overlooked!
Increased lending on quality watches is also worth a mention. When a customer presents an item to pawn, H&T has a facility which lets it send high-definition images of the item from the store back to central office, where jewellery experts determine its value. Expertise in watches is an important part of the company's overall offering.
The StockRank is still excellent:
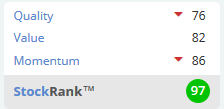
Funnily enough, I agree that Quality is not especially strong for H&T. It's essentially a financial firm, and it's never going to compound in value to generate exponentially larger returns, like some rare stocks can do.
But it is the undisputed leader in its sector, its management is highly competent as demonstrated by how they have navigated through both benign and difficult macro conditions, and it has discovered some exciting growth opportunities, particularly in personal lending.
On top of all that, thanks to the improved performance, the stock remains quite cheap on conventional valuation metrics, trading at a PE ratio of just 11x.
What else can I say, except that I'm a happy holder.
SysGroup (LON:SYS)1
- Share price: 320p (-17%)
- No. of shares: 12.4 million
- Market cap: £40 million
Yet another blow to shareholders from this market research/brand consultancy.
We've been covering it for a while here. Concerns have been plentiful:
- The rebranding from "Brainjuicer". It had a quirky, unique name. It changed this to a more generic name where it didn't own the .com domain. They are the brand experts, not me, but I preferred the original name!
- Very little visibility on sales. The company has been completely honest about this.
- As a people business, potential vulnerability to staff costs taking a big bite into profitability. In H1 2017, expenses rose due to staff costs. This unfortunately coincided with a 9% reduction in gross profit, producing a 70% decline in net income.
Today's announcement sees things getting worse:
Q3 trading continued to be worse than anticipated and, subject to its normal lack of revenue visibility, the Company now anticipates Gross Profit for the year to 31 March 2018 will be around 20% less than the prior year.
As the year has progressed, the Company has taken steps to reduce overhead cost growth. After overhead growth of 8% in H1 (with investment in headcount growth in the US and the Advertising Agency), we anticipate overhead growth over the year as a whole in low to mid single digits. On this basis the Company expects Profit before Tax for the full year to be a little over break-even (2016/17: £6.3m).
There has been a dramatic mismatch this year between the company's hiring plans and the business which actually came through the door, resulting in this collapse in profitability and now an attempted reversal of the trajectory in cost growth.
Profit before tax in H1 was £0.85 million. If the full-year result is "a little over breakeven", it says to me that the company is currently loss-making.
It's a remarkable change in fortunes for a company which had one of the most consistent track records in profitability over the past 10 years.
Checking the interim results, the company said the following:
Were the gross profit decline seen in H1 to be repeated in H2, then our profit before tax for the full year would decline by 50% to 60% (2016/17: £6.3m).
That was at the end of October.
For the company to now be saying that the full-year result will be close to breakeven, suggests a very bad lurch lower in financial performance over the past quarter.
What would concern me now is that if the company will have to reduce headcount, this will result in large severance payments, further reducing profitability in the short-term.
Of course, it's also possible that the company will make a speedy recovery, and that can't be entirely ruled out. It talks today about a new advertising product which it is selling to existing corporate clients, and which it hopes will generate more stability to revenues going forward.
But shareholders are right to be concerned. When news of difficulties in H1 first emerged, a more competitive market was cited as one of the reasons for the slowdown in sales. Every trading update since then is consistent with the idea that this company has lost its mojo and that competitors have caught up with its product offering!
It does have a strong balance sheet, with £4.6 million, so at least there is no question for now about it being in financial distress.
I tend to steer away from "people businesses" these days, but I'll continue to keep an eye on this, for signs of potential recovery. It's still conceivable that this year has been a particularly unlucky one.
As the company said in the interim results:
Whilst [the] variability in individual clients or markets can be marked, the positives and negatives have historically tended broadly to offset each other, and our results in aggregate in any 6 month reporting period have appeared more predictable and stable than in fact they are. Our order book and pipeline can change quickly, both for better or for worse.
Avingtrans (LON:AVG)
- Share price: 202.5p (+4%)
- No. of shares: 31 million
- Market cap: £63 million
Pre-close trading update and notice of results
This is an engineering technology group which recently took over Hayward Tyler (LON:HAYT) in an all-share deal. So the share count is a lot larger now, and the company a lot bigger, making prior-year comparisons difficult.
We shouldn't complain about that, as these complicated situations can sometimes make for good buying opportunities, if we are willing to do the work to understand them!
Performance so far this year is in line with expectations.
The key financial performance indicators of revenue, gross margin and EBITDA are all tracking the Board's expectations and the Company continues to secure new business in generally improving market conditions. A number of notable contracts were secured in the period, worth almost £7m in total...
Avingtrans had last-reported net cash of £26 million, while Hayward Tyler had net debt of £22 million at its last annual results as an independent company.
The combination of the two companies, therefore, has enabled Hayward Tyler to pay off its more expensive sources of funding, and also to renew its more attractive facilities, putting it back on a stable financial footing.
This is along with the other standard efficiencies you get from a larger listed company. Cost savings have been realised, as anticipated.
Therefore, the Board is pleased to report that the opportunities for the long term profitable growth of the enlarged Avingtrans group as presented by the acquisition are as expected.
I've just been reminding myself about the rationale originally presented for the deal. The idea was that the enlarged group, including Hayward Tyler (which designs and manufactures specialist motors and pumps) would become a leader in the nuclear power and gas sectors.
Hayward Tyler has a long history stretching back to the 19th century, and had a record order book when financial difficulties pushed it into the arms of Avingtrans.
The group is forecast to earn adjusted PBT of £2.1 million in the year ending May 2018, rising to £3.4 million the following year.
That's still not cheap on a PE basis, but it's worth bearing in mind that a decent chunk of spare cash might be left, depending on how much is being used to pay off Hayward Tyler's debts. This could enable a further acquisition in due course.
Overall, therefore, this looks interesting. I still don't feel sufficiently fluent with the story to buy the shares personally, but will continue to study it.
Mothercare (LON:MTC)
- Share price: 45.5p (-27%)
- No. of shares: 171 million
- Market cap: £78 million
This is a high-profile casualty of the decline in high street footfall. This chart tells the story of the past five years:
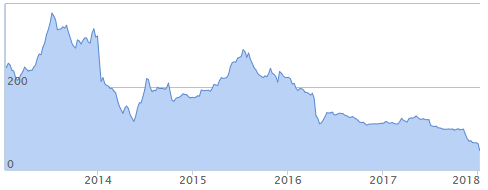
It wants to be "the leading global retailer for parents and young children", but the format isn't working as parents are clearly preferring to migrate to the Amazon Baby Store (external link).
And if the old, high street retail format doesn't work, it's not as simple as just setting up a website and enjoying online growth instead. You still need to match the cost efficiencies of Amazon.
Anyway, these results are worrying to say the least. For the 12-week Christmas period, UK like-for-like (LFL) retail sales are down 7.2%, and even UK online sales are down 6.9%.
However, as Paul has previously pointed out and as the company re-iterates in today's footnotes, sales on iPads in its stores are included in Mothercare's online sales. "Online" should really just include website sales.
With store closures taken into account, total UK sales are down 11%.
International retail sales also misfired, down 3%.
It strikes me that the company is striving to protect a brand that most parents don't care about:
In our UK business, we took a conscious decision to remain at full price to protect our brand positioning prior to Christmas but to then discount more heavily in the end of season sale. We have subsequently seen good progress with strong sell through rates on Autumn Winter clearance lines albeit these carry lower margins and will lead to a further reduction in full year margin as a result.
Protecting a brand makes sense in fashion, but does it make sense in baby products? I'm not so sure! I'd have guessed that most parents just want cheap prams and car seats which meet basic levels of safety!
So I don't see this company recapturing mass-market appeal. Maybe it would be better off deliberately targeting the much smaller niche of wealthy parents who are willing to pay up for a brand name and for in-store customer service, rather than pursuing its current strategy?
The company is loss-making and may not have all the time in the world to cut its costs. Besides a hefty pension deficit, its financial debt is growing, and now forecast to be £50 million at year-end in March:
We expect net debt at year-end of approximately £(50)m, and at this level we have sufficient liquidity and covenant headroom within our existing facilities.
Can we conclude from the above statement that net debt higher than £50 million might not allow for sufficient liquidity and covenant headroom?
Net debt was c. £38 million at H1, so it is set to have grown at c. £2 million per month during H2.
Last year, its facilities were increased to £67.5 million (£62.5 million revolver plus £5 million overdraft).
So my conclusion is that it will have £17.5 million of headroom at year-end. It will then face into the seasonally more difficult H1 period. On this basis, it's not hard to imagine the company needing to raise more equity in FY 2019. I would not choose to put any more money into this company with its current strategy, but hopefully it will be up to shareholders to decide!
Craneware (LON:CRW)
- Share price: 1598p (+4%)
- No. of shares: 27 million
- Market cap: £431 million
Trading Update and Significant Contract Win
Craneware is a successful company providing software to US hospitals.
This update confirms that management is confident in meeting market expectations for the full year, based on the first half which has just ended in December. The forecast on Stockopedia is for revenues to climb to $66 million, up 14%.
H1 revenue growth has been a little stronger than that, up 15%-18%, so given the "confidence" expressed today, maybe we can pencil in a potential earnings beat here?
We also read about a "significant contract win":
This contract is expected to deliver in excess of $16m of revenue over its initial five year term as Craneware's Value Cycle solutions are utilised by over 75 new facilities across the Network.
Note the "initial five year term". Craneware makes great play of its revenue visibility, and this is likely to be well-justified given the nature of its customers. Hospitals are sticky, much like the public sector (see £IDOX). Projects can last for years, and customers can easily stick around for a decade.
Quickly reviewing the Craneware service, it helps hospitals improve what it calls their "value cycle". This is described as follows:
It includes traditional RCM [GN note: revenue cycle management] components such as pricing, charge capture, claims performance and compliance, but also addresses additional dimensions, such as: quality of care, patient satisfaction and engagement, clinical outcomes, operational efficiency and risk management.
If it does what it says on the tin, this makes it a highly sophisticated offering. Perfect for the healthcare system in the US which is still majority-owned by private institutions and based on the private healthcare model.
Long-term, I wonder if Craneware could make inroads into the UK/European public hospital sector? Or are the differences in how they are operated too deep? It has previously described the NHS as a growth opportunity.
For now, this remains a highly-rated and high-performing growth stock. Valuation is about 40x on a PE basis, using figures for the year ending June 2018. On a "next 12 months" basis, Stockopedia puts the PE at about 36x.
It has accumulated cash of $50 million, and the strength of the performance is illustrated by these quality statistics:
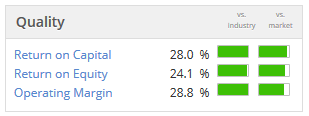
Conclusion - I'm struggling to come up with something less obvious than the fact that the shares are fully-valued at this price.
Checking the archives, I last covered Craneware a year ago, when the stock was trading at 1350p and the PE multiple was just over 30x. At the time, based on the company's terrific track record, I said "it would not surprise me at all if the current share price was a fair entry price".
With the shares now around 1600p, I wouldn't feel in any rush to buy into this. Valuation is now pushing the boundaries of credibility, even given the excellent company that it is. That said, long-term holders will feel justified in continuing to hold.
Touchstar (LON:TST)
- Share price: 76.5p (+13%)
- Share price: 6.3 million
- No. of shares: £5 million
I'm mentioning this tiddler for the sake of completeness, as it is probably too small for most of us to consider investing in.
It was formerly known as Belgravium Technologies, before changing its name in 2016.
The full-year adjusted profit after tax is forecast at £400k, in line with expectations.
This implies a significant improvement in H2, as the equivalent adjusted H1 figure was just £133k.
Note that the company was in fact loss-making in H1, due to some exceptional costs.
It also announces today that it has rolled out its retail software to the Sri Lankan Airlines fleet, while there has also been a positive development with its fleet management system being taken up by a new client.
The metrics are potentially cheap here if the momentum carries through into 2018, for those who are willing to buy into such small companies as this.
Thanks for dropping by. You'll be in Paul's capable hands tomorrow!
Cheers,
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

74 comments
I didn't realise the lemonfool is actually live. I assumed it was just to save the TMF archives from disappearing. Anyway, for me that TMF chapter is closed, albeit with many happy memories!
PP.
Curiously enough the one thing that lemonfool _doesn't_ have are the TMF archives! At the point of closure there simply wasn't enough time to arrange a transfer and I assume the TMF boards have been deleted entirely.
Fortunately the waybackmachine was pressed into service to archive as many boards as it could and I believe that it captured a large number of posts.
e.g. https://web.archive.org/web/20170707054746/http://boards.fool.co.uk/
Damian
Smashing discussion here today, lots of interesting points made, thanks to everyone.
I like the idea of Stockopedia becoming the heir to the Motley Fool bulletin boards (now sadly closed down), for intellligent, troll-free discussion. We used to have some wonderful discussions on TMF, and that was where I learned so much to get me started as an investor. There were many experienced investors there who were happy to share their wisdom & insights with the next generation. So it's nice to see that many TMF folk have migrated here!
Regards, Paul.
its also fair to say many TMF people have also migrated to TLF (the lemon fool) site.
i find this stocko site excellent also .
Motley Fool forums live on there: https://www.lemonfool.co.uk/
Indeed Paul, and without wishing to swell your head too much, I think you have a lot to do with that.
I became a bit "dormant" sometime before TMF closed it's doors, but I did keep up with your blogs from time to time and had you not moved here I might not have found stocko - I tend not to "do" subscription sites.
As a couple have mentioned, some of the more "social" aspects of TMF have migrated to lemonfool - although I joined, I have been less active there, so I don't know they quality of their stock analysis, but I have seen some good stuff on more general personal finance (and more).
I will be a bit quieter (probably) over the next few weeks as I'm dealing with a family bereavement - but will still be lurking and maybe chipping in a little.
With everything going on line, what will happen to all the high street shops.......
Cisk. I agree with most of your comments, especially so re going against the herd. The best time to buy is often after big falls if then most of the bad news looks priced in.
e.g I bought back Revolution Bars around £1 based partly on Paul's comments but I also always do my own research including Stockopedia figures and info before buying.
I also agree re some low ranking shares. E.g stockopedia marks/figures for early stage companies with great promise are likely to be low.
Do you have any data to support your thesis? Are all falls equal? How do you know the bad news is over?
"So I wonder how many people might be tempted to catch the falling knife at Mothercare (LON:MTC) , Debenhams (LON:DEB) or Carillion (LON:CLLN) for example? Or overpay for shares in companies which are inflating their profits? I think it's very important that we assess them impartially & logically here, and flag up the risks."
I think this is very important. All sorts of opinions fly around the board which is healthy. But often the opinions are based on misunderstandings.
e.g. from their comments some people have the impression that Debenhams are a company stuck in the past when in fact they have a very successful digital arm, if you go by sales revenue. By Gross Transaction Value the on-line side of Debenhams is bigger than BooHoo's revenue despite BooHoo's fantastic growth. Some people say that the consumer wants experiences rather products, but if you look at what Debenhams is trying to do at least in as far as is articulated by their strategy they are trying to embrace that. Others have made fair mention of the legacy from the PE days and long leases.
I think it is very valuable when Paul and Graham take a look at all these different situations as they often manage to cut through the numbers to see where the financial problems or positives lie and that is as useful for potential turnaround situations as for high flyers.
I held some Debenhams (LON:DEB) for a while to see if the CEO from Amazon could affect a turnaround. But it became clear that there are so many legacy issues it wasn't going to happen soon enough and so sold out.
However, if this got bad enough to go into administration I could see the on-line business coming out the other side, shorn of the physical stores, as a nice viable business.
One way or another, I don't think ignoring companies simply because the prospects for them right now is particularly helpful.
Strongly agree re Paul and Graham covering bad companies too. I don't and won't hold any share they give a strong thumbs down and on rare occasion of holding one, sell at once. With so many quality companies to invest in why hold on to potential big losers? I'm not bothered if the share price of the odd bad one subsequently goes up. It's pretty obvious that the higher the quality of our portfolios the greater the chance of them doing well. Also I find the analysis from Paul and Graham so informative and educational, including the way they comment on stock rankings of some of the shares covered. And some of the comments are such good quality too.
Ken, Paul and Graham provide a superb service with the daily reports, often entertaining and always informative, and the reports have helped me a great deal over the years.
But I guess one of the ways they have made money over the years is to go against the herd, buying unloved companies, when others wouldn't.
Personally I would never not buy a company because they gave it a strong thumbs down, or sell it if I already owned it; conversely I wouldn't go ahead and buy, just based on their positive commentary. I do however use their comments as a pointer for further research, as I do for stock ranks. However some of my best investments have had low stock ranks and, on the surface, would appear not to be of great quality.
But each to their own, the best thing for me about the site is that it's a community, you develop your own investing style and have some fun while doing it!
A view on Mothercare from the school gates, is that shoppers will visit Mothercare, check out the latest, see if they can get similar round at Halfords, or next. Prices are not very competitive, and with young tots, growing fast, you have to consider this as a customer. I always get the impression Mothercare feel they are too big to fall, a little like marks and Spencer’s.
the best value in the retail sector for me is JD Sports Fashion (LON:JD.) at the moment. they posting their results next week and im sure it will do well. the share price has been down for a while and be interesting to see what it does.
Hi vik2001.
At risk of being a pedant, JD Sports Fashion (LON:JD.) is currently ranked 37th of the 44 Speciality Retailers by “V” score. Plenty going for it otherwise but not necessarily “good value” at the moment.
https://www.stockopedia.com/sectors/specialty-retailers-534030/
Gus.
At risk of being a pedant, JD Sports Fashion (LON:JD.) is currently ranked 37th of the 44 Speciality Retailers by “V” score. Plenty going for it otherwise but not necessarily “good value” at the moment.
I don't think the V score means a lot on it's own. One persons idea of "good value" can vary greatly with someone else's. The V Rank is just a number generated by Stockopedia based on traditional concepts of value. I would imagine JD Sports Fashion (LON:JD.) suffers by having a low dividend yield compared to other retailers but some people would not be bothered by that, or factor it into their own calculation of "value".
All the best, Si
Hi Graham - Thanks for covering H & T (LON:HAT)
There is a useful feature on Stocko which allows you to compare shares side by side. I did this earlier for H & T (LON:HAT) and Ramsdens Holdings (LON:RFX) . Generally speaking the differences could be explained but one metric doesn't make sense to me.
The cash conversion cycle for RFX is gven as 69 days, but that for HAT is 450 days. Assuming that the maths are correct, what could account for this glaring difference?
Thanks, Ram
H & T (LON:HAT)
I have a theory that the low unemployment nbrs do not reflect people in well paid full time jobs, I believe there are a growing number of people in zero hours contracts/gig economy jobs/part-time work, and I believe the rise in populism is a reaction to inequality. These 2 themes make me believe that there is a growing number of people who might need to goto a pawnbroker/cannot get a bank loan and I believe this 'ahead of guidance' trading note backs up my theory.
If AI and robots (automation) leads to further headwinds to people having well paid, full time work, then the future looks even more positive for HAT.
ABC
I agree its surprising that Craneware (LON:CRW) didn't issue an above expectations statement. However, they've been pretty clear about the value of the new contract (worth 5%+ p.a. on revenue) and trading for the first half. Maybe they will let others revise up expectations for them. Unlike others, this is not currency assisted as they report in USD already.
Operating margins, FCF margins and returns on capital are not only high but have been on a rising trend. All we need now is to see an effective deployment of that large cash pile.
Yes the P/E is 39 on Stockopedia but once you adjust for net cash and the likely earnings beat its somewhat less than that.
Touchstar (LON: TST) issued an update and is looking like an interesting turn-around business.It is profitable and I bought a few more this morning, but it is probably too small (market cap £4.25 mn) to come within the criteria of this site.
Richard
Hi Richard - thanks for suggesting Touchstar (LON:TST). I've written up a few sentences on it. As you say, it's a bit small for us here.
Cheers
Graham
Surely the point of the SCVR, as much as making money, is teaching and learning?
By ignoring bad companies, inexperienced investors won't understand what makes them bad. I really appreciate Paul and Graham's time spent going through balance sheets, explaining the accounting tricks and loopholes used to massage figures, their red flags etc.
Also, opposite to the point being made about bad companies coming good, is good companies that are bad - for example everything about Fevertree Drinks (LON:FEVR) looks amazing but is it worth its ridiculously high pe? My point being, "good" and "bad" are subjective (I'm not saying fevr are bad!) - most shares can be good or bad there's only the question of price..
IGotPoesJacket - Good companies generate or have the potential to generate a high return on capital over the long-term. Price is something else. Fevertree Drinks is generating a high return on capital. Whether it is over priced or not is a different issue. This is a very simple mindset and I note that I have generated a lot of negative feedback here. However, this simple approach has allowed Fundsmith to be one of the best performing funds in the UK. SCVR already follows this approach to some extent by dismissing resource stocks and some other sectors.
I agree learning about profit warnings is interesting. But a simple question is this. Would you prefer coverage of a company that issued a profit warning or a company with great prospects whose share price could double? I'll stop this debate now as it could go on forever!!!! This should be a thread for SCVR ideas. The main point though is that "selection is better than cure". Selecting good stocks at the outset generates fantastic results. You couldn't of lost money in Unilever for example.
Re: SYS1 & Fundsmith philosophy as discussed by ratioinvestor
I would certainly agree with ratioinvestor about the importance of ROCE and, as any of the thousand plus people who has been to a Fundsmith AGM will know, ROCE now seems to form the bedrock of selecting companies for quite a few investors (including myself). However, the point I would make is that there are other criteria favoured by Terry Smith including that the company should, ideally, be producing consumable type products and have large numbers of customers so this may help to distinguish between companies like SYS1 and Fevertree. Terry also favours very large companies, although I have found his philosophy also works for smaller companies, though as you might expect, the risk to reward ratio is greater for these.
Hi IGotPoesjacket
I agree and I like the commentary on “bad” companies and good. A good example was the on going commentary on Globo by Paul a couple years back, without which a lot of people here, I think, would have lost money.
As to Fevertree Drinks (LON:FEVR) IMO when you look their numbers, what they have done in five years (profits from £2m to £38m), there flexibility (they only employ 40 people), the managment and the addressable market, I do think that they are worth the PE but that is what makes a market.
I am long (very) Fevertree Drinks (LON:FEVR)
BW
Michael
Simona - thanks for that. Yes I agree bad companies are good to learn from. Ok so cover them too. But at least state in the list which are which. Not sure what is wrong with that? I think we can learn from bad companies in terms of what to avoid. The trouble is say around 80% of companies are low quality. So if we cover those in equal measure we crowd out the coverage of the good companies. There are relatively few high quality companies out there. The investors chronicle or media cover everything. Why not cover a lot but focus mainly on the most prospective investments? Or at least differentiate the poor companies from the bad ones. I have seen some good quality companies missed in this report in terms of coverage and that seems a real shame.
System1 - Someone elsewhere pointed out that this has a 100% quality rating on Stockopedia. This seems odd in light of the profit warning today. It might be interesting following this up. What caused the rating to be so high. It would be a learning exercise for me as I haven't looked into what drivers the Stockopedia's ratings. As someone else has stated the link of System1 is incorrect it so to a stock with a ticker SYS instead of the correct SYS1
Here's how they break it down
https://www.stockopedia.com/aj...
System1 QualityRank™ Components
I don't see what is wrong with trying to differentiate between good - high ROCE - and bad companies. This is how the best investors have done well - Buffett, Smith etc. But I have two thumbs down on my post so obviously people here don't agree with me.
FWIW I didn't give you a thumbs down but... I think we learn far more from companies that are in decline or turn out to be bad investments than we do from boring companies that just keep churning out good results. We also have to accept that there are a range of investors reading the SCVR including those who may be new subscribers that are not experienced in stock market investment, particularly in the small cap arena which is a real minefield. So IMHO it's important for Paul and Graham to analyse both "good" and "bad" companies equally.
I hear what you're saying, because I'm only interested in quality companies and somehow I have magically (through prior bad experiences!) avoided all of the small cap company frauds and blow ups over the past few years, however I realise that not everyone has been so lucky and it's really important that P & G bang home the signs that things were not right to help guide all to improve loss avoidance for the future.
All the best, Si
Excellent post Simoan
Thanks for the suggestions to cover Craneware (LON:CRW), I will cover it too. Cheers!
As a comparison to Graham's observation relating to earnings forecast, I present H & T (LON:HAT) 's smaller rival Ramsdens Holdings (LON:RFX) which was mentioned in the article.
Somewhat similar trend between the two...
SYS and SYS1 are two different companies. I think a few of the above links are pointing to SysGroup (LON:SYS) instead of System1?
Graham, Paul - Just my view and I am sure many people here would disagree with me. But I wouldn't look at companies like Mothercare in detail as I don't really see the point? Surely it is better to consider companies with good prospects and that are performing well. Mothercare is only worth covering as a case in point on what not to invest in. Or maybe the SCVR could have two types of companies.
Good - Craneware
Bad - Mothercare, SYS (I assume it is bad).
If it was me I would only do a few lines on the bad ones. Covering the companies like this helps us know what your angle is. I.e. whether the view is that this could be an investment prospect. Or the view is that this is a case on point on issues that need to be avoided.
Keep the reports coming they are great to read!!!
"bad" companies can make good investments... at the right price
Clouds - the most successful investors differentiate from good and bad companies. "Bad companies can make good investments... at the right price." Sure but you have to be really lucky. In Mothercare it would of been tough to make money in the last decade. In Unilever it would of been hard to have not made money in the last decade.
I don't see what is wrong with trying to differentiate between good - high ROCE - and bad companies. This is how the best investors have done well - Buffett, Smith etc. But I have two thumbs down on my post so obviously people here don't agree with me.
But SYS1 was good before it changed it's name from Brainjuicer, in the last 2 years the shares went up from 268p to over 1000p, it also still has a QR of 100. If anything it shows how quickly fortunes of companies can change, even well rated ones. I think a name change is a possible red flag.
SYS1 beats Fevertree Drinks (LON:FEVR) on many quality aspects: https://www.stockopedia.com/co...
So I can't agree with you there, ROC is over double FEVR's.
Also remember Globo that Paul cover extensively, I'm sure that saved some investors some money.
herbie47 - Sure but you are perhaps misinterpreting ROC. What investors are focused on is the ROC going forward. The historic ROC is an indicator of this but that is all it is. ROC is a "flow" measure.
If you look at my post what I said was that: "Good companies generate or have the potential to generate a high return on capital over the long-term." (i.e. the future)
Just because SYS1 has a higher ROC than Fevertree in one year doesn't mean it is higher quality. What matters if the ROC in the future. The recent update at SYS1 suggests that its ROC may not be sustainable.
Even more reason to cover it as some just go by Stockopedia ranks. Also the 98 figure is from the last TTM, so is hardly that old. Fevertree Drinks (LON:FEVR) had quite low ROCE a few years ago. I would rather they covered companies that are changing, good companies doing well don't need that much coverage. I'm interested in companies such as Boohoo.Com (LON:BOO) after their profit warning.
Fevertree's return on capital is listed at 47%. Hardly low. I am talking about the potential to generate high returns on capital over the long-term on a sustainable basis. Fevertree may have had a low return on capital before but it had the potential to generate a high return on capital in the future. I don't know much about SYS1 so can't comment there. What you want ideally is an historic high return on capital and the potential for this to continue. Failing that you just want the potential for a high and sustainable return on capital. There is no point investing in a company with a low P/E if profits are about to crash. It is the same with the return on capital.
Yes I agree but SYS1 had that, so I would be interested in whats gone wrong, last figs on Stocko ROCE:
38.6 20.1 41.8 53.3 46.8 66.9 98.1
Looks good does it not?
Hi ratioinvestor, thanks for sharing your view.
I do try to mostly focus on "good" companies. "Good" does exist on a spectrum, though, don't you think? It's not black and white. Some companies are just average. And some companies change in quality over time. The SCVR is a place where we try to figure out which is which.
Graham - I agree that you and Paul try to focus on good companies. I like the fact that resource stocks are ignored for example and most speculative stocks. I guess I would argue that there is a case to be even more selective. Blowing up companies like Mothercare are interesting to write about and provide lots of lessons. However, Mothercare could probably be summarised as "avoid high street retailers." I think SCVR report does better than most at being selective. I.e. Investors Chronicle and the newspapers cover everything. I'd just make the case to be even more selective. That way we miss out on fewer quality stocks. I.e. GoCompare.com, for example, wasn't covered (I don't think) after making a good acquisition. The Times newspaper covered it very badly. The stock is up about 10% since then and should have good future prospects. GoCompare is a high return on capital stock with good growth potential. To be fair though I think GoCompare is too large to be covered according to the £400m criteria so that is probably an unfair point!!! My bad.
Mothercare could probably be summarised as "avoid high street retailers."
I kind-of agree about ignoring Mothercare as it has been failing for some time and most that there is to say has been said. On the other hand it is big news today and it is interesting to discuss any read-across to other retailers (e.g. internet sales have no read-across because they include some in-store sales).
I strongly disagree about the sector in general - I have been very happy with my shares in Bonmarche Holdings (LON:BON) and Next (LON:NXT) . And of course Paul has a retail / fashion specialism.
I think it's essential for Graham & I to cover good and bad companies. It's easy to make money in a bull market. One of the key purposes of these reports is to help people avoid losing money - we've got a great track record on that, having spotted loads of dodgy companies & warned investors about the risks. The really, really crap companies we don't even bother mentioning, but there are plenty in between, which people might be tempted into, even though there could be serious flaws with the company's finances & reported accounts, which we'll usually spot & warn people about.
So I wonder how many people might be tempted to catch the falling knife at Mothercare (LON:MTC) , Debenhams (LON:DEB) or Carillion (LON:CLLN) for example? Or overpay for shares in companies which are inflating their profits? I think it's very important that we assess them impartially & logically here, and flag up the risks.
Also, occasionally there's a bargain. I owe Graham many beers over him flagging up GAME Digital (LON:GMD) here at 20p, which everyone thought was a terrible share. Thanks to his excellent analysis, I backed up the truck at 20p, and am now sitting on a whopping great profit, as it's risen to 56p.
I think we've got the balance right as things are, so we won't be changing the type of things we report on here.
Regards, Paul.
P.S. Also, by looking at bad companies, there is often read-across to other similar companies. So very useful to look at what's going wrong, and to avoid banana skins at other companies which may be having similar issues but not yet admitted the problems to the market.
the way you guys reported on GAME Digital (LON:GMD) was spectacular, the execution of the report and analysis was spot on, even more so was the timing..... whoever payed attention would have been on healthy gains.
I didn't get in on it, because I didn't really pay to much attention, as I didn't understand fully what a special situation was. But what a great piece on learning it was for me and I will look out for future special situations on this journey.
For those who missed GAME Digital (LON:GMD) , (or saw the trade too early , I bought in Q4 2016 iirc & scalped a quick 20% inc dividend in Q12017) there is a vastly larger US quoted but international comparison which is Gamestop Stock Rank 92 P/E sub 6 divi 8% actually growing (3Q’s on the bounce)and doing stock buybacks too, interestingly they have a fast growing collectibles division that is offsetting declines from online migration, there’s a November presentation here;
http://phx.corporate-ir.net/External.File?t=1&item=VHlwZT0yfFBhcmVudElEPTUyNjYzNTl8Q2hpbGRJRD02ODUxNjY=
I hold a lot and it looks standout value to me epic is NYSE GME
Hi rhomboid1,
Many thanks for flagging $GME - it looks quite interesting - very low PER and very high divi yield.
Looking at the figures, I'm not so keen on its balance sheet. At Jan 2017 it seemed to have $669.4m cash, and $815m in long-term debt, so overall a net debt position. This contrasts with GAME Digital (LON:GMD) which has a large net cash position, not far short of its own market cap (especially after recent £19m disposal).
Revenue streams at $GME look more diversified though, as you say. Also I note from the presentation that you linked to, it has short leases, so can exit from loss-making stores in a similar way to GMD's even shorter leases. I don't know how commercial leases work in USA, but would imagine not too different from UK.
The Stockopedia computers also like GameStop - check out all this green!!!
Anyway, thanks for flagging it up - looks potentially interesting, I might pick up a few on a spread bet.
Regards, Paul.
Absolutely agree that it’s a very good thing to look at both good and bad companies. Read through across companies in the same sector can help cut potential losses and, of course, identify opportunities.
It’s taken me years of investing to realise the way to make money is to minimise losses and run your profits. Such a simple concept but harder to put into practice! It’s been several years since I took a total loss (think silverdell was the last one...) and these reports help a lot in this regard!
Also I periodically look through my share sales, look at what’s happened since I sold, remind myself why I bought and sold in the first place, and hopefully learn a thing or two! IMO one of the best things about investing is you never stop learning.
Graham, thanks for the comments on Avingtrans (LON:AVG). Price has been weak of late, compounded by a lack of announcements on contracts from the company after the recent acquisition. And the board giving themselves options hasn’t helped matters. However they have a very good track record at spotting opportunities, building a business and selling it on favorable terms. I think the HYT acquision will be the same, hopefully time will show they got a bargain. It was a sound business hampered by a lot of debt.
Paul and Graham keep up the good work, always appreciated and always my first read of the day (especially now I’m 8 hours behind on west coast USA!)
Although you have made some good points your suggestions lean towards making Paul and Graham's SCVR a tip sheet. To my mind that is a danger. This is a site where data is provided so you can make your own decisions.
--------------------------------------------------
P.S. Just want to try this Edit function kindly pointed out.
Wow! Works!
There have been some good replies: 'Good' and 'Bad' being relative and changing places for the same company, ROCE based on TTM, importance of subtle signs of changes, so worthwhile discussion.
the analysis of bad co's is very helpful if you are short
If you're short in a bull market then you've more courage than I have.
(Good luck to those who are - I wish I had sufficient skill and courage to do it, and do it successfully; though I should think I'm deficient in both.)
I increased my holdings in Revolution Bars (LON:RBG) last week as it was looking like at value bargain at those prices, and still even today. Im long and awaiting for this to hit the 225p and above mark.
Another stock im trying to work out that I see could be a good investment is Stock Spirits (LON:STCK) as im sure their next results will be positive. But no position yet.
H & T (LON:HAT) please!
Revolution Bars Revolution Bars (LON:RBG)
So Revolution Bars may be in a sweet spot in the short term. Either a boost to the share price from a favourable trading environment.- if this has not materialised then perhaps a more vunerable take over target.
I hold a long position in REvolution
I see that McBride (LON:MCB) has warned on profits today. So its turnaround seems to have shuddered to a halt.
Interestingly, checking my previous notes on it here on 24 Oct 2017, the company stated then that it expected an H2 weighting for the year 06/2018. Here we are less than 3 months later, and the company has put out a profit warning. It looks to be about a 20-25% profit miss vs expectations.
I'm increasingly inclined to run for the hills when companies come out with the H2 weighting thing, as it quite often seems a precursor to a profit warning a few months later. It would be quite interesting to do a study analysing what happens next when companies mention that they expect an H2 weighting.
Regards, Paul.
Avingtrans (LON:AVG) please Graham
Good morning Graham
I would appreciate your views on Avingtrans (AVG) time permitting.
All the best
Hi jonno, I've taken a look at Avingtrans (LON:AVG). Let me know your own opinion if you get a chance! G
Happy New Year Graham,
Thanking for looking at Avingtrans (LON:AVG) Stainless Metalcraft was one of the first shares I bought, it would have been end 1987 after the "crash" They built the stainless bits in MRI scanners, which to be superconducting, are cooled by liquid helium to near absolute zero. Helium can find the smallest hole so you need to be a good welder! They were good metal engineers but perhaps not such good financial engineers and became part of Ferraris Group. Avingtrans (LON:AVG) were a shell company that bought a company (Jena something, was East German remains of Jenaer Gewindetechnik GmbH, previously Carl Zeis) and they bought various bits off Ferraris including Stainless Metalcraft (perhaps even all?) from memory they did the fiddly bits for the RB211 fuel injection system. About 12 yrs ago I did a comparison between boards of AVG and a software engineering company. One had 3 times more higher degrees and the other paid 3 times the salaries. I moved the money from the software company into Avingtrans (LON:AVG) Avingtrans (LON:AVG) selectively grew the aerospace division until in 2016 it sold off the aerospace (much composite rather than stainless) to PE. It had a pile of cash and returned half to investors and used some of the other half to buy Hayward Tyler (LON:HAYT) a specialist in pumps in nuclear reactors (not easy to send a man in to change a part!).
So the board of Avingtrans (LON:AVG) seem to have very good engineering backgrounds, rather than just accounting backgrounds, but have none the less gradually and directedly built up, sold off, swapped and "engineered" an interesting, very high end, business between nuclear and medical fields. I wish that I had topped up at 180p last month (well at least replaced the shares I tendered at 200p in November and was planning to buy back).
Well worth looking into, I hold and still looking to top up.
Regards, Seadoc
Hi Graham
Thank you very much for your insight. As has been mentioned the share is expensive on a superficial PE basis, but operates in niche and very specialist areas. It is also financially sound and given past performance has adept management. In a reasonable time frame I think that the current share price will look cheap. As you will have gathered I hold Avingtrans.
Thank you and Paul for your daily reports that I find invaluable in helping to inform my investment decisions.
All the best
Jonno
I have always liked Craneware (LON:CRW) , but with a forecast eps growth of only 8.6% and PE of 39, the valuation is too rich. I suspect even with today's bullish outlook, it will still remain too rich.
I like the look of Craneware (LON:CRW) too. It popped up on my quality/momentum screens last year and only really failed with the high P/E of 38 being out of line with 8% growth in FY18 and 15% in FY19. However it's a very bullish trading statement today with good trading momentum, contract wins and cash generation. The only odd thing is that they still expect to meet expectations rather than beat them. Maybe I'm missing something but the price has just broken through to an ATH this morning and I can see them going higher.
I'm also interested in H & T (LON:HAT) but I'm sure that Graham will cover them without prompting!
Craneware (LON:CRW) sales and EPS growth is soo consistent and the ROCE and ROE% soo high, that Craneware shouldn't really be valued as a "normal" company. It clearly has a wide Moat and operates on 3-5year contracts. Using a PEG type calculation it does look poor value , but because it is churning out wonderful Buffet style operating performance its share price keeps going up. I hold and brought some more this morning. Ian
I agree, Craneware (LON:CRW) is the type of company where one could realistically imagine steadily increasing earnings and dividends for the next 10 years+. If that happens then valuation today is largely immaterial. If growth grinds to a halt then valuation today gives a lot of downside!
I hold.
Key ones to look at:
Bango - I don't really understand this company and it looks over promoted at first glance.
Craneware - Just outside the £400m limit so not sure on this?
Dialight is maybe worth looking at?
A few profit warnings but not sure it is worth spending time on those? Mothercare etc.
Talking of read-across, H & T (LON:HAT) issued a very strong trading update this morning ("we expect the full year profit before tax to be above current market expectations"..
Bodes well for Ramsdens Holdings (LON:RFX).
Please DYOR. No advice given.
Morning all!
Even though it's not (yet) a listed company, nightclub operator Deltic has issued an RNS trumpeting strong Xmas trading;
The announcement does also mention refurbishments to their sites, so it looks like not a true like-for-like comparison. But, hey, everyone massages LFL figures, because there are no standardised rules.
There were press reports late last year that institutional shareholders in Revolution Bars (LON:RBG) (in which I hold a long position) rejected the Stonegate 203p cash bid, because they were warming to the idea of a merger between Deltic and RBG.
We've now had positive updates from both Deltic and Stonegate (see links below), suggesting that the premium drinks market is buoyant. That should have positive read-across for Rev Bars too, providing management was not too distracted by the bid approaches to take their eyes off the ball on managing the business.
Deltic trading update today
Stonegate trading update 4 Jan 2018 (many thanks to reader here who flagged this last week)
Therefore I've been increasing my position size in RBG, and it's now my biggest long position again. So you'll hear me screaming from miles around if it issues a profit warning!!
Regards, Paul.
Paul, it’s also worth noting that Be At One cocktail bars have experienced very good trading over the festive period. LFL sales +8.1%.
http://lunchbusiness.co.uk/be-one-reports-‘record-festive-trading-period’-sales-126
Hopefully that bodes well for holders of Revolution Bars (LON:RBG). I hold no position myself.
So, clearly tough market conditions cannot be a valid excuse if RBG do not report growth somewhere near that. The thing is, having low LFL growth earlier in the year how likely is it that this takes a big turn for the better over the festive period?
Paul,
Do you, do we, want to spend our money on experiences or goods? Lots of discussion in the end year/start 2018 financial press, most reporting a desire to increase experience over things.
This may explain Debenhams (LON:DEB) and Mothercare (LON:MTC) problems though I think this is more to do with internet buying. And in the case of Debenhams (LON:DEB) long leases taken on prior to the float for which (heaven forbid) there was some reason for that choice by the private equity company before float. Bought by PE at £1.7b sold on three years later at £2b. But the PE were more than happy with the deal and I would wonder what the benefit to PE could have possibly been?
But to return to Revolution Bars (LON:RBG) experience over things could explain the strength of the classier and higher price bars.
Regards, Seadoc
ps: I am also long Revolution Bars (LON:RBG) and short Debenhams (LON:DEB)
Based on my experience during the Xmas lull, the local revolution was doing decent compared to others. Wetherspoon was an easy winner but it always is!
I'm hoping for a decent result, if nothing else earn back the money I spent there!
Debenhams should no longer be in business - it's like Woolworths I think - personally I cannot isolate a reason to go there other than it is nearby, which does not extend to DFS Furniture (LON:DFS)/Card Factory (LON:CARD)/£dc (I hold DC of these and others too)
My view of retail is that you need to provide a reason to visit your store, whether that be experience/product/price and from what I can tell, a lot of retailers are providing neither of these and they are the ones that will get hurt.
If anyone has an ironclad way of identifying one from the other, would appreciate your insights.
Hit submit by accident so forgot to add tickers, but hopefully people get the sentiment.
My view of retail is that you need to provide a reason to visit your store, whether that be experience/product/price and from what I can tell, a lot of retailers are providing neither and they are the ones that will get hurt.
If anyone has an ironclad way of identifying one from the other, would appreciate your insights.
Hit submit by accident so forgot.......
For a limited time (one hour?) there is an edit button on your post (to the left of Report Link Share) which avoids the need for a second post to correct something.
I see - thanks for pointing out. Much appreciated
My morning smallcap tweet:
Mothercare (LON:MTC), Malvern International (LON:MLVN), H & T (LON:HAT), SysGroup (LON:SYS)1, Angle (LON:AGL), Tungsten (LON:TUNG), Dialight (LON:DIA), Maistro (LON:MAIS)
Mothercare (MTC) 12 wk trading: UK: rev -11%, LFL -7.2% including online -7%. Even online is down! Group rev -2.4%. Guidance: "we are not anticipating any improvement in the short-term market conditions for the UK and on this basis the adjusted group profit for the year is likely to be in the range of £1 - 5m."
Malvern International (MLVN) FY trading. H2 rev up over 25%. Exp FY pretax -£0.6m (-£1.3m). No F/C.
H&T Group (HAT) guides FY beat.
System1 Group (SYS1) warns again. Q3 trading worse than anticipated. Guides FY 'Gross Profit' down 20%, pretax a little over breakeven.
Angle (AGL) University paper shows Parsortix-based ARV7 test "may provide a wider understanding of ARV7 than other techniques with the potential for improved patient outcomes...estimates that an ARV7 test could save, on average, at least $5,000 per patient tested."
Tungsten (TUNG) At 31 Dec, Tungsten Network Finance total originated invoice outstandings £54.5 million up 89% on previous reported peak of £28.8m in the period to 31 Oct.
Dialight (DIA) warns on FY & CEO resigns. GUides rev £181m. "Dialight's recent product delivery performance is a significant disappointment to the Board."
Maistro (MAIS) - the new name for blur Group.