Small Cap Value Report (Thu 16 Nov 2017) - Keystone Law, NXR, SRT, VCP, CLG, MACF

Good morning!
To get you started today, here is the link to yesterday's article. I updated it in the evening, having run out of steam during the afternoon. It now covers;
Ab Dynamics (LON:ABDP) - results
GAME Digital (LON:GMD) - results (I added more to this section)
Wey Education (LON:WEY) - unnecessarily deep discount on placing
Walker Greenbank (LON:WGB) - profit warning
On to today's news...
NB. I tend to update the article header to show what companies I intend reporting on. So please refer to this before posting comments below requesting me to cover companies that I'm already intending to report on. Thanks!
Keystone Law
Intention to float - this announcement caught my eye this morning, and might be potentially interesting. Although I got burned on the disaster that was Fairpoint, which went to zero in the end. So I'm very wary of legal services companies.
Key points;
AIM, ticker "KEYS"
Expected to commence trading on 27 Nov 2017
Placing price 160p
Total shares after placing, 31.27m, market cap of £50.0m
Raising £15m (before costs) - of which £5m goes to the selling shareholder, and £9m goes to the company, however this is mostly (£7.4m) to be used to pay off shareholder loans. So in effect, most of the placing monies are to cash out the selling shareholder. Generally I dislike situations where an existing shareholder is using an IPO to exit, because quite often problems subsequently emerge.
Company will be debt-free after the above transactions.
Panmure Gordon is broker & nomad.
The business model is a disruptive legal firm, with its lawyers being self-employed and working from home. Therefore its central costs are low, and fixed. Also, the suggestion is that it can grow profits in future, from operational gearing - due to having fixed costs.
Good 3 year growth of 20%+ p.a.
Results for y/e 31/1/2017 - revenues of £25.6m, EBITDA of £2.1m - grrrr, why on earth do companies give us EBITDA, and not proper profit? This is such an annoying trend.
I would want to see proper numbers before considering investing here, which would be in the admission document. A point to note is that when private companies come to the public market, they often pay their Directors via dividends. So this can flatter profit figures, which need to be adjusted to include realistic salaries for Directors.
My opinion - I'm wary of all new issues, as quite a lot go wrong.
That said, in a bull market, many often go to a premium initially.
I like disruptive businesses, and the business model here seems to have been well thought-through - e.g. lower fixed & office costs, from having self-employed lawyers. There again, it's not exactly rocket science, and plenty of lawyers already work predominantly from home. I wonder also if there might be an issue with HMRC, who are clamping down on self-employment when people are actually really employed in all but name.
I also like that the lawyers don't get paid until Keystone receives payment - another sensible aspect of this business model. So this one might be worth a closer look perhaps?
Norcros (LON:NXR)
Share price: 177.4p (up 2.5% today)
No. shares: 62.3m
Market cap: £110.5m
Norcros, the market leading supplier of innovative branded showers, taps, bathroom accessories, tiles and adhesives, today announces its results for the six months ended 30 September 2017.
The company put out an H1 trading update recently, which I covered here on 12 Oct 2017 ,so I've just re-read that, to refresh my memory. Also a relatively big acquisition and placing was announced, which I covered here on 2 Nov 2017.
Here's the highlights section;
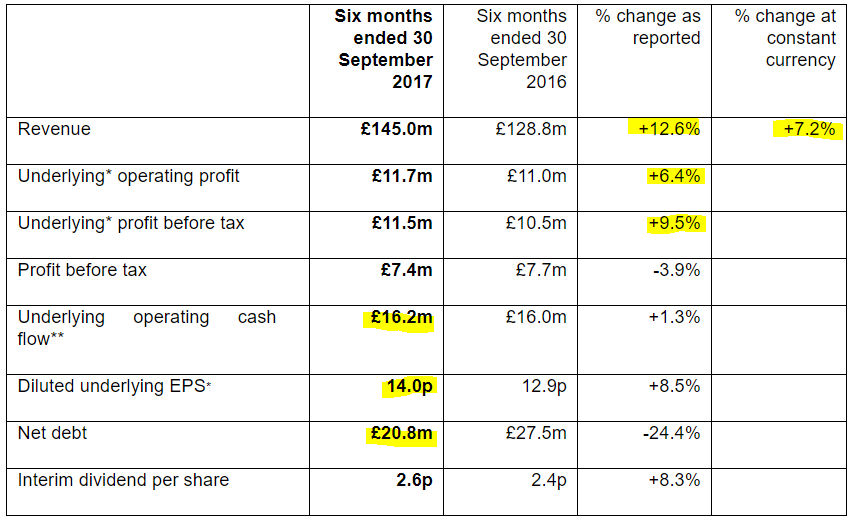
Note that revenues (and presumably profits too) are being helped by positive currency conversion. Although input costs will also be rising (since products are made in China).
Underlying profits are up, but not as much as revenues.
The business looks highly cash generative.
There's an up-to-date in line trading update;
Given the promising performance in the first half of the year, the Board remains confident that the Group will achieve underlying operating profit in line with its expectations for the year to 31 March 2018."
Full year expectations look to be 28.9p EPS, so that gives a PER of just 6.1 . As I mentioned a few weeks ago, this seems excessively pessimistic, but seems due to investor worry about the enormous pension scheme. Another investor worry seems to be that a fair bit of Norcros's operations are in South Africa - political instability there could be a concern.
Pension scheme - today's announcement says;
The gross deficit relating to our UK defined benefit pension scheme as calculated under IAS 19R has reduced from £62.7m at 31 March 2017 to £52.1m at 30 September 2017, primarily due to a 0.1% increase in the discount rate to 2.70% (31 March 2017: 2.60%) reflecting a slight increase in bond yields. Despite the small improvement, bond yields still remain at historically low levels.
We remain confident that our pension obligations continue to be appropriately funded and well managed, with the Company due to pay £2.5m this year into the scheme in accordance with the agreement made with the Trustee in April 2016. The next actuarial valuation date is 31 March 2018.
In the picture, I see the pension scheme being manageable. Also, as the company grows by acquisition, it is gradually diluting the pension scheme. Interest rates have at least begun to rise a little, so the trend is now possibly in the company's favour? The trouble is that, with such a large scheme(s), it only takes small movements in assumptions & bond yields, to make a big difference to the deficit. That could be good, or bad, only time will tell.
Acquisition - of Merlyn is a big deal, at £60m - roughly half funded by a placing, and the rest from bank debt. The bank facilities are growing to a hefty amount, but I'm very impressed that the bank is offering these facilities on an unsecured basis - indicating the bank has a lot of confidence in Norcros;
If approved, the transaction will be funded by a £31.4m firm placing, placing and open offer of ordinary shares and an amendment to the Group's unsecured revolving credit facility from £70m to £120m.
This is a very different attitude to how the banks were in 2008, and several years afterwards. So investors who were not investing during the financial crisis, should be made aware that credit can be withdrawn very quickly & easily if banks get the jitters in a recession. So I'm not keen on Norcros gearing up too much in the relatively good times. It's probably OK for now though.
Dividends - the interim divi is up from 2.4p H1 LY, to 2.6p H1 TY. There is a pleasing progression in the divis each year. The yield is healthy at about 4.5%. So this looks quite a nice GARP share, which also rewards shareholders with decent divis - quite attractive in a low interest rate environment.
Balance sheet - here are the usual key numbers that I focus on;
NAV: £65.2m
NTAV: £21.3m - which looks rather low for the size of the group, but the main reason is the pension deficit of £52.1m. So if we add that back, then NTAV without the pension deficit would be £73.4m, which looks fine to me.
Current ratio (working capital): 1.69 - which is very healthy.
Note that there is also £29.9m in long term debt.
Overall, I'm happy with the balance sheet, but we need to bear in mind that debt will increase by £30m with the Merlyn acquisition. That's probably at the top end of where I would want to see debt.
My opinion - I very much like the modest valuation here - very low PER, and a decent dividend yield, for a group which is performing reasonably well.
The main downsides are the huge pension fund (but it looks manageable) and the political risk from having a decent chunk of profits originating in South Africa.
As I seem to say every time I report on this company, I'm tempted to buy some! There again, with the UK consumer seemingly drawing in our respective horns, I'm worried that this could perhaps be the wrong time to buy a consumer-facing business. After all, we had a profit warning yesterday from Walker Greenbank (LON:WGB) which reported a sharp downturn in UK demand for its upmarket interior furnishings. Those problems could be limited to the luxury market, but what if it's the start of a more general trend of consumer spending reducing on things like kitchen, bathroom & other household revamps?
On balance, I'm probably not going to buy any, but it's a finely balanced decision. I reserve the right to change my mind at any time, as with everything.
SRT Marine Systems (LON:SRT)
You might be wondering why SRT is in today's article, given that I have already reported on its rather poor interim results here, 2 days ago. This is why...
CEO interview - I haven't really got spare time to seek out CEOs who want to do audio interviews with me, but I keep in touch with the old regulars, like John McArthur of Tracsis (LON:TRCS) and also Simon Tucker of SRT Marine Systems (LON:SRT). Both these CEOs are outstanding in their communications with private investors. So I quite like to chat with them every 6 months, and ask questions which are crowd-sourced from you, dear SCVR readers!
To save time, I now have a dedicated email address for my QualitySmallCaps website. So if you would like me to ask Simon Tucker your question(s), then please email me any time up to this Sunday at midnight, using this email address:
QSCquestions AT gmail DOT com (obviously, please replace the capitalised bits with the usual email syntax. I have just published it like that to avoid spam picking up on the email address.
NB. this is a non-commercial offshoot. I don't charge anything, and there are no adverts, I just like doing occasional interviews, it's interesting & sort-of fun. I'm not in any way endorsing or recommending any companies, of course. The website name implies endorsement, which was a mistake. I should have called it something else, but never mind.
Victoria (LON:VCP)
Acquisition - investors who backed Geoff Wilding's buy & build expansion of an originally small carpet maker, have been laughing all the way to the bank. As indeed has Mr Wilding, who has personally made £hundreds of millions on paper from his success here.
I won't go into all the detail, as it's moved way above my area of focus (typically £10-400m market caps).
What's so interesting about Victoria, is that it seems to have been an impeccable buy & build, which has created enormous shareholder value.
The share price has risen 7.7% this morning to 853p. The placing was at 783p, so people who backed that are already nicely in profit. The acquisition is due to complete today. No doubt brokers will be raising forecasts, since the deal is being part-funded with cheap debt, so is likely to be earnings accretive, even after dilution from the new shares for the equity element of the funding.
My opinion - well done to everyone who holds this share. I've nipped in and out a few times, thinking it looked too good to be true, but am now kicking myself about that. In this case, buy & hold would have been a wonderful decision.
The end game with Victoria has always been to build it up to an international group of carpet & other flooring manufacturers, apply economies of scale, synergies & best practice, then sell the whole group to (most likely American) flooring companies. So far everything seems to be going to plan, in what has been a remarkable success.
Who would have thought that carpet manufacturing could prove such a lucrative area? Apparently it is. I remember well my 1 hour meeting with Mr Wilding last year, and I was tremendously impressed. I'm sure once he's sold Victoria, all eyes will be on what he does next!
Clipper Logistics (LON:CLG)
Share price: 400p (up 1.3% today)
No. shares: 100.3m
Market cap: £401.2m
Clipper (LSE:CLG), a leading provider of value-added logistics solutions and e-fulfilment to the retail sector, announces an update on trading ahead of its interim results for the six months ended 31 October 2017.
Things seem to be going as planned;
Trading for the first half of the year is in line with the Boards' expectations, with growth in revenue, EBIT and net earnings.
The acquisitions of Tesam Distribution and Repairtech during the period have gone well, with both fully integrated and performing in line with our expectations.
Outlook for H2 sounds positive;
The Board remains confident that the combination of continued organic growth in the Group's sectors (particularly e-fulfilment and returns management services), new contract wins and the development of Clicklink will continue to deliver strong performance by the business in the second half.
That sounds to me as if the full year forecasts are probably well underpinned, and who knows the company might even beat them?
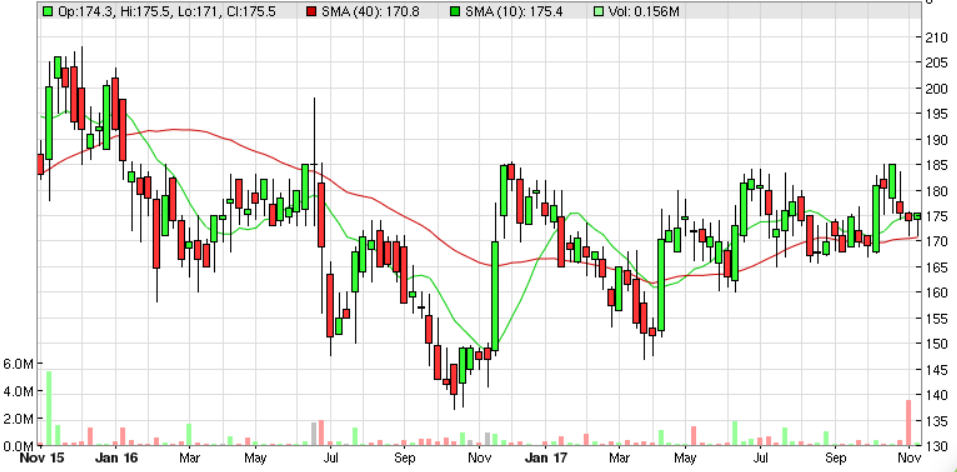
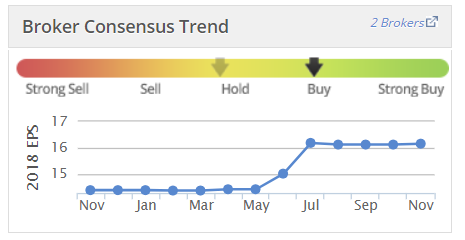
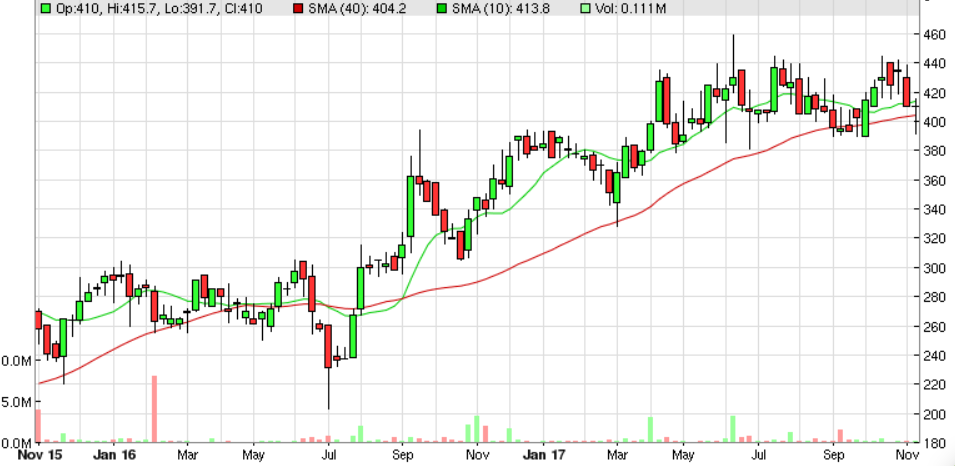
As you can see from the Stockopedia graph below, broker forecast consensus rose during the last 12 months. However, we have to be a bit careful, and remember that with groups that are making acquisitions, this may be acquired growth, as opposed to organic;
Despite having been fully listed since May 2014, I haven't written about this company before. This is a glaring omission, as it's right up my street - being a picks & shovels type company to the eCommerce & retail sectors.
Actually, I only noticed it recently when reading the Admission document for Sosandar (LON:SOS) (in which I hold a long position). Sosandar described their outsourced business model, with Clipper doing their goods intake, storage, and dispatching to customers. Plus I think they also manage customer returns - very important now, as online fashion involves a very high return rate of c.40% on average. Customers tend to deliberately over order, then send back the items they don't like, keeping the ones they do. That creates logistical nightmares for eCommerce companies. Clipper deals with all of that, leaving the client free to focus on what they do best.
Graham wrote a useful piece here on 25 May 2017, on news of Clipper making an acquisition. So that acquisition does seem to have been the catalyst from brokers increasing their estimates above.
Valuation - the forward PER has come down from 27, when Graham looked at it in May 2017, but is still quite high for what is basically a bunch of warehouses & 3,000 staff, moving stuff about;
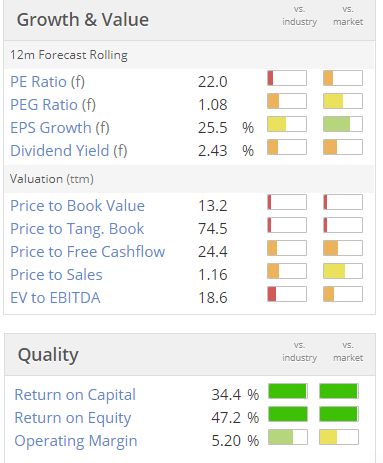
As you can see from the high P/NTAV, there's little in the way of asset backing here - the valuation hinges on profitability. The growth track record is excellent though;
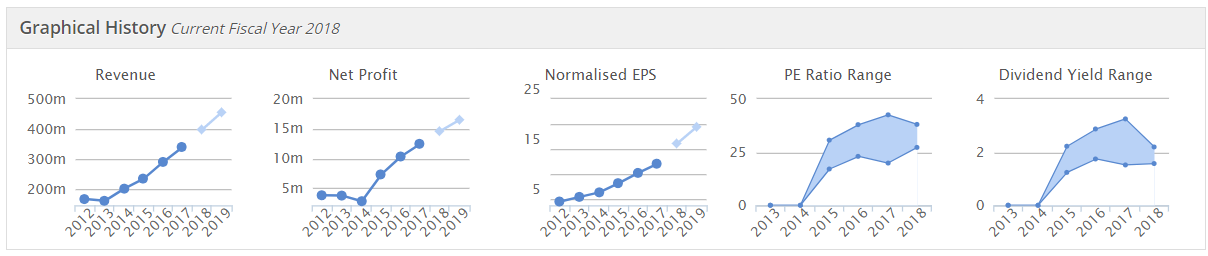
Even if some of the growth is coming from acquisitions, that doesn't matter, providing debt is not growing excessively. Note that EPS is growing strongly, which I very much like.
Balance sheet - I've looked at the last balance sheet. It's not great, with negative working capital. However, as we've seen with Wincanton (LON:WIN) , logistics businesses seem to be able to operate fine, even with a terrible balance sheet. The reason seems to be because customers pay up-front to a certain extent, before liabilities fall due. So negative working capital is probably not a problem.
There's no pension deficit here either. Borrowings look fine, relative to profitability.
Overall, there's nothing to be worried about with the balance sheet, in my view.
My opinion - I like this, and am kicking myself for not having spotted it earlier. Being focused on eCommerce, as well as conventional retailers, exposes the company to good growth. It seems to make a reasonable 5% operating profit margin - enough to be a decent business, but not too much to attract lots of competition.
Looking at Clipper's website, it has an impressive client list, and seems to be focused on IT - both in managing its operations, but also integrating with client systems, which is essential these days. I remember trying to manage outsourced warehouses in the old days of doing things manually, and it was chaos - everything was essentially done on trust, so you had no idea what stock the outsourced warehouse held, and they could have been pinching tons of us without us knowing. Things are very different now. It makes complete sense for growing eCommerce companies to outsource everything to Clipper.
At the current valuation, it's a bit too rich for me, but I'll put it on my watchlist as something to possibly buy on a general market sell-off. It could possibly be seen as something similar to Wincanton (LON:WIN) but with better finances, and faster growth. Whether that is worth paying a PER of 22, instead of a PER under 9, is the big question?
Macfarlane (LON:MACF)
Just a very brief comment to flag up this one as potentially interesting. I don't have time to crunch any numbers today, I'm afraid.
This is a packaging company based in Scotland. The company's performance looks very interesting, so worthy of a closer look some time soon;
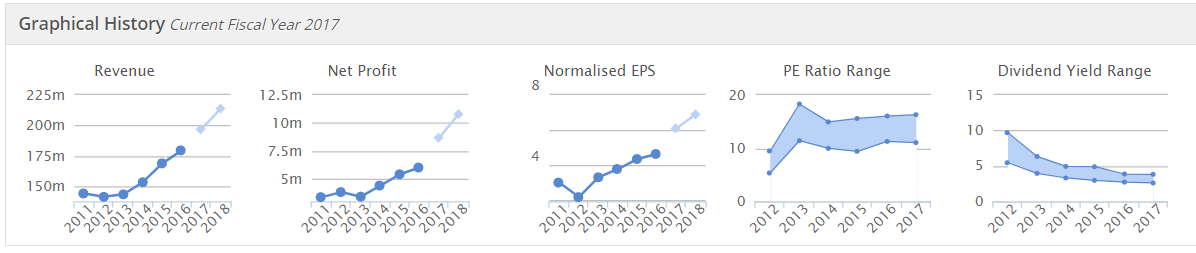
If forecasts are met (the lighter colour blobs above), then performance would look very impressive. Some growth seems to have come from acquisitions though. I haven't checked the balance sheet for debt.
Today the company says;
The momentum achieved in the first half of 2017 has continued in the second half of the year with improving organic growth and the continuing benefit from acquisitions.
The Board is confident that its full year expectations will be met assuming that the Group benefits from the trading cycle in the final quarter of 2017 through our focus on the e-commerce sector.
The net effect of these factors is that Macfarlane Group's profit before tax for 2017 to date is well above the corresponding period in 2016 with a good contribution from acquisitions and this trend is expected to continue for the remainder of the year.
Debt doesn't look to be a problem, relative to forecast profitability;
Bank borrowings of £14.6m at 30 June 2017 are expected to reduce by the end of the year, reflecting the Group's traditionally strong working capital inflows in the final quarter.
My opinion - this seems to be another company that has slipped through the net here. So I haven't looked at it properly for 3 years. The forward PER looks low, at 10.9, plus it pays a 3% divi yield. I like the update today, and the long-term growth track record looks good.
Add to that, a StockRank of 94, and "Super Stock" classification from the Stockopedia computers, and I really should add this to my list of shares to research in more depth. Can any readers give us a heads up on the company, perhaps?
I have to leave it there for today. Graham will be looking after you tomorrow, as is usual on Fridays.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

49 comments
Thanks for the SRT interview, Paul - very interesting.
I've been looking at Norcros over the weekend.
It's quoted EPS of 14p is on a Diluted underlying basis - the normal Reported EPS and Normalised EPS are much less at 8.6p and 10p according to Stockopedia interim income statements. I suspect the brokers target is on the same basis (see difference between TTM and 2018E) and explains the low forward PER of 6 - on a normal basis I would estimate 8+.
Phil
Norcros (LON:NXR) 's half year results are all the more impressive in the context of other home improvement companies issuing profit warnings. However, it looks like their revenue growth at constant currency is softening slightly:
15/16: +11%
16/17: +10.6%
H1 17/18: +7.2%
Fine for now in the context of a wider slowdown, but something to keep an eye on.
£ + Keystone Law = It will be interesting to see the 'Risk Factors' in their Admission Document in due course (I gather it's not presently available & I'll wager - Was not prepared by any of their Solicitors?!).
The business model has historically represented the 'Ubersiation' of legal services in the UK ('Solicitors on zero-hours contracts'), and has historically been greatly helped by a quite restrictive regulatory environment imposed by the Solicitors Regulation Authority (SRA) - Which has historicallyallowed Keystone's owner / manager to make high profits off the back of not particularly entrepreneurial lawyers who would otherwise have likely left the profession because they could not otherwise practise = No longer employed / in partnership and not able (for a range of reasons to self-employ - e.g. unable to manage a business / uninsurable etc.)
I've never understood how anyone would want an [individual] business advisor who is not able to establish themselves in business and instead pays a substantial proportion of their earnings for someone to undertake their admin! At least Barristers Chambers (much cheaper) have office space and provide real infrastructure to 'their lawyers'.
However, the regulatory landscape is changing fast, with considerable likely forthcoming de-regulation allowing individual Solicitors to compete with Keystone directly = https://www.lawgazette.co.uk/news/sra-relaxes-rules-on-client-account-and-where-solicitors-can-practise/5061500.article
This float largely looks like a 'knowledgeable cash out' by the present owner(s) / manager(s) leaving the 'uninitiated / ignorant' to buy into a business likely to be facing very different pressures in the future - compared with the favourable position they have historically experienced.
There is nothing very revolutionary about this business (Uber does at least have technology and it doesn't make money! = http://uk.businessinsider.com/uber-2016-financial-numbers-revenue-losses-2017-4)
Paul, re Keystone Law, I have been using them on a certain recent libel case. It looks like there will be a satisfactory outcome so I am happy. But I do like aggressive lawyers. Must have spent too much time in the USA.
As regards Wey Education (£WEY) one could argue at length about the placing price but it's a tricky company to value and I did not consider it worth anywhere near the market price before the placing, or now. Just looks like one of those stocks everyone thinks they have to buy so the price is driven by demand, not fundamentals. The riskiness of the business plan seems to be ignored. But one oddity is that the placing seems to be for acquiring a company which is not just unnamed, but the deal may not even happen. All rather odd.
I doubt I am alone in carefully watching your conduct in this libel case.
I would like to thank you for your great work with ShareSoc and sincerely hope that the case does not end up detracting from this or undermining its good name.
Leoleo73: ShareSoc is not directly involved in the legal case, and I think everyone will be satisfied with the outcome.
Norcros (LON:NXR). I'm still keen, but the increased gearing means I don't want to hold as much as before. I sold a chunk on announcement of the fund raise (at well above 172p) with the intention of just applying for the basic entitlement to bring my holding back to where I wanted it. But this morning I decided to apply for some excess entitlement as the odds seem in my favour that I'll be able to sell those again for over 172p.
So, like simoan, I am hoping some people won't take up their basic entitlement. But I am not hopeful since anybody not wanting more shares had ample opportunity to sell their entitlement ahead for a profit.
Macfarlane (LON:MACF)
I've held some of these since 29.3p (so a very long time). They've been boring, but pay out a reasonable dividend, so I've been happy to hold for the income. If it helps anyone, the two biggest weak spots in my opinion are the high debt + pension deficit (like NXR), "Macfarlane Gearing inc Pension Dfct % = 71.6" (although I'm tempted to see this as a small hedge against increasing interest rates), and the weak (negative) tangible book value. Last night I did my first monthly portfolio review for nearly three months, and MACF made it to my "sell if the price spikes up a bit" list. Maybe after this morning's announcement they'll get a reprieve!
BTW, I'm long.
Thanks for all the views Paul & everyone.
Thanks to everyone for their comments on Macfarlane. I bought a nice chunk of shares after they passed my system criteria 18 months ago but have felt a little disappointed by their lacklustre performance. Despite a recent encouraging heads up from Investors Chronicle I was thinking of selling but having read todays comments I think I will stay onboard for a while longer.
Re: Wey Education (LON:WEY)
If anyone is interested, the transcript of yesterday's interview with Chairman David Massie is here:
https://www.directorstalkinterviews.com/wey-education-plc-qa-placing-possible-acquisition-lonwey/412740113?utm_source=MadMimi&utm_medium=email&utm_content=Q%26A+just+published&utm_campaign=20171116_m142660401_DTI+Questions+%26+Answers&utm_term=Wey+Education+PLC+Q_26A_3A+Placing+_26+Possible+Acquisition+_28LON_3AWEY_29
I have some first hand experience of this market and the key issues worth noting include:
I don't know what their strategy is in detail but from what i read, there is nothing but alarm bells ringing.
Finally, he doesn't take responsibility for the placing deep discount but hides behind his broker decision. Not a leader I would want to back
So i sold out today
Wey Education (LON:WEY). If the directors participated in the placing then I will be particularly annoyed. But if not, then they have been diluted just like everybody else.
While the price action since the placing clearly demonstrates that it was priced too low in hindsight, I think it is particularly hard to gauge what the right price is to place a large amount of iliquid stock after a large speculative rise. Quite possibly institutions were sounded out and indications received when the price was lower, in which case it would have been difficult to go back and ask for more later.
Admittedly, it is easy for me to be relaxed about this as I was not a holder before yesterday (and therefore was not diluted), the placing allowed me to buy at around 27p, and I'm now looking at a good short-term profit.
I will try to write later about the business itself which I am very keen on.
Wey Education (LON:WEY) the business.
I spent a few hours researching them yesterday morning.
InterHigh
* There is a massive and natural moat / barrier to entry here. Parents are generally quite risk averse as regards their children and ideally want to see a track record before "sending" their child to a school. InterHigh have that track record. That is before you consider any expertise and technology investments.
* I had previously considered home schooling and never thought of or came across a virtual school as an option. This chimes exactly with what David Massie said in the interview - I think the return on advertising expenditure would be enormous in the early stages.
* Mumsnet has many wonderful stories about how virtual schooling has turned around the education of their child. This is a company that can make a genuinely positive difference to people's lives and if sanity prevails they should make a lot of money doing it.
* The prices are very low, yet they have good feedback and are making money. The prices are clearly much lower than the state can educate children, let alone a good private school. Indeed some children are having their fees paid for by councils. (Caveat: PE and things like after school clubs are not included and parents should be incuring some extra costs in providing the equivalent).
* The only negative feedback I could find was from parents who had signed up without reading the contract, pulled their child out (let's hope not to be home schooled) and then got upset when they were chased for money. Some said it was not for their child (as is to be expected), some said there were individual teachers who were not so good (like any school), but pretty much every feedback was positive.
* I can see it being ideal for parents who move around a lot for their work, or split their week between different locations or countries. (but there are legal risks as laws vary between countries).
* Home schooling in the UK is very lightly regulated, certainly compared to elsewhere. Although a potential threat I think InterHigh would benefit for any move towards more regulation as they provide much more structure than typical home schooling.
* The existence of high-quality provision like this can only increase the market for home-schooling to parents who would have never considered it before. Lessons are only taught in the mornings so it still leaves a lot of flexibility.
* Teachers have many of the same benefits as the children/parents - ability to work from anywhere (including a different country) and having more free time.
Infinity (selective education)
* This seems a natural extension with good synergies.
* Attractive to relative rich parents with an international lifestyle.
ecademy (business to "business")
* Again, a natural extension with good synergies.
* I can see this appealing to schools as a way to enlarge their curriculum, especially for smaller / isolated schools (e.g. the Scottish Islands).
Quoralexis (TEFL - Teaching English as a Foreign Language)
* Like fwyburd I am very sceptical about providing adult TEFL - I can see little synergy or competitive advantage there.
* I can see more potential for child TEFL and cross selling benefits, but I imagine this is still a very competitive market.
International (English education abroad)
* There will be regulatory / legal issues here. In the UK the rule is that children must be educated "at school, or otherwise". Effectively pupils are home schooled and use Wey as a resource. But in many countries attending a recognised school is a legal requirement: https://en.wikipedia.org/wiki/Homeschooling_international_status_and_statistics. In Spain it is thought that quite a few ex-pats illegally home school their children and they may have difficulty trying to get approval while facilitating illegal education.
* English schools in foreign countries are often much more expensive than private schools in the UK and are often not very good. So there is a good market here.
* Perhaps business to business is the best approach.
Hi leoleo,
A comprehensive list of positives for Wey Education (LON:WEY) re internet schooling. It looks like we've been googling the same things! I also grew much more positive about the company, the more stuff I dug up online.
One key point you missed, is that online schooling completely neutralises the whole issue of bullying, and disruption in classes. If a child becomes disruptive in an online school, the teacher simply silences them by clicking a button. So every lesson continues with little to no disruption. The children like this, and of course it's also great for teachers - they can actually teach, instead of spending most of their time battling to retain control of a group of rowdy kids.
WEY pays its teachers standard English pay rates, but they can work from home, and don't have any problems with disruptive kids.
The valuation of WEY is clearly almost a finger in the air job. It's clearly not worth anything like the current valuation on historic numbers. But people are buying into the great opportunity that it has going forwards.
Regards, Paul.
I exited Wey Education (LON:WEY) this morning having ducked in and out several times successfully over the last 12 months.
It could of course go a lot higher but I fail to see what the moat/barriers to entry are and I have yet to see anything about the management that convinces me they have done anything similar previously.
Clearly the broker/management did not expect the share price to run up to anything like this or they would not have placed the shares at such a large discount.
Wey Education (LON:WEY)
Wow: 104% one-year volatility according to Stocko! That is not one for people who want to use stop-losses. As Paul says, it is hard to value and that is basically what 104% volatility means.
Re: Clipper Logistics (LON:CLG) - this can also be compared with Eddie Stobart Logistics (LON:ESL) which floated earlier in the year and posted an upbeat 'contract update' this morning. Eddie Stobart Logistics (LON:ESL) acquired a company called iForce shortly before listing which does outsourced warehousing and returns for e-commerce companies, and also boasts an impressive list of clients.
Not an endorsement but in the interests of full disclosure I do have a long position in £ESL
Three other points about Keystone:
1. There are alot of virtual law firms so consolidation may be around the corner - see Excello Law and others.
2. Their model is the same as Barristers essentially - an office is still required - so hardly innovation as the Chambers model is Dickensian, if not earlier.
3.This sort of publicity is hardly reputation enhancing.
https://www.lawgazette.co.uk/law/breathtakingly-rude-law-firm-under-fire-over-insolvency-threats/5063160.article
Quick reminder - it really helps if people commenting can put the £ + ticker in every comment, so that it is clear what company you're commenting on!
It's so frustrating having to scroll upwards to find the original post, in order to work out what company someone is commenting about!
Thanks, Paul.
I think that Macfarlane (LON:MACF) is a great company. More info at the link below, and I will try and make time this month to do a more up-to-date write up on Stockopedia.
https://uk.advfn.com/cmn/fbb/thread.php3?id=33752357
Hi EC
I also hold quite a chunk of Macfarlane (LON:MACF) , as they grow they become a safer investment as they increase geographic coverage and widen the customer base, there’s a very useful presentation on their website following the recent results ;
https://www.macfarlanegroup.com/wp-content/uploads/2016/12/Interim-2017.pdf
All in all I think they’re v well priced for the growth and income on offer
I note Macfarlane (LON:MACF) has a large pension deficit. But yes it does look quite interesting now.
Hello EC,
thanks for your great work on the Macfarlane (LON:MACF) thread on ADVFN - not often that you can say good things about ADVFN threads!
I am quite satisfied with the steady progress at MACF, quite a turnaround over the last few years and I would prefer that progress at both the company and shareprice remains steady for years to come.
One of the few negative points is the pension deficit - and the substantial payments being made by the company at the moment. Worth bearing in mind though that not all pension deficits are equal - and note 10 to the final results is well worth a read for a surprisingly clear and understandable presentation of the defined benefit pension deficit. This fund closed to new members in 2002 and froze contributions in 2010.
The irony is that the assets of the fund are listed in the note and corporate bonds/gilts have been reduced to zero. Draw your own conclusion of the validity of the IAS19 calculated deficit (which assumes the entire fund is composed of corporate bonds/gilts to derive the present value of the liabilities)! Unfortunately while the deficit may not be real, the current payments being made by the company to reduce the apparent deficit most certainly are real.
cheers
Illiswilgig
Thanks, Illiswilgig - glad you found the Macfarlane (LON:MACF) thread useful.
Re: Norcros (LON:NXR). I know there are no other holders here, so there's not really any point suggesting it would be a terrible mistake to take up their entitlement in the open offer at 172p. Of course, I won't be subscribing for an excess entitlement, no siree, not me, who'd do a stupid thing like that? :-)
All the best, Si
@Simoan I hold Norcros (LON:NXR) and would be interested to find out why you feel this way. I plan to take up but not apply for extra. Unless I am missing something obvious (which might be sarcasm), I thought the results were decent if not good, and will help pension position. From a portfolio perspective it is getting sizeable as is construction/materials sector, so would like to cut some of the position, but as it stands I buy from 172 something I can sell for 176 (today). Not applying for extra - the size of acquisition and associated debt combined with pension is bit too much risk for me. Haven't had a chance to look through report in depth yet but nothing jumped out from numbers/discussion
Re. Norcros (LON:NXR), I hope the acquisition does not get voted through at the GM next Wednesday.
It is issuing its own shares at c. 0.4x sales to buy a company on 2.0x sales. Once acquired, Merlyn will then be valued on 0.4x sales. Destroying value.
If the valuations were the other way round, I would fully endorse the transaction. It would be value enhancing.
Also this valuation seems excessive given the current concerns associated with the UK consumer discretionary sector at the moment - see the sell offs at Topps Tiles (LON:TPT) and DFS Furniture (LON:DFS) as evidence. Additionally there should be a liquidity discount for the fact that Merlyn is privately held. And size discount given the smaller size!
Also the fees for the transaction are c.£4m. £NXR's current market cap is £110m so they are paying 3.6% of their current market cap for this acquisition. The only winners are Numis and the other advisers (and the sellers from Merlyn).
Nick Kelsall makes a compelling case for acquiring a shower tray and shower enclosure firm to complete their offering - but I fear he's chasing this at a cost to shareholders.
Very much agree with your 2nd paragraph and mimics what I thought when first announced. I was very anti at the time, given size/price/debt but have been coming round especially after a solid results and progress of past acquisitions. The revenue synergy is attractive and I don't doubt Nick Kelsall's salesmanship but he seems to have been pretty good with acquisitions too! Woud have much preferred a bolt on deal! Oh well - still got 16 hours to decide! Appreciate your perspective ley and others who have commented, and of course Paul!
It is issuing its own shares at c. 0.4x sales to buy a company on 2.0x sales. Once acquired, Merlyn will then be valued on 0.4x sales. Destroying value.
But that's only one measure of "value". Look at the operating margins of Merlyn which were approx. 20% for 2017 - way in excess of those of the rest of Norcros (LON:NXR). So it's clearly a company with some pricing power and differentiation in the market they operate which will further increase and diversify earnings.
In these situations, you either trust management based on their previous acquisitions (which have all been excellent) or you don't. At this point they have my trust based on their track record to date and so I'm happy to take up an excess entitlement, although I don't expect it to get filled.
All the best, Si
I'm happy to take up an excess entitlement, although I don't expect it to get filled.
Well, Happy Days! I didn't expect to get my full excess entitlement in the Norcros (LON:NXR) open offer, but did. I wish I'd asked for lots more because I'm surprised the market is allowing me to flip them for 176p right now. It's not often the market gives you a quick and very easy 2%+ return.
All the best, Si
Norcros (LON:NXR) When/if I take up an offer and if it is not a round number of shares then I tend to put my hand up for just a few more in the hope of ending up with a round number. From memory this was 10 for 51. I like the company, yield over 4%, PER in single figures and ROCE in double figures and I see the pension deficit as a bonus because I think there is every chance of discount rates climbing.
Paul - I understand the caution on Norcros. It is a view the market also holds with the P/E ratio having declined over the last few years. However, the homebuilding sector is continuing to grow and this is an area they are exposed to. They have also delivered with their last three acquisitions. The latest deal is expected to be earnings enhancing for the fiscal year to March 2019. Norcros is something of a "messy" story but appears to be priced for a disaster. All that investors need is for nothing major to go wrong and they should get a positive and decent return. However, the continued decline in sales for Johnson Tiles UK and Triton Showers is disappointing. When Norcros was listed in I think 2007 it was a fairly low quality business.
Thankyou to William O'Neil CAN-SLIM-esque screen. I had just finished reading his book.(How to Make Money in Stocks: A Winning System in Good Times and Bad, Fourth Edition) I,m working my way through other screen authors books and decided to buy Victoria PLC a while back after following his method for while. Up a nice sum today
Thanks Paul for flagging the IPO of Keystone; I had no idea they were planning to do this. The rules changed a while back regarding ownership structures for solicitors' firms, so it is interesting that finally these alternative routes are being explored. As a profession, we are not normally known for innovation... For me, however, I simply could not invest in Keystone. The middle/lower City firms have been under intense pressure for a while; which is why an increasing number of consolidations have taken place - see for example CMS Nabarro Olswang this last year. Niche boutiques seem to prosper, but general full service mid/lower market firms are suffering. I don't see anything innovative about Keystone, but am v happy to be proven wrong.
Re: Keystone.
I have a lot of experience in tech and disruption. Part of my investment strategy is to find disruptive technologies and I have invested in several, mostly UK based tech start-ups. In the course of this I have come across many trying to do this but so far I have not come across any of interest.
Having looked at Keystone, I would define their innovation as a "sustaining innovation", not a truly disruptive one. In essence this means their "business model" is the same as incumbent law firms (fees for time) but their operating model enables them to deliver this at lower cost.
The risk to them is that large incumbent law firms could quickly replicate their model; the opportunity is that they could be bought out by an incumbent.
Re Victoria (LON:VCP) Wilding is a very smart cookie. Today's acquisition of Keraben is big, on very good terms and multiples.
I took an intial position.
That is large, debt must be around £200m now? It’s not one me.
herbie - re, Victoria (LON:VCP) By my calc total net debt after the deal = 89m + 72m (new) = 161m
adj EBITDA 46m + 36m (my calc) = 82m
Which gives post acquisition, net debt / EBITDA ratio = approx 2. Well within acceptable range
But as ever DYOR
Does that include the CERAMICHE SERRA S.P.A. takeover for £50m?
Re. Victoria (LON:VCP)
Good point. The Ceramiche deal adds £32.6m to debt (rest is deferred consideration) , and adds £9.4m to EBITDA.
Add these to my previous calculations, and the debt/ EBITDA multiple still comes to around 2.
I would not use EBITDA it is not a reliable figure.
Not the sort of company I would want to be in dangerous times even if debt free.
Well momentum doesn't seem to care about EBITDA does it?
https://www.sharesmagazine.co.uk/events/event/growth-innovation-forum-2018
Hope this isn't considered bad form but I just noticed that this event is now open for registration. A number of frequently discussed companies are scheduled to attend including Bioventix (LON:BVXP), Cloudcall (LON:CALL), LoopUp (LON:LOOP), 1pm (LON:OPM) and WANdisco (LON:WAND). Having attended the previous event, I found it a useful opportunity to intereact with senior management.
It would appear I failed to read the fine print. None of the companies are confirmed as yet. They've just copied last year's list.
The Shares event looks interesting. Thanks for the info. I have just registered.
Victoria (LON:VCP) has just announced an acquisition and placing. Unlike Wey Education (LON:WEY), the placing was at yesterday's share-price, no discount, no premium.
I am mystified by Wey's chairman's explanation as to why the discount was so deep, saying this was usual practice. That and his explanation as to how they will use the funds left me underwhelmed. I am long but I'm beginning to question the quality of their management. Unlike Chairman Mr Wilding at Victoria, who seems to know exactly what he's doing.
Wilding is a former investment banker. He knows what he is doing, he got half the company for £20,000.
Morning Paul,
Come across a few this morning and although all 3 are "in-line", they do look quite interesting and unloved, from a SCVR coverage perspective.
Would much appreciate coverage of any or all of them.
Vitec 1045p – £479.9m – PER 14.3
Trading Statement – In-line.
Almost doubled in the past 12 months this is ticking a lot of boxes.
Clipper Logistics 395p – £396.1m – PER 22.0
Trading Update – In-line - With recent acquisitions integrated and also in-line with expectations. Board remains confident.
I really like this, it’s on my Watchlist.
Macfarlane 74p – £116.6m – PER 10.9
Interim Management Statement For The Period 30 June 2017 to 31 October 2017 – “Board remains confident that full year expectations will be met".
Always quite fancied this around the 60p mark with a, say, 50p Stop. There’s quite a lot to like, rising Revenues, Profits, EPS, a ROCE of 15%, a decent well covered 3% Dividend. Any downside is that 20% of Mkt Cap Net Debt but the ROCE of 15% means that’s less scary to me. Based on the fact it’s trebled in the past 5 years and it’s on a PER of 10 I wonder why I am not involved here from the 60p area (I've had my chances). This is still on my Watchlist at 60p but I am thinking, on a lowly PER of 10.9, it may well be worth raising the bar here.
Thanks in advance for any coverage.
My morning smallcap tweet:
Toople (LON:TOOP), Eastern European Property Fund (LON:EEP), Redt Energy (LON:RED), LXB Retail Properties (LON:LXB)
Toople (TOOP) 4 month trading. Orders still increasing month on month. "Digital marketing strategy has increased monthly customer lead generation numbers by over 100% compared to June...Despite the competitive market, monthly revenues have consistently exceeded £100k." In line? No indication.
Eastern European Property (EEP) will consult with holders on options to maximise value, inc de-listing and seeking an anchor tenant for the principal property in the short-term to facilitate a more attractive disposal in the medium-term.
RedT Energy (RED) wins first sales in Asia of its energy storage system.
LXB Retail Properties (LXB) Progress after a number of delays and unexpected costs. Rushden Lakes enhanced planning consent now beyond challenge. "That, coupled with further letting progress reported below, means that the revised agreement providing for The Crown Estate to fund the next two phases at Rushden Lakes is now unconditional...90% of the Phase 2 space is pre-let, with a further 2% in solicitors' hands. Phase 3 is 63% pre-let following the recent signing of an agreement for lease with Wren Kitchens for a 12,000 sq ft unit and another 20% is currently in solicitors' hands." I'm long.