Small Cap Value Report (Thu 30 July 2020) - NXR, SCS, IGP, VLX, AIEA, BLV

Good morning, it's Paul here. Many thanks to Jack for giving me a day off yesterday, which was much appreciated.
In the usual way, this is a placeholder initially, i.e. a blank post, to enable readers to post comments from 7am, whilst I write up the article gradually throughout the morning & early afternoon, section by section. For newcomers, I report on the day's small cap trading updates & results statements, plus any other important news.
Please see the header for announcements I'll be reviewing today.
Today's report is now finished.
.
Stockopedia App
Just to flag up that I downloaded & used the Stockopedia app on my smartphone (a Samsung M31 - which is a fantastic phone for the relatively low price) last weekend, and I found it excellent. I'm a bit challenged with eyesight, hence prefer using a full-sized PC or laptop screen, as opposed to a mobile device. However, with the Stockopedia app, I could see everything clearly. It spaces out the usual StockReport into a longer, thinner version. Also, I found the news pages very easy to scroll through - better than the full webpage actually, because the left and right pane scroll independently, whereas they're locked together in the web version of Stockopedia.
Therefore, I shall be using the Stockopedia app in future when I'm out & about, to do a quick research job on a share that e.g. a friend might have recommended over lunch. Something that should hopefully be happening more often again, if restaurants remain open. I'm not sure how long that might be though, with all these second wave outbreaks popping up?
(NB. I have not been asked to post the above, it's my genuine personal opinion, and thought it might be useful to flag up to readers)
.
Norcros (LON:NXR)
Share price: 164p (up 9% today, at 08:12)
No. shares: 80.57m
Market cap: £132.1m
Norcros plc ("Norcros" or the "Group"), a market leading supplier of high quality and innovative bathroom and kitchen products, issues the following trading update for the 16 week period ended 26 July 2020 ahead of its Annual General Meeting which takes place at 11.00am today.
Note that, with a end March year end, the current financial year began shortly after lockdown restrictions were introduced in the UK, and were introduced earlier than that in some other countries. It's also worth noting that a lot of DIY shops continued trading throughout lockdown, due to bing classified as essential. Hence Norcros's customers were probably less impacted by lockdown than other sectors.
Here is the very clear table, showing how revenues have bounced back strongly in June, and more so in July, which is actually running ahead of last year. I'm not sure if this is LFL revenues, or if there have been any acquisitions which help these numbers, it isn't stated either way, which is a bit of an omission. Maybe the company and its advisers could bear that in mind with future disclosures? Actually, that is relevant to all companies which are making acquisitions.
.

.
As we can see, the business has recovered quickly & strongly from the covid crisis. There might perhaps be an element of catching up, or pent up demand, from the sales increase in July, maybe?
Profitability - more important than revenues, yet so many companies are not telling us how they're performing right now. I can't be the only investor who finds this frustrating. So a thumbs up here to Norcros, as it says;
Overall, the Group broke even at the underlying operating profit level in May with a return to profitability on the same basis in June resulting in a small underlying operating profit for the first quarter.
Reading between the lines, this suggests to me that April was probably loss-making.
We have to be careful with operating profit now, as IFRS 16 messed things up by moving some rental costs into finance charges, which is below the operating profit line on the P&L. Hence there is a danger that post-IFRS 16, operating profit now over-states true profitability, although this issue is probably not huge in £ terms, but that depends how many leasehold properties a company operates from.
Liquidity -
Strong balance sheet and liquidity
As outlined in our year end statement of 25 June, in response to the sharp impact of COVID-19 we took immediate action to preserve cashflow and reduce costs. Group net debt has reduced to £35.2m at the end of June compared with £36.4m at the year end.
Net Debt: LTM EBITDA at the end of June was 1 times compared to 0.9 times at the year end.
["LTM" I assume means Last Twelve Months?]. There should be a rule that all abbreviations are asterisked with an explanation of what they mean, for all companies. Sometimes the abbreviation may not be obvious to some readers, so it's always best to provide an explanation, rather than leaving people scratching their heads. Maybe I should start a consultancy business, to help improve the quality of trading updates? It's badly needed!
Another glaring omission, is that we're not given any figures on stretched creditors. It's easy to report lower net debt, if you're not paying VAT or payroll taxes temporarily. Companies must disclose these figures, otherwise the positive cashflow is misleading, as it's benefiting from one-off concessions from Govts. All those tax creditors will be cash going out of the door in the coming months, and before end March 2021 at the latest - coincidentally that's Norcros's next year end date, so the year end balance sheet might not look so good for net debt as today's update.
My opinion - Norcros always looks cheap, because it has a large pension fund in deficit, and is materially exposed to South Africa, with the consequent economic & political risk. Media reports suggest S.Africa is in poor shape, with massive problems, including widespread poverty, still having economic apartheid effectively, and horrendous levels of crime & drugs. Therefore I can see why Norcros shares always look cheap.
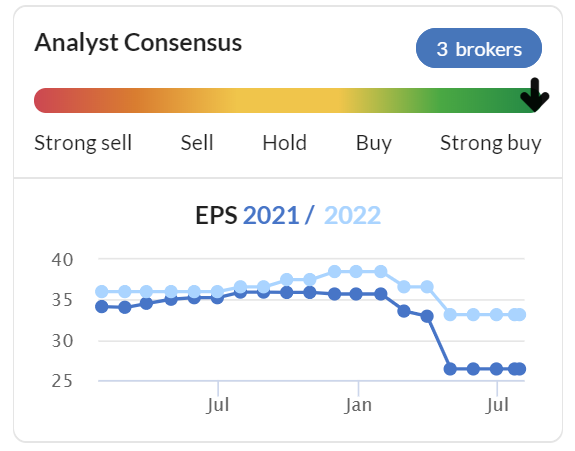
I always check the broker forecasts graph on the StockReport, to see if forecasts have come down significantly since March. IF they have, then this is a good indication that covid has been baked into the forecasts. If they're a horizontal line, then this indicates the forecasts are almost certainly out of date, hence need to be ignored. This tracks through to the valuation table & StockRanks on the StockReport too. Hence we need to be particularly careful at the moment, to double check everything.
.
.
As you can see above, forecast EPS came down a lot in March, so it looks as if the broker forecasts have indeed factored in some impact from covid.
The only thing I would question is whether Norcros might want to suspend, or reduce divis for a while? I would prefer it to preserve cash, by withholding divis, in order to de-gear, even if that means management taking some flak from income-seeking shareholders.
My opinion - I think this RNS is partially misleading, given that it doesn't say how much the company has benefited from stretching tax creditors. Also, it doesn't say whether revenue growth is organic or not?
However, now that we know it's trading profitably again, with a strong recovery in June & July, then debt is less important than previously.
Bear in mind that the pension schemes are likely to be a bigger problem, due to the effect of zero interest rates - these cause pension scheme liabilities to balloon. Although with equity & bond markets strong, then the pension scheme assets should have risen in value too.
The exposure to South Africa worries me.
I don't expect the bank to get difficult, seeing as current trading is strong.
You can buy it now on a PER of about 6, and the likelihood is that any future lockdowns would be far less broad in scale than the recent one. Hence future earnings should be able to rise. Overall, despite the issues flagged above, it still looks good value to me. DIY has apparently been doing well throughout lockdown, as people can always order stuff online. Being stuck at home twiddling our thumbs, there must be millions of people who decided it was time to revamp their homes, which should benefit Norcros.
.

.
Scs (LON:SCS)
Share price: 191.5p (up c.20% at 09:49)
No. shares: 38.0m
Market cap: £72.8m
ScS, one of the UK's largest retailers of upholstered furniture and floorings, today issues the following trading update for the 52 weeks ended 25 July 2020, ahead of announcing its preliminary results on 29 September 2020.
How about this for clarity? This table below is the best way of presenting revenue that I've seen so far, from all companies I've looked at. Simple and clear, to split the revenues into the 3 logical categories of pre-lockdown, lockdown, and post-lockdown. Please can all companies use this format for your announcements.
.

.
I had to look twice, are they really saying revenues are up 92.2% above last year, or are 92.2% of last year's numbers? This paragraph confirms, they are genuinely 92.2% up, on top of last year's numbers. We can reasonableness check this by looking at the full year figure of -5.9% down. That's only slightly down on the -4.2% down for the 34 weeks prior to covid. Therefore, this confirms that the post-lockdown period almost fully recouped the lost sales during lockdown. This is tremendously impressive.
Encouragingly, post-lockdown trading has been very strong both in-store and online, with Group order intake increasing 92.2% when compared to the same period in the prior year. This reflects pent up demand, which has been supported by our well executed re-opening plans, our continued focus on value and customer service, and our increased investment in targeted marketing over the last two months.
I can see why the share price is up 20% today, that looks fully justified by this outstanding update.
It reminds us that there is a time lag of orders received. Therefore the profit for FY 06/2020 is likely to be worse than the order intake table suggests. However, that benefits FY 06/2021, which gets off to a flying start. Therefore expect strong interim results for H1 12/2020.
Liquidity - strikingly good figures here, and a good explanation of its negative working capital model (being paid up-front, before product has been made to order).
Sadly, there is one glaring omission - no figures are given on the short term benefit of stretching creditors (VAT & payroll taxes). We must insist on companies providing this essential information please. As I keep pointing out, if sretched creditors information is withheld, then the cash/debt figures are misleading.
On 17 March 2020, the Group drew down £12m from its revolving credit facility ('RCF'). As noted in our trading update on 26 May 2020, including the £12m RCF, the Group held £48.3m in cash.
Since the end of May, the £12m borrowed under the RCF has been repaid and cash on the balance sheet has grown to £82.3m. This compares to £57.7m of cash at the end of July 2019. The increase has been driven by the Group's negative working capital model, benefiting from the order intake over the past few weeks, coupled with effective cash management actions that the Group has undertaken in response to the COVID-19 outbreak.
I think companies also need to think about the wider issue to society of holding back taxes, when they don't need to. ScS is clearly rolling in cash, which earns next to nothing on deposit. Hence why would they hold back payments to creditors? Companies which are cash-rich, should pay creditors on time, or even early (to e.g. help support small suppliers), even if they don't have to. Then trumpet why they've paid creditors quickly, to be socially responsible. Maybe ScS and other cash rich companies, are missing a trick here?
Outlook - too vague to give us anything useful. But I think it's safe to assume that +92% sales performance against last year is very unlikely to continue for long, since that must include a lot of pent-up demand from lockdown. Maybe ScS should raise its prices, if demand is that strong?
I think investors should ask for more clarity from companies. After all, companies are sector experts, so should have a good handle on what the future holds, even if it giving us a range of possible outcomes. Refusing to give any indication of the outlook, is not good enough.
Whilst it is too early to provide clarity on the outlook for the weeks and months ahead, the Group is encouraged with its trading performance since re-opening on 23 May 2020. The Board would again like to thank our colleagues for their ongoing dedication and professionalism during this time, as well as our customers, shareholders, and wider stakeholders for their continued support.
ScS is a resilient business, with a strong balance sheet, coupled with a flexible cost base, and is well positioned to navigate these difficult circumstances and maximise opportunities as and when they arise.
My opinion - I've been positive about ScS for a while, flagging it here as a good opportunity for recovery. So I hope some readers have benefited from today's share price rebound. It operates from retail parks, which are much better placed to recover, since they're big stores, with social distancing easy to do, and footfall figures show that customers have returned in greater numbers than to traditional, more cramped High Streets.
Also, as I've flagged before, ScS prices are low, hence I don't think its sofas & beds should be seen as big ticket items any more. All those millions of people locked down this year, would be more likely to replace worn out sofas, carpets, etc, than before. Hence lockdown may ultimately prove to be an overall benefit to ScS, depending on when the sales spike eases off.
.
.
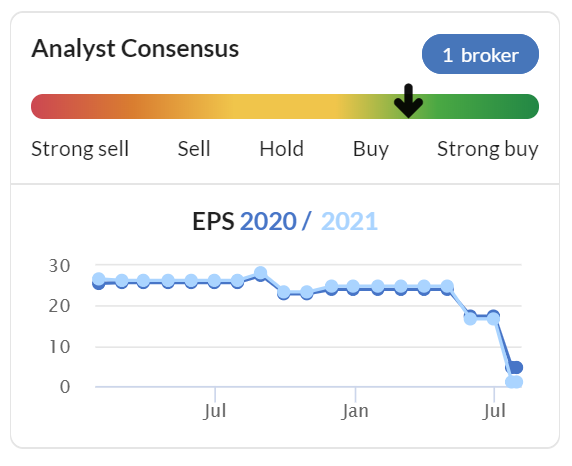
Reading today's update, it seems to me that FY 06/2021 forecasts are likely to be substantially raised (the lighter line above, for colour-challenged readers). Together with a balance sheet groaning with customers' cash, the valuation could be a bargain, even after today's 20% rise, perhaps?
.
Intercede (LON:IGP)
Share price: 75p (up 7% today, at 11:06)
No. shares: 50.5m
Market cap: £37.9m
(I'm long)
I don't normally comment on contract wins, unless it's something major, but in this case I've got a couple of broader points to make, so thank you for your indulgence.
Intercede already has a highly impressive client list (one of the main reasons I bought this share in 2018), including various branches of the USA Govt. These are long-term contracts, so very sticky, some having been running 10-15 years, or even longer. Plus there are some very big corporate clients, including 5 of the world's 6 largest aerospace companies. Therefore most of the cost base is covered by sticky, long-term recurring revenues. The company is now in year 3 of a 3-year turnaround under new management. The hope is that this should be the year that new clients kick in, with additional high margin contracts, once the product, processes, people, and finances were fixed in years 1-2.
Therefore it's encouraging to see a contract win announced today;
Intercede, the leading specialist in digital identity, credential management and secure mobility, is pleased to announce its involvement in a successful bid for a ten-year contract with the U.S. Department of State (DoS) to create an innovative Identity Management System and Credential Management System (IDMS) solution compliant with Homeland Security Presidential Directive 12 (HSPD-12) for the DoS and its customers.
Note that Intercede's main strategy is to sell through 3rd party systems integrators, with the Intercede software being a component within a bigger IT system. Here is the link to the overall project announcement, from a company called Guidepoint. I like that Guidepoint name checks Intercede's MyID product in the second paragraph - which is the new, mid-market product, designed to greatly widen Intercede's total addressable market, and MyID is quick & easy to set up, being standardised. Previously Intercede just went for the top end, high security market, with bespoke products. Hence this announcement is reassuring, that the MyID product is generating a contract win with another big part of the USA Govt. I know some people had concerns that IGP was perhaps legacy software, dining out on long-term contracts which were stimulated by a security push after 9/11. It's reassuring to see that it is still relevant for new systems today.
Guidehouse sounds like a substantial business. It was spun out of PriceWaterhouseCoopers, being their public sector division.
Headquartered in Washington, D.C., the company has more than 7,000 professionals in more than 50 locations.
The beauty of selling through third party systems integrators, is that if a project goes well, it is likely to lead to more business following on. Also as a small UK company, IGP couldn't possibly finance a worldwide sales team alone. In my various meetings with IGP management, and their RNS statements, they have stressed the importance of the partner sales channel like this. Hence it's a positive development to see this beginning to bear fruit. I'm hoping this might develop into a multibagger share, if sales really start to take off. But of course that can never be guaranteed, it's just a wish, supported by a good strategy, now it's all about execution.
A cautionary word - although this contract is pleasing, we're not given any financial details, and it was already budgeted for. Hence it shouldn't be particularly price sensitive;
Intercede expects to receive orders for software licenses and associated development, professional services and support & maintenance within the next few months; a portion of which will be recognised in the current financial year ending 31 March 2021.
The contract was included within the directors' expectations for the current financial year ending 31 March 2021.
The most recent information the company gave, was that the sales pipeline was up 40%, but Intercede does not disclose the actual amount of the sales pipeline. Hence I am hoping to see it beat expectations for FY 03/2021, which is only 6% forecast revenue growth on last year. On the downside, the covid crisis is bound to have delayed conversion of sales pipeline into sales.
My opinion - this is one of my top 3 personal holdings, because I can see the growth potential from the turnaround strategy under newish management. With such an amazing client list, offering numerous reference sites, and long-term customer stickiness, then the potential growth seems credible. Management were very cautious to begin with, but seem much more confident in the future in the most recent RNSs.
I was invited to join a Zoom company presentation for analysts & brokers recently. It was superb, and focused on introducing more members of the senior team, not just the CEO & CFO, and explaining the product. Cloudcall (LON:CALL) followed the same format recently in their webinar, and it works tremendously well, so I hope more companies adopt this format with online presentations. After the IGP Zoom call, I messaged the company to suggest it repeats the same format, and throw it open to all investors, so people can better understand what the company does, as it's not always obvious from RNSs. This included screen shots of the product itself, and the technical chap (whose name eludes me) gave a particularly clear explanation of the products. The slides were easy to follow too, so it definitely deserves a wider distribution.
The shares are horribly illiquid, so I've found that buying tends to require patience, on the dips. I recently bought some more for my SIPP, and the market makers took full advantage of me, increasing the price for any size, so think I had to pay about 5p over the market offer price, to get a decent quantity. Frustrating, but long-term, if things pan out as I hope, then paying 75p or 80p won't make any significant difference. It may not pan out as hoped though, I can't predict the future with certainty, nor can anyone else.
The issue with the convertible loans should sort itself out in about 18 months, as the company has enough cash to pay them off. Although apparently it will just be a negotiation between the company and the loan note holders (which includes Directors) as to who wants the cash, and who wants to take shares. The dilution would be unfortunate, but isn't huge, and would bring the benefit of a completely ungeared balance sheet.
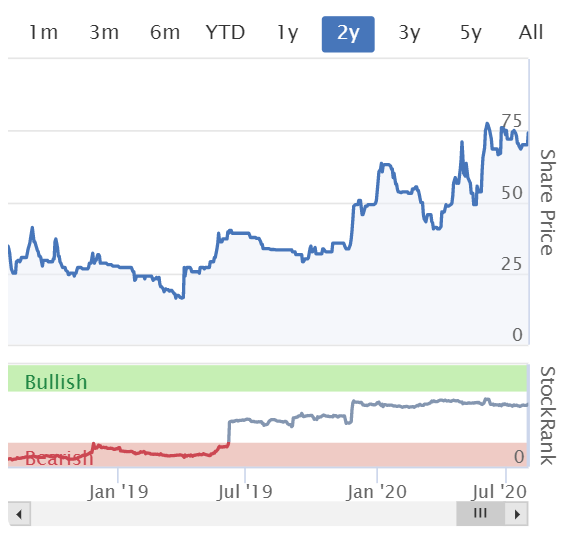
So far, so good;
.
Volex (LON:VLX)
Share price: 143.7p (up 4% today, at 13:11)
No. shares: 152.25m
Market cap: £218.8m
Volex plc (AIM:VLX), the global supplier of integrated manufacturing services and power products, is today holding its Annual General Meeting, during which the Executive Chairman, Nat Rothschild, will make the following statement on trading for the three months ended June 2020...
Recap - I briefly reviewed Volex's FY 03/2020 preliminary results here. The brief version is that I like the excellent turnaround progress, like the strong balance sheet, but thought the outlook comments were a bit mixed.
Q1 update today - very good in the circumstances, I'd say;
Unaudited revenue for the three months ended June 2020 was $96 million, which was flat on the same period a year earlier. Given the disruption caused by the global coronavirus pandemic, we are very pleased with this result.
Operating profit remains at a similar level to the prior year, and our cash balance as at 24 July was $30 million. Our $30 million revolving credit facility remains available and undrawn.
This shows a really resilient business, that (for many companies) the worst period in memory, due to covid, has seen revenue & profit flat against last year. Very impressive, I think.
Outlook - same points made as last time, but good to see things are improving;
As noted in our results statement on 18 June 2020, we continue to see weakness primarily in the medical installation sector, as hospitals around the world remain closed for non-critical medical procedures. In our electric vehicle business, demand is approaching pre-crisis levels as customers re-open their factories and consumer preference continues to shift towards electric vehicles. We continue to see resilient demand in our consumer electronics and data centre businesses.
Dividends - shareholders approved the 2p final dividend today. I agree with reader comments that paying divis at this time of crisis, is a very strong signal. That's another benefit of investing in companies with strong balance sheets - they can usually keep paying divis even in times of uncertainty.
My opinion - I'm tremendously impressed with how well Volex has performed. A few years ago it looked a bit of a mess. Not many turnaround situations do actually turnaround convincingly, but this one very definitely has done so, so kudos to management.
I watched an excellent documentary over the weekend, about the manufacturing process for London cabs, now made in a state of the art £500m factory in the midlands. The key electric/hybrid version was fascinating. It really struck me how complex all the electronics are, with lots of heavy-duty cabling to cope with the high power required to move a heavy vehicle. It only has a range of 80 miles on battery only, so they've bolted on a 1.5 litre petrol engine to produce extra electricity, which extends the range greatly, to about 380 miles from memory. Although the concept of a hybrid vehicle is somewhat baffling, since there's little cost or emissions benefit from lugging around all that extra weight, whether on battery or electric power.
Anyway, the point I'm making is that this documentary made me join up the dots with Volex - i.e. it could be on the cusp of a big increase in demand from electric vehicles, once they become more widespread. I imagine the medical devices softness would sort itself out in time. After all, given the critical importance of having decent quality wiring in electrical vehicles, I imagine manufacturers wouldn't necessarily risk putting in sub-standard wiring, as it could result in breakdowns, or even fires, if short circuits arise.
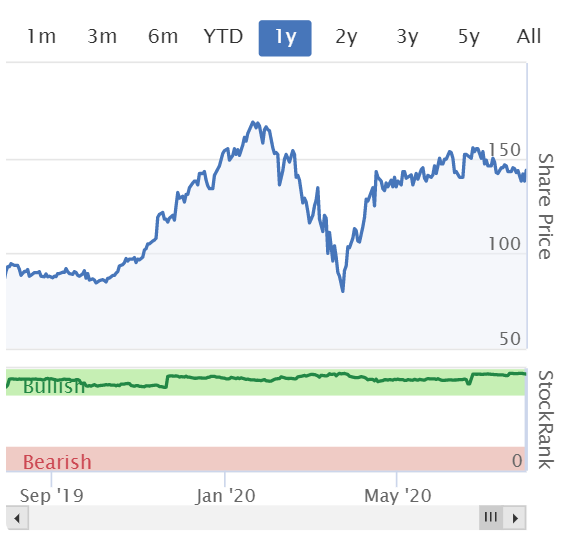
Overall then, I'm inching closer to buying some Volex shares, when I have some spare cash. I'm thinking in terms of maybe buying a small or medium-sized position, not going crazy with it.
.
.
Lastly, I'll do some quick reviews of micro caps. These are thinly traded, so I'm putting less focus on the tiddlers, unless there's something really special;
Airea (LON:AIEA)
27.5p - mkt cap c.£11m
Interims for H1, 6m to 30 June 2020. I've gone through the figures, here are my brief notes;
- Pre-lockdown sales were in line with LY
- Apr & May 2020 sales down 51% vs LY
- June much better, down 9% on LY
- 6 year CBILS loan of £2.75m drawn
- VAT deferred - but doesn't say how much, and I can't find it on the balance sheet. "Deferred tax" is usually other stuff, and there aren't proper notes to the balance sheet categories
- Hoarding cash, now has pile of £6.5m, or £3.7m if we offset the CBILS debt - looks fine, but bear in mind that cash will reduce as the business expands again, due to the build up of inventories & receivables, so I think this should be seen as a bit of a one-off, artificially high cash figure
- Pension deficit has risen from £3.6m to £4.9m - consuming £400k p.a. of cashflow, as deficit recovery payments
- Outlook - H2 should produce a "modest profit"
- No interim divis - makes sense
- Balance sheet - looks fine to me. Very healthy working capital position (i.e. net current assets). Also has a £3.6m investment property, which could be sold if they ever get into difficulties - always good to have some property down the back of the sofa. Overall, I don't have any concerns re solvency risk
My opinion - looks cheap, and fairly low risk recovery play. Lack of market liquidity could be frustrating. Not the sort of thing to trade, but I think it could be a reasonable long-term recovery share. I could see say 50% upside, if recovery continues, with a maybe 1-2 year view, so quite good possibly.
.
Belvoir (LON:BLV)
145p (up 11%) - mkt cap £53.8m
Thank you to readers who flagged up this positive trading update in the comments below.
I've had a look, and agree with you! The key bit says;
The Board is delighted to report that trading during the first half of 2020 has delivered continued growth due to the success of its strategy, despite the UK-wide lockdown.
Both revenue and operating profit is comfortably ahead of 2019 with net profit in line with management's pre-Covid expectations, as set at the start of the year.
Providing there's nothing unusual in the figures, then it strikes me as very impressive that the company is now saying profits are in line with pre-Covid expectations. The hit from lockdown saw a good recovery, due to pent-up demand once lockdown ended. Similar to what ScS was saying above, so this could develop into an interesting investment theme.
Nice to see it clearly disclose deferred VAT;
The Group has continued to generate cash from operations with net debt at 30 June 2020 standing at £5.7m (31 December 2019: £6.9m) having deployed £2.0m of cash in January to acquire the Lovelle network and deferred payment of £0.5m VAT until Q1 2021.
No divi, but hoping to reinstate. I'd prefer them to strengthen the balance sheet.
Nice outlook comments.
My opinion - looks good, although my balance sheet concerns still exist. Maybe a resilient business like this can operate OK with a weak balance sheet? So my concerns might be misplaced in this case?
I've run out of time for today, so will see you in the morning.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

78 comments
One thing to note with the Volex (LON:VLX) update is they say "Unaudited revenue for the three months ended June 2020 was $96 million, which was flat on the same period a year earlier" whereas at the time of their FY20 results they said revenue was up 4% to the four months ended May 2020. So either they didn't have a great June or they had a good Feb & March.
It's still a good performance given the turbulence, but this latest update points to revenues creeping lower at the moment.
I'm interested to hear the bull case. I'm currently sitting on the fence, waiting for more of a fall, as the weak like for like revenue growth makes me feel like the potential upside is limited.
Apologies if others have made the same suggestion, but using the mobile app on an Android (matching your phone) or Apple tablet might be the best of both worlds for Stockopedia on-the-go.
One of Paul's remarks has prompted a couple of questions from me on how Stocko presents earnings etc forecasts in the light of Covid:
1. Does the list of 'Analysts' include 'paid-for' research, eg from the likes of Edison, as well as independent houses? (I suspect some SmallCaps have only the paid-for option.)
2. I assume there's no way we can tell the effective date of analysts' forecasts included in the Consensus figures? With LargeCaps I'd guess most analysts will update their forecasts quite promptly after new info comes to light while for SmallCaps there may be quite a delay (couple of weeks?), depending how busy the research house is. So at any point in time, the consensus may represent a blend of updated and historic forecasts?
3. If a company itself withdraws guidance, as many have done in recent months, do analysts still review/update their forecasts or do they tend to leave them unchanged until the company gives some guidance? Or do some analysts also withdraw their earnings forecasts - in which case do they drop out of the Stocko consensus figure?
Apologies if these questions are too dumb!
Not dumb at all wilbraham, in fact it is very petinent at this time.
1. I don't know the answer to your question 1 , but I would have presumed that the consensus includes all available forecasts (paid and unpaid).
2. You can certainly see when forecasts change from the graphic on the StockReport.
But not (from stocko) which analyst changed their forecast when.
3. This one is very pertinent.
Some analysts might actively say that they have withdrawn their forecasts (I haven't actually seen this), but I suspect the way that Stocko (and all other sites) capture the data would not reflect that, as they just capture the latest forecast from the brokers in their sample. (Presumably with some form of date cutoff)
The forecasts I have shown above are for £WGB and basically you can see that neither broker updated their forecasts as the crisis developed (the April, May, June figures 8.8,8.6,8.8 I'm pretty sure must be just a statistical blip).
My characterisation of that is that the forecasts were obviously downgraded on lockdown, but the analysts had no idea how bad to make them, so they said nothing.
WGB's statement at the end of June gave more clarity and one of the brokers updated their forecast. Paul report that they were forecasting a loss
So the average now shown of 4.92p I presume to be made up of one unchanged forecast and one updated forecast.
This is quite important for two reasons -
1. The "concensus" make no senseus until the 2nd broker updates their view.
2. It looks like the forecasts were cut in July - which directly feeds through to the Momentum Rank. As per my characterisation above, I would argue that given that the most negative thing I think you could say about WGB's June statement is that it wasn't as bad as it could have been. So if the analysts had been brave enough to guess a number back in March then the June statement would have resulted in an upgrade.
(As an aside, WGB's more recent statement this week demonstrates that the Broker forecasting a significant loss was overly pessimistic, but the apparent "consensus" is still overstated as a result of the forecast that has not been updated.)
It's a bit of a minefield at the moment for the StockRanks - not only is the Momentum Rank hugely dependent on whether the post-covid forecasts have been produced; but even more so the QR & VR will be heavily skewed by whether or not a company has reported actually results that include part or all of the lockdown period.
Volex looks like it Posted Ok Paul before your laptop went wonky
Oh brilliant, so it did, thanks for pointing it out!
I'll remove my last comment about it disappearing!
Just published Ultra Electronics Holdings (LON:ULE) H1 20 analyst presentation from this morning. Ultra Electronics Holdings (LON:ULE) supply the defence and aerospace, security & cyber, transport & energy markets. They are undergoing a transformation with new management. They have a strong order book, limited CV19 impact, and are reinstating dividend in September. Major markets are solid, although commercial aviation challenged, but even so they have good order visibility going forward.
Here's the video, or podcast here.
Also, a reminder, Ig Design (LON:IGR) management will give a FY20 results webinar tomorrow 31.7.20 at 12.30, do join us. Register here.
3 quick comments on Scs (LON:SCS) (I do not hold).
1 - Given the lead times I understand why the focus in today's update is on order intake, but I thought it might be worth highlighting that there will be a 38% drop in H2 revenues vs last year.
2 - I originally thought that the company needed £285m of revenue to break-even this year, but in retrospect this value might be lower given lower marketing and performance pay. Fingers crossed for all holders.
3 - At the end of May 2020, the company had £16m of actual cash ie excluding customer deposits and the RCF. Crucially all suppliers had been paid at this point, so this £16m is important in the sense that under normal trading conditions we can never work it out.
This figure will no doubt be lower now, but if you want to work out the company's true cash position this is probably a good starting point.
For reference:
Cracking analysis, thanks! I didn't have time to work out the figures myself, so it's really useful when readers post more detailed analysis like this (I'm assuming your figures are correct, because you sound like you know what you're doing!) ;-)
Scs (LON:SCS)
Hi Paul
The company's suppliers are paid by the end of the month following delivery.
Given that deliveries were paused by March 24th, I think it's fair to assume that there were no supplier payments due by the end of May.
So I would hope that the £16m "true" cash position I noted at the end of May is accurate.
---
All the figures in my post, including the £16m, are pulled from the published company reports so one would hope they are correct.
Fingers crossed I know what I'm doing :)
Thanks for the marathon effort today by the way.
Cheers
A
Just musing on a bad day for the market - FTSE down below 6000 - and a scratchy month up / down in a range but overall losing 3%. I felt quite good about things at the beginning of the month. Lockdown eased, travel abroad on the cards, a nice whiff of optimism and confidence appeared to come back. But the government has played a shocker in July. lift the lockdown / impose local lockdowns, no need for masks / mandatory masks, 'air bridges' / quarantines etc.. . It is hardly creating an environment where things can get back to normal. And the signs are good - 'cases' may be up but that is largely to do with more testing - hospitalisations / ICU admissions (only 80 at present) / deaths well down. It seems to me that people like Matt Hancock have no regard to the economy and especially the small business sector when introducing these contradictory and unnecessary regulations.
With the end of furlough in sight government must now prioritise the economy. Otherwise I really worry where the market is headed to in August and September.
Well said above!
I made a cautious 1% using £SUK2 as taught on Stockopedia in a recent article. Had I kept my bottle this 2X short moved by more than 5% today.
Using this Short ETF is quite tricky with the leverage. If it moves against you, you either need to Stop out or else hang on for FTSE100 to deteriorate further.
Anyway, that's my gym membership paid for plus a bike service, thank you.
Where's The FTSE100 going next now its fallen to 5989?
The Government is creating a drama out of this crisis. Business does not have the assurance that this will not happen again.
Wonder if anyone has any thoughts on Gvc Holdings (LON:GVC)
They announced a tieup with MGM over in america that's doing well. But since headlines about a HMRC investigation it has dropped from 900+ down to 672 (currently).
Think theres an opportunity here?
"All those millions of people locked down this year, would be more likely to replace worn out sofas, carpets, etc, than before."
Paul, that's a worthy comment, I'm thinking of all those sofas suffering crushed springs!
Silver
Paul, Can you explain your comment (Norcross): "It's easy to report lower net debt, if you're not paying VAT or payroll taxes temporarily." Cash would be higher by the amount of the unpaid VAT, but that VAT would increase liabilities by the same amount so net debt would be unchanged, surely. Or have I misunderstood something? Thanks.
cic, you're correct that the deferred payments would be shown a liabilities but as debt, which is generally defined I think as outstanding balances that incur interest. (Including under IFRS16 the infered interest on rental payments).
Hi CIC,
Paul says in his comments - "Another glaring omission, is that we're not given any figures on stretched creditors."
So the VAT deferred may spike up creditors and the corresponding amount of cash (that should have been paid and of which will eventually be paid) as output VAT is still in the bank. This puffs up the cash in the bank.
cic
Cash would be higher by the amount of the unpaid VAT, but that VAT would increase liabilities by the same amount so net debt would be unchanged, surely. Or have I misunderstood something? Thanks.
You have missed the fact that most amounts owed out in taxes/trade payables/deferred consideration etc are excluded from the net debt calculations as they arent a "debt" when we are talking about "net debt". Historically only the liabilities that incurred interest tended to be included here when looking in very simplistic terms - although one should never presume anything is true when it comes to accounting standards as there tends to be an exception to any rule.
Note this fact is very important when it comes to looking at a companies solvency , last time scs went tinto insolvency they had very little debt and cash in the bank - it was the trade payables liability that brought the company down not an item that was ever flagged up as being included in the net debt.
Getting back to Norcros (LON:NXR)
at 31/3/2020 per note 7 they had
+47.2 mill net cash and current borrowings
-83 mill non current borrowings
leaving net debt of £36.4 mill
going to balance sheet we have
cash of £47.3 mill
current liabilities borrowings £0.1 mill
Non curent liabilities borrowings £83.6 mill
this matches the net debt above
they make the follwing note ref net debt
Net debt is the net of cash, capitalised costs of raising finance and total borrowings. IFRS16 lease commitments are not included in line with our banking covenants.
so although i may have expected lease liabilities to be include in debt they are not !
getting back to current liabilities and long term liabilities
in addition to the above items which are included in net debt we have the following items which are not debt debts they are non debt debts if you see what i mean.
trade and other payables £73 million
lease liabilities £25 mill
pension scheme liabilities £49 mill
tax liabilities 1 mill
provisions 3.2 mill
None of the directly above are included in debt.
In summary net debttaken in isolation normally tells you nothing useful about the solvency of a company.
Hi Paul,
Thanks for all your work.
Just wanted to say it's great that mentioned/considered in your Scs (LON:SCS) article about the "lighter line above for colour-challenged readers".
Although it doesnt affect me as i'm red-green colour-deficient it's great that you would think of it.
So many charts etc are red and green (which is the most common colour-deficiency) and it makes things so much more difficult/frustrating especially if you are unable to change them.
Well done!
£SCS. Another super write up Paul, thanks. I do wonder if we're not seeing something that we saw in part in the last recovery. First people stop spending because of the shock, then they get bored and open the purse.
This time out there are more limited options for that purse.
Out: Fancy holidays abroad.
In: Home improvements or even a move. Holidays at home. Cafes, Eating.
?: That new car
Anecdotally I was talking to a builder mate at a BBQ and he was saying that everyone locally is booked out for months, only issue was materials. Plaster and Paying blocks (from India!!).
Personally, two big holidays abroad gone - kitchen completely refurbished. Old Jag (4.0 XJ8) totally new suspension.
Went for a bike ride yesterday in the Bourne Valley (fab) and stopped at a posh/bistro pub. Asked how it was going and they said they were flying, bookings way up and takeaway showing no signs of abating.
Think the likes of SCS could do very well.
Norcros (LON:NXR)
shanklin100
If one cannot trust a management team to be open and honest then, IMHO, better not to invest in them as you never know what else they might already be hiding or will choose to hide in the future.
I would agree with that statement however i would say though, that as a long time holder of Norcross i have always found them to be a very safe pair of hands with regard to the integrity of the information they provide. Many companies are guilty of perhaps not providing the detail we would perhaps like at all times - i would be wary about stretching things too far in that regard. In summary something can perhaps be misleading at times without there being malice behind the intent that is often present with the "dodgy tell you a story management that presumably we all so hate and try to avoid". Norcross have no real need to do anything other than present a summary of the situation as it is so if the summary is misleading i for one would say that for this company that i wouldnt presume its done without any intent to mislead. They will perhaps be among the majority of companies that will probably expect it to be a "given" that cashflow will be managed in a reasonable manner at present times and may take the attitude that they don't need to keep repeating this fact perhaps?
Note todays update was simply an AGM update - the company only last month gave a detailed update ref cashflow confirming what Paul suspected is true ref hoarding the cash - so i wouldnt exactly say they have been remiss i their duties in spelling this situation out.
Per the company last month.
Cash preservation and cost reduction
Once the severity of the pandemic in our major markets was apparent, we took immediate action across the business to preserve cashflow and reduce costs. We have taken advantage of the Government furlough schemes, tax payment deferrals and rent deferrals totalling over £10m in the first quarter of this year. Additionally, we have withdrawn the final year-end dividend and have ceased all non-essential capital expenditure. At the same time, we have been focussed on minimising the rate of cash burn by reducing costs and eliminating any discretionary expenditure. We have also frozen all pay throughout the Group with reviews deferred and secured voluntary reductions of 20% in the fees or salaries of the plc board members, Group leadership and senior management teams for the first quarter to end June 2020. The result of these measures is that the current cash burn in our operating scenario is approximately £5m per month compared to the unmitigated initial estimate of broadly double this level.
Hi rmillaree
My comment was primarily directed at Paul's "partially misleading" comment rather than the Norcros (LON:NXR) TS, as Norcros (LON:NXR) seem to have been going absolutely nowhere for many years, so I did not read the RNS in great detail.
The more general point I was making is that management honesty is just something I need in the stocks I hold for me to get a decent night's sleep.
For example, many posters view Mpac (LON:MPAC) as a company with excellent prospects and available at a particularly decent price. I would not necessarily disagree but sold my holding after finding out that they failed to mention 25% H1 YoY sales drop in their recent Operational Update... ...albeit it was guestimated at in a FinnCap broker note and AIUI mentioned in a management interview.
In Many ways, I would like to buy back in to Mpac (LON:MPAC) but would prefer they had not blotted their copybook in this way.
Obviously all IMHO.
Wish every share I bought goes "...absolutely nowhere for many years..." like Norcros (LON:NXR) which roughly doubled in 3 years! It would help offset some of those that genuinely do go nowhere (or worse).
Fair comment, I hadn't realise it had almost reached £3 prior to Covid-19.
Hi Paul, any thoughts on S4 Capital (LON:SFOR) Sir Martin Sorrell's new digital ad marketing services co. Latest acquisition news came out at 16.30 yesterday. Not cheap but an excellent way to play AMZN, GOOG, FB etc.
Hi Terry,
Amusing name by the way! Are you Terry, or is that someone you don't like?!
As regards S4 Capital (LON:SFOR) - I've been meaning to look at that one again, but haven't got round to it. It does look quite interesting, but my main concern is that the valuation could be elevated due to Sir Martin's involvement? Also I have some concerns about the way it presents numbers, which seem to flatter profitability. Also, is Sir Martin an old man in a hurry, desperate to have another big success, post his WPP success? If so, he could be over-paying for acquisitions, possibly?
So I do have some concerns, but on the other hand, Sir Martin's CV is spectacular! Mind you, sometimes a brilliant CV can be because someone had a brilliant team behind them, and was just the front man (possibly the case with Woodford?). So when they move on to pastures new, it's surprising how often things are messed up. Or sometimes brilliant people are just lucky, in being at the right place, at the right time. Often things are on a bell curve, so some people just get lucky, irrespective of ability.
Regards, Paul.
Thanks for the speedy response Paul. You raise some valid points. I personally think that SMS is on a mission here. Unceremoniously dumped from the global giant he created, he's out for revenge, and won't let up until SFOR is bigger than WPP.
As you point out, he's no spring chicken so he's wasting no time buying up the best companies out there. (nobody knows the ad tech sector better than SMS).
Finally I don't think they overpay because they never really do 'acquisitions' as such, they always merge into a bigger and bigger global player.
I just can't see their expansion slowing - unless we all stop using the internet!
Slightly off topic but I couldn't pass without comment:
"sometimes a brilliant CV can be because someone had a brilliant team behind them, and was just the front man (possibly the case with Woodford?)"
I probably concur, I was talking to an FA friend after Woodford's branch out on his own, I'd mentioned I'd bought into his (Woodford's) income fund and it was doing ok, he passed comment (possibly tinged with jealousy of course) that he had a good team behind him at Invesco who were making the calls. I never forgot that comment and when his funds started to go awry I was out like a shot (profitably thankfully)
I've noticed that a couple of his investments are starting to recover of late (Eve Sleep, and another I can't recall), so maybe he just got unlucky with timing, although the in depth presentation by Ed on here last year I found immensely interesting (in a nutshell he sold his winners to top up on illiquid losers as funds were withdrawn)
There are a couple of other things to remember about Woodford. His Investment Trust also did badly and so that was nothing to do with having to sell the liquid winners to fund redemptions as was the case with the unit trust. He also took very large stakes in many of these small companies so he couldn’t realise those gains without hammering the share price even he wanted to. Perhaps this was because he was running too much money.
As regards the team behind him at Invesco, his protege there, Mark Barnett, has also come to grief so it looks to like the team there was not somehow the cause of the previous success rather than Woodford. I think that it’s probably more the case of Woodford and that team getting a few major calls right in the previous years but then having too much faith that their approach would work under all market conditions, rather than the team there continuing to be successful after the front guy has moved on.
So, a number of factors/mistakes but leaving a team that continued to be highly successful without him doesn’t look like one of them because they weren’t as far as I can see.
On Woodford, if anyone is interested - excellent podcast with Mark Slater - he briefly mentions Woodford going awry + loads more
https://citywire.co.uk/funds-insider/news/mark-slater-real-market-panic-was-all-too-brief-in-this-crisis/a1384525
Hi all. Sorry if I’m missing something obvious, but is there a stockopedia iPhone app?? I cannot seem to locate it in the AppStore.
Not sure about an App, but I simply use my browser on my phone to go to the usual website and it is configured for phones as Paul says - easy to read and navigate. A Joy.
Aye, same here. it is well configured for phones. But then read Paul's message above mentioning about an app and thought... oh!
I found a Stockopedia app on the PlayStore, for google android phones, which is what I use (because it better integrates with GMail, Google Calendar, and I don't have to remember passwords, as they're stored within Chrome).
So I'm not sure about iPhones. Maybe one of the tech team could reply to this thread if they see this?
As KevinS1 says, the other option is just to view Stockopedia on a web browser in your phone, as it seems well set up for that too.
You can add the app to your iPhone by following the steps below. Please note that you may need to scroll right instead of down to find 'Add to Home Screen' depending on your model.
Hi Oliver
I have watched the video multiple times and have no idea what you are doing. Please could you break it down into simple instructions.
I have gone onto Stockopedia through Safari and logged in but nothing like your video is coming up.
Thank you, Martin
Hi Martin,
Once you're on the Stocko page in Safari, if you scroll up the page it will make some icons appear at the bottom of the iphone. Select the middle one that looks like a box with an arrow pointing up, tap on it. After that a window pops up, scroll down about two thirds and you will see "Add to Home Screen", tap that.
After that, tap "Add" in the upper right hand corner, and Stocko will appear on your iphone home screen.
Cheers
Hi TLK
Had no idea what I was meant to be doing to begin with, but, all good now.
Thank you and Kind Regards, Martin
thanks. Very useful
I can't find the App in the Google Play store on the web or on my mobile.
https://play.google.com/store/search?q=Stockopedia&c=apps
I'm beginning to think Paul has installed a different app...
It doesn't seem to come up in the search. If you log on to the site via Chrome on your mobile there will be an option to add the app. At least there was for me.
if anyone from stocko could confirm if there is an actual app for iPhone that would be amazing. I didn’t think there was one.
I'm not from Stocko but can confirm that I am logged into the Stockopedia app on my iPhone...
Thanks, did you download it from the AppStore as it’s not come up in my search. Pretty sure I am missing something here though.
There is no phone app but you can create a shortcut on your home screen to the mobile version of the website.
Norcros (LON:NXR) "My opinion - I think this RNS is partially misleading,"
If one cannot trust a management team to be open and honest then, IMHO, better not to invest in them as you never know what else they might already be hiding or will choose to hide in the future.
Paul
Maybe I should start a consultancy business, to help improve the quality of trading updates? It's badly needed!
Yes please the quality of most company announcements nowadays is ridiculous - its often spin and kpi's that only last as long as they show the business in a good light and the dreaded in line with expectations without telling us what the expectations are.
Ref Norcros (LON:NXR) and the lack of the lfl figures - i will probably forgive the presumably stressed finance department here - the table pretty much told me what i wanted to know - note the last acquistition completed on 1st April last year (would i fool you folks?) so the numbers should be reasonably clean in that regard - ie no reason to expect lfl figures are any worse than actuals.
Ref loss in April with sales down 60%+ in that earlier period i think the loss was to be expected and not really of any relevance with the healthy later bounceback in sales numbers.
Hopefully the surge in shareprice will be short lived as i will probably top up around these levels if i get a chance - obviously there is the danger here that the stong bounceback may have been partly aided by pent up demand that may later subside - based on the tone of the news today though it seemed more along the getting back to normal - i think if they had epected material spike back down in numbers they would have probably have added some extra caution - then again they may simply not know whats going to happen in that regard.
Thanks for clarifying re Norcros LFL/acquisitions, saved me a job! :-)
Update looks good. Perhaps worth a brief comment Paul but only if you have the time?
Onthemarket (LON:OTMP)
This section of their AGM statement today speaks for itself especially so the first and last paragraphs, and share is up 10% on a generally down day.
Our financial year to 31 January 2020 was a year of strong operational performance with financial momentum building throughout the second half. It is particularly pleasing to see the portal delivering real value to its estate agent and new homes customers, with record enquiries as millions of engaged consumers visit the website each week.
"Despite the UK lockdown as a result of COVID-19, it is pleasing to see operational progress continue. At 30 June 2020, total advertisers* had grown to almost 14,000. Throughout June, the portal generated more than 1.8 million leads - an average of 134 per advertiser, an increase of 6.3% from our 126 leads per advertiser during January and 40% on the FY20 average leads per advertiser of 96. This was despite the curtailment of discretionary marketing spend following the onset of the COVID-19 crisis.
"Throughout the COVID-19 pandemic we have focussed on careful management of cash. At the end of June, our net cash balance stood at GBP9.4 million (an increase of GBP0.6m compared to the end of May), and, excluding GBP2.3 million of deferred creditor payments on both dates, we had no borrowings.
"Following the release of pent-up consumer demand as the market reopened, buoyed further by the Chancellor's stamp duty holiday, agents are seeing strong levels of activity. The COVID-19 crisis has been a catalyst for many agents to review their portal choices and examine the value delivered. We believe there is significant potential for market share gains and we will look to capitalise on this opportunity through our strong portal offering, our approach of agent alignment through ownership in OnTheMarket and our commitment to sustainably low listing fees.”
Onthemarket (LON:OTMP) really good trading update. 600 new full paying agents since the new contract off equating to about £2mill revenue and 1619 new full paying over the last year which is up 42% and additional agents on part paying contracts.
They are really starting to gain traction.
Today's update from Minds Machines (LON:MMX) seems to show that their revised strategy is working. Domain registrars are the rent-takers of cyberspace with very sticky revenue and the ability to increase rents ahad of inflation. I hold as it looks a decent longer term investment and it feels better to pay rental for my own domains with some of a rent collector's profits!
Re BigDish (LON:DISH)
Encouraging news I suppose in that if they hadn’t been able to sign up a good number of restaurants in the current climate (given that restaurants are desperate and given that the product is free) it really would be the death knell.
I expect that the market reaction may well be positive as many PIs may not be too worried about whether this can be turned into revenue and profits at this stage. However, I am, so no position for me.
The financial benefit of their different activities is invariably missing in their announcements. BigDish seems to have a simplistic "more is better" philosophy, spiced with story-telling.
Severfield (LON:SFR)
After apparently passing on the dividend at the preliminary results the company said today:-
"As a result of the Group's strong balance sheet and cash position, the board is recommending a final dividend for the year ended 31 March 2020 of 1.8p per share, making a total for the year of 2.9p per share (2019: 2.8p per share). "
Cash speaks louder than words and the unexpected income is nice.
Yes cash is the number one thing to look at in this climate. Forget all the corona adjusted EBIDTA nonsense, forget adjusted profit, forget trading profit even, just show us the cash. The more companies obscure that position the less likely I am to get involved.
Lack of cash is what will drive the impending wave of bankruptcies.
Norcros (LON:NXR) and SCS (LON:SCS), both of which I hold, reporting good post lockdown trading, presumably due to pent up demand. Being stuck at home looking at that grotty old bathroom and sofa has clearly had an effect. Hopefully it will be a similar story for wallpaper and another of my holdings, Walker Greenbank (LON:WGB).
My morning smallcap tweet:
HML Holdings (LON:HMLH) Diurnal (LON:DNL) BigDish (LON:DISH) Omega Diagnostics (LON:ODX) Sigmaroc (LON:SRC) Intercede (LON:IGP) Minds Machines (LON:MMX) Sopheon (LON:SPE) Volex (LON:VLX) Tanfield (LON:TAN) Onthemarket (LON:OTMP) Yu (LON:YU.) Biome Technologies (LON:BIOM) Norcros (LON:NXR) SCS (LON:SCS) Fireangel Safety Technology (LON:FA.) Belvoir (LON:BLV), Stobart (LON:STOB), Smart Metering Systems (LON:SMS)
HML Holdings (HMLH) rec offer 37.5p, a 27% premium for this mediocre property services co.
Diurnal (DNL) guides FY(June) rev for Alkindi up 130%. Is this all of rev?
BigDish (DISH) 1250 restaurants have joined, including prev announced Pizza Hut. BigDish-to-GO will launch in beta towards the end of next week. Recall that DISH currently not charging.
Omega Diagnostics (ODX) UK Rapid Test Consortium, of which Omega is a partner, has had the covid antibody test approved for professional use.
SigmaRoc (SRC) guides H1(June) rev up 83%, U/L EBITDA up 91%, ahead of mgmt expectations. No FY guidance. I hold.
Intercede (IGP) wins US Homeland Security contract. No numbers. The contract was included in mgmt expectations for this FY.
Minds + Machines (MMX) H1 registrations up 31%, automated online channel billings up 20% reflecting move from one-off brokered billings. "As a traditionally H2 weighted business, we are further encouraged by the outlook for the full-year as new partner initiatives delayed in Q2 due to COVID-19, are now set to commence in H2."
Sopheon (SPE) partnering with snack giant Mondelēz to transform its innovation and commercialization [sic] processes and portfolios. No numbers.
Volex (VLX) 'very pleased' to see flat rev in last 3 months. Still weakness primarily in the medical installation sector but demand is approaching pre-crisis levels in electric vehicles.
Tanfield (TAN) gets second loan note of £1m to fund legal action and keep the lights on.
OnTheMarket (OTMP) AGM stmt. Total advertisers now nearly 14k. Agents are seeing strong levels of activity.
Yu (YU.) guides H1(June) rev down 20%. Average monthly sales bookings £6.2m (£3.2m). U/L EBITDA ahead of expectations set by management at the start of the year but "adjusted EBITDA loss c. £2m due to covid. Uh? So one made-up BS profit good, another bad.
Biome Technologies (BIOM) guides H1(June) rev £2.6m down 28%, including grants. Blames over-capacity in the fibre optic market and covid. Bioplastics rev up 53% to £2.2m. Reduces expectations for Stanelco RF division in H2.
Norcros (NXR) last 16 weeks rev down 35%. July rev up 8%. I hold.
ScS (SCS) guides FY(July) rev down 20%. Order intake down 6%. Post-lockdown rev up 92%. "Whilst it is too early to provide clarity on the outlook for the weeks and months ahead, the Group is encouraged." I hold.
FireAngel SafetyTech (FA.) guides H1(June) rev down 20% and U/L op loss £2.7m (£1.7m). July sales expected to be flat YoY.
Belvoir (BLV) guides H1 rev 'comfortably ahead' YoY and net profit in line with pre-covid exp. Confident of meeting FY pre-Covid expectations.
In line: Stobart (LON:STOB) Smart Metering Systems (LON:SMS)
Norcros (LON:NXR)
Very pleasing trading update - small underlying profit qe June - despite first nine weeks being down 60% on last year - July sales to date at the same level as last year. The shareprice remains depressed. Slightly slower bounce back in South Africa than uk. So hopefully firmly back into decent profit levels going forward.
BP shares...any thoughts please?
you’re more likely to get a response from Paul, if you keep it to small cap (exceptionally some larger retail), not miners or oil and gas, a company issuing an rns today and gave your own thoughts on its performance.
Oil and traditional value are likely to do well coming out of a crisis and growth in a bull market. Royal Dutch Shell (LON:RDSB) showed today it is far more resilient than people thought.
Morning Paul - any chance of adding Harworth (LON:HWG) to this morning's list ?
Also, looking forward to your views on Scs (LON:SCS) . I doubled up in early April in the belief that people's sofas would become a thing of "hate" after lockdown and that there would be pent-up demand. Encouraging words so far from the co. supporting that view.
Morning LumpedOn,
If I have any spare time, I'll try to look at £HWG . Although it always helps if reader requests are accompanied with a few bullet points on why you think it's interesting!
I've just started work on £ScS , so that section should be up by about 10am. Each section takes me about an hour to write, as I have to look up previous information, check broker notes, etc, to ensure I can put everything into context properly.
Regards, Paul.
Understood, and thanks for the feedback.
Harworth (LON:HWG) is a land and property regeneration business focussed on the Midlands and North of England, and is of interest to me as I believe the company will benefit from both former (pre-pandemic) and current Govt policy to "level up" and "build build build" as a way of driving up employment and opportunity in the region.
I feel that given the large number of constituency seats won in the Midlands & North in December 19, and the apparent continued desire to demonstrate delivery of election promises, that any incentives re. planning permissions, subsidies, inward investment etc. can only benefit Harworth (LON:HWG) .
The trading statement released this morning appears (to me) to show good progress in both rent collections and realised asset values, which coupled with banking facilities and cost controls seems (to me) to have strengthened the balance sheet and prepared the company well for opportunities in this space.
In the post-election market lift, the share price reached £1.50ish, dropping to a pandemic impacted low around 88p. I started buying in early March at pre-election levels, too early as it turns out, when I and others believed the worst falls were over. After today's update I am now weighing up adding more, and would be interested in your views on this one's financial position as reported,
Thanks.
Hi,
Morning Paul,
It would be great to hear your thoughts on Belvoir (LON:BLV) if possible.
They provided an interesting update this morning - "Both revenue and operating profit is comfortably ahead of 2019 with net profit in line with management's pre-Covid expectations, as set at the start of the year."
In addition, the following statement could be quite valuable as it probably applies to similar companies in the sector - "Since the restrictions on the housing sector were lifted in mid-May, there has been a surge of activity due to pent-up demand. This has seen Group network revenue in June up 12% compared with June 2019 with our lettings business up 17% and ahead of pre-Covid levels, and has resulted in June being a record-breaking month for our Newton Fallowell estate agency network in terms of instructions and sales, and for our financial services division in terms of written income."
Cheers
Belvoir (LON:BLV) - it's on my reserve list, if I have any spare time after doing the other companies.
I'm tending to leave the smallest micro caps to the end now, as they're often very difficult to trade, so me saying to 10,000 readers that something tiny looks cheap, would probably just result in a lot of frustration, and maybe spike the price up, which is not helpful to anyone.
As a holder I'm really pleased with the Belvoir (LON:BLV) update so topped up this morning. It's much better than I expected especially given they had reduced fees for their franchisees during the lockdown. All the more incredible that revenue is ahead of last year given the economic backdrop and the housing sector restrictions until mid-May. I'm especially pleased the financial services commission has risen in H1 because that's what is particularly driving growth and profits with this share.
Finncap have updated their free broker note today with an expected EPS this year of 14.7p - note this is still slightly lower than the 15.5p I had noted down as brokers pencilling in at the start of the year.
Despite the debt which has come down slightly, with the growth potential from financial services (albeit partly acquisition driven) I personally think a p/e of 13 isn't unreasonable here so a short-term share price of 190p seems achieveable with further growth years after.
If I am disappointed by anything today it's the plan to resume dividends so quickly, as I'd personally prefer them to reduce debt a bit more or use the funding to pickup some lettings agents who might be prepared to be sold cheaply post-COVID.
Despite the uncertain outlook, I'm feeling more confident about sales and lettings agents given the stamp duty holiday. Belvoir (LON:BLV) has taken the lettings fees legislation in its stride too. DYOR.
Nice one Patrick, great to hear your views :)
Hi, technical question to stir comments.
Statistically, how many days does it usually take for the 50ma and 200ma to intercept? How long does a golden cross or death cross usually last for?
Dan
Statistically, how many days does it usually take for the 50ma and 200ma to intercept?
Why would they intercept except for a short-term (and possibly one-off and random) fluctuation if the company is growing steadily or declining steadily?
If your question is about the "usual" time it takes for reversion to the mean, how will you calculate it when some values are infinite?
And how would the answer be useful in making trading decisions?
There's a Stockopedia ebook on the typical share price behavious following a profit warning here that you may find relevant.
Gosh, you weren't fibbing when you said you were a Data Scientist!
The 50MA is approximately the smoothed price 25 days ago and the 200MA is approximately the smoothed price 100 days ago.
So the 50MA will cross the 200MA if the price 25 days ago is the same as the price 100 days ago (after a bit of smoothing).
So your question is basically: how often is the price 25 days ago the same as the price 100 days ago - or equivalently how often is the price today the same as 75 days ago?
Now of course if the price is rising continuously apart from a few ripples (or falling continuously) then this does not happen. So the event only occurs after the price has changed direction. And with a bit of hand-waving the change of direction occurs somewhere near the middle, or about 75/2 = 37 days between the two points where it is the same.
So a golden cross indicates that the price changed direction (after smoothing) from falling to rising about 25+37 = 62 days ago (roughly 3 months) and a death cross indicates that the price changed direction (after smoothing) from rising to falling about 62 days ago.
But how often does a stock change direction? That is an interesting question. A stock with volatility=0 would never change direction. So clearly it increases with volatility. But what is the formula? Volatility is "noise" and I think there is an argument that the number of crossings depends on volatility but ignores any underlying trend ("drift"), with more crossings for stocks with higher volatility.
Bigdish (LON:DISH) big director sale notified yesterday, then operational update today. Interesting timing but no idea which way the price is going to go. Mitchells & Butlers (LON:MAB) is a big player so there is a lot of food for thought in this update.
The Chairman sold £8k worth of DISH shares, under a salary sacrifice scheme. Not helpful, but not significant £ either.
Operational update today sounds very encouraging to me, signing up some big names like Mitchell & Butlers, and also Patisserie Valerie, to use its online ordering/discounting app. Takeaway app also going live, in beta.
The company is pre-revenue, but a very interesting concept, and could become valuable once it achieves scale.
Disclosure: I'm long. Has to be seen as highly speculative, and needs to raise more funding later this year, which I think is likely to come from a strategic investor, not via a placing, probably.
Thanks Paul, yeah worth clarifying its 8k, not a huge amount in the grand scheme of things and this is a highly speculative volatile share. I see this as a fun concept play that could easily go the way of the junk pile, however I am a bit more confident of its longer term potential.
I’ve not come across DISH before, looks interesting but not one for widows and orphans. my main concern is lack of moat unless I’m missing something.