Small Cap Value Report (Thur 28 Sep 2017) - CMCX, HVN, MOSB

Good morning!
CMC Markets (LON:CMCX)
- Share price: 163.75p (+6%)
- No. of shares: 288 million
- Market cap: £472 million
This stock is of particular interest to me because I follow the sector, and currently have a long position in IG Group (LON:IGG).
This sounds good:
Profitability in H1 2018 is significantly higher than the same period in 2017 with both net operating income and revenue per client higher (and marginally higher than H2 2017), driven by increased client volumes.
Interestingly, the statement says there has been a small decline in active clients and that therefore, the improved financial performance helps to prove that CMC is focusing on higher-value, experienced clients.
This would be essentially the same as the IG strategy for the past several years. IG has had no interest in increasing active clients in the UK, instead only wanting to find and keep the most profitable ones.
It was a sound strategy but then it became very relevant when the FSA last December threatened to put leverage caps on retail traders in leveraged products. Along with other regulations, these rules would have had a particular focus on restricting how these firms are allowed to cater to inexperienced clients.
The regulatory threat smashed the share prices of all the stocks in the sector, although they have been recovering since then. CMC is up more than 50% from the low of 95p.
The threat hasn't gone away, but the FSA is certainly taking its time to figure out what to do next. It received more than 2,500 submissions in relation to the proposals, and has doubtless been wading through them.
On this subject, CMC says:
Regulation remains a key focus for the firm, and despite profitability in H1 2018 being significantly higher than the same period in 2017, the firm remains cautious about the future outlook given the ongoing regulatory uncertainty and the impact, if any, potential changes could have on Group performance.
I'm happy continuing to hold IG, which has the best international diversification and which I think would experience a strong boost to its competitive position in the UK from the new rules. I'm not sure if CMC would experience any competitive boost.
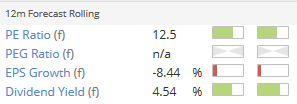
But CMC shares remain pretty decent value, still on a discount to compensate for this issue:
Harvey Nash (LON:HVN)
- Share price: 87.75p (-0.4%)
- No. of shares: 73.5 million
- Market cap: £64 million
After a lacklustre operating profit result for the previous financial year, these interim results are an opportunity for Harvey Nash to show it's back on the front foot.
It's a tech recruiter and provider of outsourced services, and its shares tend to trade on a discount against its peers. The PE multiple is currently a mere 7x.
A few of the H1 highlights:
- Revenue and gross profit up 12.6% and 2.0% respectively
- Profit before tax before non-recurring items up 4.4%
- Interim dividend of 1.643p per share, up 5.0%
Scrolling further down the statement, the constant currency performance is again a bit softer versus the prior year:
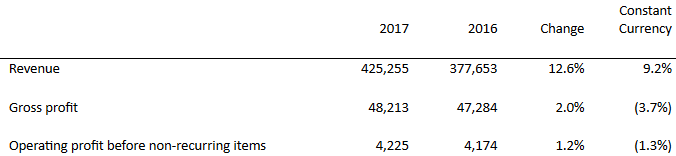
Even though net income increased, arguably the operating profit before non-recurring items, at constant currency, is the most important measurement of group performance. And on that front, it recorded a 1.3% decline.
The reduction in gross profit at constant FX is explained as follows:
This was mainly due to changes in revenue mix with the strongest growth in profitable but lower-margin managed services, coupled with a slowdown in permanent hiring in the UK during the election period.
The financial performance as a whole is becoming substantially lower-margin.
On the positive side, Harvey Nash is implementing a cost-saving transformation programme, has moved to AIM where costs are lower, and has made a couple of acquisitions which sound interesting.
Net debt might be worth keeping an eye on, as it jumped up to £10 million by the end of the period and then a £6m cash acquisition was made.
My opinion
Harvey Nash says that it grew market share in the UK & Ireland region, which accounted for 38% of its net fee income.
The results are probably quite reasonable then, in the sense that Harvey Nash grew market share in the more difficult region, and did fine in Mainland Europe where conditions are presumably easier.
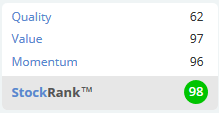
It offers a 5% dividend yield and is probably much safer than the typical AIM stock. And yes, the StockRank is 98.
Moss Bros (LON:MOSB)
- Share price: 97.5p (-2.5%)
- No. of shares: 100.8 million
- Market cap: £98 million
Trading at this suit retailer is in line with the Board's expectations.
I've selected these from the highlights as the most important:
- Total Group revenue, excluding VAT, was up 4.3% on the previous year to £66.6m.
- Group like-for-like* sales increased 2.8%
- Like-for-like* retail sales, including e-commerce were up 5.1%
- Like for like* hire sales, which represent 12.8% of total sales in the half on a cash taken basis were -8.4% down.
The problem area is clearly suit hire. Under current trading, this trend has persisted in the first 8 weeks of H2, although not quite so poor: minus 4.7% (again on a "cash taken" basis).
Reading through the statement, the company says that customers are choosing to buy rather than hire. So in other words, if hire sales hadn't fallen, then retail sales would have fallen instead.
Our store teams are increasingly focussed on offering solutions to customers for whatever their occasion or need, whether they choose to buy, hire or 'Tailor Me'. Whilst we cannot know for sure the original intention of customers coming to our stores, more customers are ultimately choosing to buy rather than hire their suits. This is in part reflected in the reduction in hire sales on a like-for-like* basis versus the previous year.
It's a difficult environment:
We remain acutely aware that market conditions remain tough, with a highly competitive retail landscape set to continue alongside an unpredictable economic back-drop. There are significant cost headwinds, driven by National Living Wage, the Apprenticeship Levy and weaker sterling.
Paul has pointed out before that like-for-like sales at Moss include refitted stores, making the comparison somewhat debatable.
Last year, Moss refitted 11 stores and opened 7 new ones. In H1, it refitted 4 stores, and opened 4 new ones. The total number of stores is 129, and at least the 15 refitted ones will be included in the like-for-like calculation. I still think the company's reported like-for-likes are important number, but it's worth bearing this in mind. The numbers would have been worse without the 15 refitted stores.
Moss still managed to grow operating profit from £3.6 million to £4.2 million, and cash was stable at £21 million despite £4 million in dividend payments.
My opinion
I quite like the proposition here. It seems conservatively run, not just in terms of the cash balance but also in terms of the store portfolio. It had 124 stores in January 2016, so the net increase is just 5 stores in 18 months.
Tactically, I don't think I'd buy the shares just yet. The company's USD requirements are hedged out to Spring/Summer 2018 and when those hedges expire, I wonder if margins might take a hit. So I think we might get cheaper opportunities to buy into the story here..
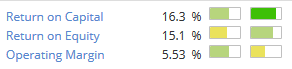
All that being said, the StockRank remains very high at 92, including some above-average quality metrics:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

40 comments
It was HVN AND MOSS BROS with stock ratings of 98 and 92, so comment on BOO is not so relevant,but the timing comment I made IS. Even with a very good stock investment timing is so important.Luck must still play a big part in profit or loss from shares. JNFINANCIAL had me on a cfd long position for around a year which eventually wiped me out--the stock was IQE and I sold in a margin call at 16p--now look at it. Thatt was 2013/14. Timing out 3 years.
I have registered the stock ratings of 2 companies as being rated as very high 92 and 98. I take it this would be a valuation of safety of the stock in rough waters,safety of any dividends,quality of management,investment outlook,and general future prospects to carry on making and improving profits.
Having seen this I was confused to see that BOOHOO.COM has fell from a high of 270p to195p. I am sure that the timing factor is very very important with these shares-as important as when 2 builders Persimmon and TW were advised me by a well known brokerage (same one who is changing name) when the price was above 1200p it fell like a stone to 900p and took 9months or so to get back to 1180p when i cancelled the account. TIMING-NOW DOUBLE.
I am very new to analising shares like they are analysed on here,-this could probably be a contributory factor of why I have lost so much and have now put all of my eggs into one oil and gas driller/producer hoping to get some back. 4 years ago With 70/80k to invest I could have thought about the moss bros andcenkos/Harvey Nash type investments but instead went for the suicidal cfd advisory account route with 5 different brokerage companies where I lost money with all. Prime markets £6000 and JN FINANCIAL £13/14k both gone bust.Galvan changed name toGain Capital-why lost £1800 London Stone Securities lost about the same. I also lost money with a fifth non advisory broker. All prmised the earth. No significant backing fromombudsman or fscs-onus on me to prove not on them to defend their forecasts. So i am loking for guidance to learn new skills to get my money back.playing with £5k with £10k invested dependant on oil price hitting $60 a barrel ( don't hold yer breath) this from another broker changing name!
Excellent point, Paul. Perhaps we could also encourage people to quote key sections of posts they are responding to? It makes reading and understanding threads much easier.
Excellent point, Paul. Perhaps we could also encourage people to quote key sections of posts they are responding to? It makes reading and understanding threads much easier.
Yes, I agree too and it's an old habit I learnt from early TMF days making sure you quote the section you are replying to. However, it also helps if you hit the reply button to the post your responding to (which I notice you have not in replying to Paul :-)) because then you get a little comment that says "In reply to Paul Scott, post #24" or whatever and if you click on it you can see the whole thread and only that thread. I quite like this feature, so well done Stocko!
To be fair, FrEng did this and it was really my oversight that caused the problem. My only excuse was a tough day at work (as opposed to downing cold beers whilst enjoying a panoramic vista of Dubrovnik harbour!) and I'd hit my third stage top out phase, mainly due to lack of caffeine... and we all know what happens after a 3rd stage top!
All the best, Si
Hi,
The mix up above just again highlights the need for everyone to please put the company name or ticker into every comment.
All too often I have no idea what company people are discussing here. Please put the ticker in, to make life easier for everyone!! :-)
Thanks, Paul.
As an aside, when looking at "Holding's in Company" announcements I notice that Hargreave Hale crops up fairly often, and I recall fairly recently some negative comment being made in respect of them on here. Is there anything noteworthy in relation to them please? Also, have they recently changed their name to Canaccord Genuity Group?
http://www.cityam.com/267917/wealth-manager-canaccord-genuity-acquires-hargreave-hale
Thanks FREng for explanation of HH name change :-)
Taken over by Cannaccord, I think.
Thanks Graham, another excellent report!
I cannot understand why Harvey Nash (LON:HVN) (in which I have a long position) seems to languish on such a dismal PER.
Too small for the SCVR, but Mobile Streams (LON:MOS) (in which I have a small long position, sadly) has put out a disappointing update today.
Touchstar (LON:TST) looks a tad uninspiring too (I also hold some of them)
Boohoo.Com (LON:BOO) really tanking now - it peaked around 270p, currently 195p - a helluva drop. Ties in very much with what Mark Minervini says in his book - best to sell out of growth companies when they're forming a Stage 3 top, and not wait for the inevitable (sooner or later) disappointment.
B est wishes, PAul.
Paul
I'd welcome your opinion on whether the Mobile Streams (LON:MOS) profit warning is a recoverable short-term problem or whether the likely losses make MOS uninvestable despite the cash they have (or had).
Hi FREng,
As regards Mobile Streams (LON:MOS) - difficult to tell, but my feeling is that it's probably uninvestable now.
I've got too many shares to be able to sell, so looks like I'll probably go down with the ship :-(
Or, it might have a resurgence at some point? I've mentally written off my holding in this one, so anything above zero would be a pleasant surprise.
Regards, Paul.
Thanks, Paul. The market is certainly punishing bad news savagely at the moment.
Thanks, Paul. The market is certainly punishing bad news savagely at the moment.
What bad news? I must've read a different RNS. I thought the results were great and they guided upwards on revenue and may do so again before the full year! It's painful when a share gets hit after good news but it's much better than when it gets hit after bad news :-)! Anybody would think Boohoo.Com (LON:BOO) is one of the time-waste basket cases that get more airtime than they should round these parts!!
All the best, Si
Si - Paul and I were discussing Mobile Streams (LON:MOS) not BOO.
Regards
FREng
Si - Paul and I were discussing Mobile Streams (LON:MOS) not BOO.
Sorry! My bad... have a thumbs up as apology! :-)
All the best, Si
Yes Boohoo.Com (LON:BOO) has dropped back about 25%, I was tempted to buy some, but is that no different from IQE (LON:IQE) recent fall?
Hi Graham,
Thanks for the views on CMC Markets (LON:CMCX)
I don't hold it, but do hold Plus500 (LON:PLUS) and recently held IG Group (LON:IGG) until a ridiculously steep and temporary spike down when it released it's revenue update last week triggered a stop loss I had. I have to have a slight re-think on my stop loss strategy, although the spike down looked suspicious, but that's for another time/post.
I am most optimistic about Plus500 (LON:PLUS) out of the three, although IG Group (LON:IGG) comes a very close second. Plus500 (LON:PLUS) came out with an outperform trading update yesterday, with the consequences of that to be clarified in the next scheduled trading statement on 31 October. Plus500 (LON:PLUS) has outperformed in (without fact checking) the last three or four trading updates/results. It also has the lowest forecast P/E (which should now get lower on a stable share price), has the highest dividend out of the three, and bought back some of its shares over the summer. The lower P/E could be because it is an Israeli company, but it has done all it reasonably can (through substantial dividends) to demonstrate that it is not over here to steal investors' money.
I agree with what you say, in that IG Group (LON:IGG) is definitely the market leader, much bigger, and has much more diverse products and geographies. It is less likely to suffer if any regulatory changes are particularly onerous/unforeseen - I would still own it if it wasn't for the stop loss issue. However, Plus500 (LON:PLUS) seems to be on a tear, and has stated expressly, several times, that it is "already compliant with the latest updates from its different regulators" and seems to be confident that any further regulation will only help it/the industry generally.
Thanks
Chris
Thanks for the input Chris, Plus500 (LON:PLUS) is interesting alright but the cost of extraordinary profits and short-term growth is extraordinary customer churn. I do wonder if it will be around for the long-term.
Regards
Graham
Hi Graham,
Thanks for that, I needed to hear something bearish. I checked the interim results where they talk about a conscious effort to improve the retention rates, and they say Q1 and Q2 had a low churn rate.
I will keep a close eye on that.
Ta
Chris
Graham, do you have any views on Green Dragon Gas (LON:GDG) ? They are a company that seems to offer sweet fruit-based spreads in the perpetual near future. This may be part of the reason for their slow but stead descent to their current market cap of approximately 90m GBP. Their interim results came out today:
http://otp.investis.com/clients/uk/green_dragon/rns/regulatory-story.aspx?cid=1089&newsid=932719
Hi, I'm very sorry but oil & gas is not a sector I analyse.
Regards
Graham
Graham (or anyone!): Are you able to make sense of the prior year adjustments in the accounts of Inland Homes (LON:INL) published today? (Note 14).
I don't hold, though I have made good profits here previously.
Compared to RWA (which has risen 20% since I bought them three months ago) IMHO the HVN performance is pretty poor; perhaps I'm not comparing like with like...?
Any chance of some coverage on Andrews Sykes (LON:ASY) Graham? They released their interims this morning, rather bizarrely at 9.30am.
The outlook is "cautiously optimistic" which is a phrase they have used in every market update going back to the FY15 finals. That's probably as good as we are going to get from this company, even though trading in Q3 has "continued to be positive. Europe has experienced strong results... as a result of continued high demand..."
Dividend held at 11.9p for the 4th consecutive year for a yield of around 3.7%.
It's such an 'under the radar' company due to the minuscule free float, I can't even see any broker forecasts which I think could present an opportunity even after a 75% increase in share price over the last year.
Re Andrews Sykes (LON:ASY), "Under the radar" for a reason, I'd suggest: a tiny free-float of only 8.2% is contemptuous of outside shareholders, who can have no real influence on the running of the group and who are at significant risk of a compulsory purchase of their shares at low prices when the business goes through hard times (as an equipment-hire and -selling business is bound to every few years). I've learned that that the hard way.
And good luck getting out in a hurry upon bad news if the free-float is only 8.2%.
I have no position in Andrews Sykes (LON:ASY). Good luck to those who do.
Regards,
Ed
Bestace - Just to emphasise the point made by ed miller. I bought ASY shares earlier this year and it took a devil of a job to sell them. Highly illiquid.
I have been a shareholder of Andrews Sykes for quite a few years and it is about as close to a private company which is listed as you can get. It is run with a long term horizon, but then I am a long term investor so I regard this as an advantage. The lack of liquidity could indeed be a problem, but not really for the few thousand pounds that I have in the company. A criticism often levelled is the lack of influence of outside shareholders as a huge majority of shares are in the owners' hands, but the company has been listed for about 30 years and has had many good and bad times and this does not seem to have been a problem for shareholders who have seen the share price increase by more than tenfold during this period, or by much more if you reinvested the large dividends. The company has been around for 160 years so presumably it is quite resilient! You might want to read the article by Edmond Jackson published on the iii web site on 17.2.17 if you want some more info.
Quick comment on Harvey Nash (LON:HVN) debt - it often goes up at the HY due to timing of payments. Contractor revenues go through their balance sheet and the size of those dwarf the market cap so these swings have occurred regularly in the past. The company say:
However, average borrowings over the six months to 31 July 2017 were lower than the comparative period, as reflected by the 29.7% reduction in finance costs.
So it's not something that concerns me personally given the company's history of effectively managing these working capital flows over the past few years.
dangersimpson - Re. £HVN Something that is puzzling me. I have in the past recruited contractors from Harvey Nash and know that they pay most contractors on a weekly basis, but they don't collect the fees for anything up to 3 months later.
Looking at the balance sheet, that is not reflected in the receivables/ payables data. What am I missing?
Hi Ramridge, have twice secured contracts via HVN..... was only paid monthly.... not weekly.
Note this was 2012 & 2014....so may have changed since
Hi Ram,
Remember that the the balance sheet figures represent a point in time so are the sum of all past transactions. In a steady state and at a point in time the NWC could be anything. Harvey Nash (LON:HVN) are paying for contractors weekly but invoicing on 90 day terms but if there is no change the cash flows balance since they are getting the cash in this week from what they billed 3 months ago. What they owe and what they are owed roughly balances. The initial timing difference is effectively funded by the company through equity or retained earnings. It is when you get changes in contractor numbers that the NWC fluctuates.
That combined with the fact that contract resources are just one part of their business with different working capital characteristics should explain it.
Cheers, dangersimpson
Hi, that's right, I just thought I should mention it since the second acquisition also will have affected it.
Cheers
Sorry to do this Graham, but what do you think of the loan notes issued at Dillistone (LON:DSG) (to board members) ? I am a long-term holder, and still think the company has great potential.
(On the positive side it suggests great confidence by the management, but at the same time it seems a wee bit cheeky to limit the scope of the offer, and the interest rates seem quite high).
Hi, on Dillistone (LON:DSG), I haven't looked at the results but the rationale for issuing those loan notes sounds reasonable. It says that the terms are equivalent to the best terms offered by institutional investors to make a loan, but also don't carry certain restrictions. So it's a better deal for the company than it could otherwise have got. Obviously you need to have some level of faith in the integrity of management to trust them on this.
The interest rate is high but not exorbitant. And £400k is a fairly small amount so I can't imagine it would have been cost-effective to ask private shareholders if they wanted to participate. Just my 2c.
On Dillistone (LON:DSG), I tend to agree with you, and I give the management a reasonable amount of trust - but still seems a bit cheeky.
I have held these shares for a year and sold them today - as for once there was some liquidity. Results were OK but my mainreasons for selling: were:
1). New product will not be profitable until 2020 - so difficult to see sharp turnaround.
2). Before that expect to lose £600,000 revenue from one client, which will give a big hit to profits, presumably.
3). The fact the company needs to borrow £400k from management indicates management does not expect any significant improvement in cash flow.
Cheers Graham, much appreciated. I actually have every confidence in the management here, especially Mike Love, who has an excellent track record. Thanks again.
My morning smallcap tweet:
NAHL (LON:NAH), Mobile Streams (LON:MOS), Zambeef Products (LON:ZAM), Filtronic (LON:FTC), Moss Bros (LON:MOSB), Telit Communications (LON:TCM)
NAHL Group (NAH) CFO resigns, leaves Dec. Sounds amicable. New one found. I'm long
Mobile Streams (MOS) warns revenue and EBITDA for the current FY materially lower than current market expectations due to ongoing decline in Argentina and increased competition in India. Who'd have thought?
Zambeef Products (ZAM) Everybody's favourite African cold-chain foods producer and agribusiness says wheat fungus problem not as bad as expected, will make a small profit for the year after all.
Filtronic (FTC) Q1 broadly in line with management's expectations. Positive comments leave me in the dark as to how broadly they mean.
Moss Bros Group (MOSB) gets a new suit. CFO of Paddy Power Betfair Group joins as NED.
Telit Communitactions (TCM) trading. "The Group is narrowing its financial guidance such that it expects revenues of $390m to $400m". Previous figs $400m - $430m (not given in RNS) so it's a big cut as well as narrowing. Similarly Adj EBITDA $44m to $48m (was $47m - $60m). New CEO has "commenced a review of its activities with a view to delivering a significant rationalisation of the Group's product lines and reduction in its cost base which is in progress. Separately of this review, the Board has for some time been actively considering the future of product lines which may not fit the Group's long-term strategy." Expects to satisfy all financial covenants end Sept but "as a precautionary measure, one financing bank granted an advance waiver for any potential breach of a covenant as at 30 September 2017, relating to the ratio of, in broad terms, free cash flow generation against debt service obligations (being the covenant previously notified as having been breached and waived)" Also commissions an 'independent' report to refute dodgy accounting allegations: "The Board has considered previous speculation relating to Telit's financial condition, trading performance and business relationships. The Board remains confident of the strength of the financial controls within the business. For the sole purpose of providing reassurance in this regard, the Board has engaged an independent third party accounting firm to perform a review of certain elements of the Group's financials and this work is ongoing." If you are paying for a report, it may be impartial but it ain't independent. I'm short.