Small Cap Value Report (Thur 7 June 2018) - Mello South, RFX, VLTY, CMCX, PLUS, INL

Good morning all,
Time for a quick public service announcement.
David has informed me that there are still a few tickets remaining for the Mello South conference which is taking place exactly one week from today (on Thursday, 14th June) in Hever, Kent.
Among the speakers will be Leon Boros, David Stredder and fund managers Mark Slater and Andy Brough. I will be there too, live-blogging the SCVR. And of course there will be a wide variety of quality companies for you to speak with.
It promises to be another hugely interesting Mello Event, this time in the south of England and for one day only. I recommend grabbing the last few tickets. Here's the link.
Ok, time for some analysis.
Today we had interesting announcements from:
Ramsdens Holdings (LON:RFX)
Veltyco (LON:VLTY)
CMC Markets (LON:CMCX)
Plus500 (LON:PLUS)
Inland Homes (LON:INL)
Ramsdens Holdings (LON:RFX)
(Formatting is broken, so I can't put the share price here - apologies.)
Great headline numbers from this diversified financial services provider, headquartered in Middlesbrough:
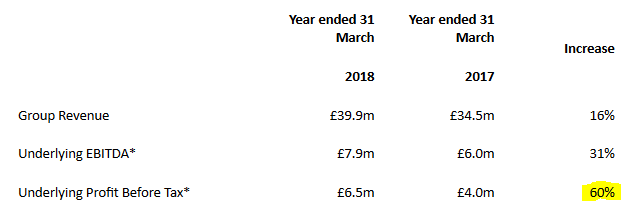
Foreign exchange is leading the way and profitability per customer has improved, so I'm guessing that people are using Ramsdens more frequently or for larger transactions - a great sign of customer satisfaction.
Margins in this segment have also improved (and it just goes to show how uncompetitive banks are at doing this, that a company can steal their market share so profitably.)
The number of FX customers is up 13%, but FX revenues are up 26%.
(As an aside, it might be worth noting that the vast majority - 86% - of Ramsdens' total customers are using the FX service. It's inevitably a lower-margin activity than pawnbroking and precious metal dealing.)
As with H & T (LON:HAT), the pawnbroker in which I hold shares, Ramsdens is also doing very well in jewellery. Sales in that segment are up 35% to £8 million. Up until a few years ago, it seems that pawnbrokers didn't realise quite what a big opportunity they had in jewellery retail. It was always just something they did on the side. Ramsdens and H&T are both now selling jewellery online.
The Marsdens pawnbroking loan book is a good deal smaller than H&T's but it's still an important source of gross profit (stable at 25% of the total). Ramsdens earned a yield of 112% on its average loan book during the year.
As anticipated, main shirt sponsorship of Middlesbrough FC will come to an end, but the name will still appear on the reverse of the shirt. That will make for slightly less name recognition, I guess, but probably not a big deal.
Perhaps this is one of the reasons Ramsdens tends to beat expectations:
The sterling gold price remained steady throughout FY18, which was ahead of the Board's budgeted expectations.
I don't mind the company being conservative and assuming that the gold price will decline.
This is how expectations evolved during the year:
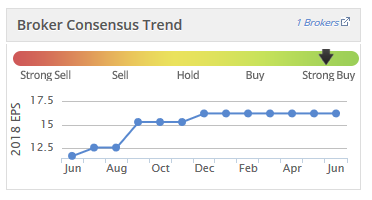
The outlook is very positive:
We have a strong platform on which to continue to build... I am confident in Ramsdens' ability to deliver on our strategic objective and continue to grow.
When you dig into the numbers just a little bit, you find they are very clean. The only adjustment made to PBT to get the "underlying" PBT is the addition of £161k of share-based payments.
So the actual PBT of £6.3 million is very close to the underlying PBT of £6.5 million.
My opinion
I've just done another quick calculation to figure out Ramsdens' return on tangible capital employed for FY2018, and I think it's about 13%.
I view pawnbrokers (or "diversified financial services providers"!) as small hybrid banks, so I'm not expecting or requiring massive returns. A solid and predictable return without too much risk is fine with me.
So in that context, I'm entirely satisfied by this result. 13% year in and year out would result in a fine outcome for shareholders. I've not adjusted for leases, which would reduce this return percentage.
Stocko algorithms think that the quality metrics are even better than I do and give it a StockRank of 91, since it's also not too expensive and has excellent momentum:
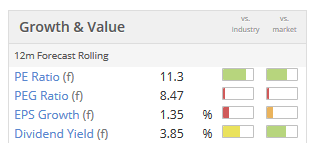
So if I wasn't already quite heavily invested in H & T (LON:HAT) (which I am still very happy to own), I would probably want to open or enlarge a long position in Ramsdens!
Veltyco (LON:VLTY)
This is a marketing company for the gaming (casino/sports betting) sector. Last time I covered it, I said that I felt compelled to take a bullish stance on it, since the sales momentum was just so strong.
The shares have remained on a cheap valuation, which I guess reflects the high-risk nature of the business. As described in its admission document, it was reliant on the revenues generated by a small number of high rollers it had brought to its marketing customer Betsafe.
Today's announcement provides the results for the period to December 2017.
Momentum continues: revenues were up 165% in 2017, and are up by another 60% in Q1 2018.
Note that the company has grown with the help of some acquisitions since Q1 2017, so the 60% growth rate in Q1 is not entirely organic.
Veltyco has made a couple of purchases, of which the most noteworthy is a 51% stake in the sportsbook "Bet90" (bet90.com), for €2 million. Despite the low price, this website is forecast to be "a key driver of further growth in 2018".
It has also bought a database of 26,000 active financial traders and they will be on the receiving end of marketing for a new online trading brand to be launched by Veltyco later this year.
The strategic vision is to own its own brands:
The majority of our revenue continues to be derived from online marketing activities but we are also seeking to increase the level of operational control we have by owning our own brands.
This would make it a significantly higher-quality stock - owning its own internet assets, rather than acting as a helper for bigger companies.
The company still has some cash reserves despite making these various acquisitions, and proposes a maiden dividend of 0.25p.
Receivables & cash flow
Banks have been a source of difficulty and this does sound like a worry, although the company says it does not expect that this will be a problem going forwards:
The Group has experienced some operational difficulties in receiving agreed marketing commissions within the online financial trading vertical due to internal processes applied by the Group's banks, however, the Directors have received written confirmation from the operators that the commissions are due and payable to the Group. The Directors started the process of restructuring the Group's banking relationships during 2017, in order to collect the receivables from all trading operators in different locations, without any restriction and the benefits are already being seen and are expected to increase in the coming months.
Banks may have been worried about money laundering and regulatory issues, I wonder?
Since the year-end, the outstanding receivables balance caused by these banking problems has been significantly reduced:
Since the year end, the Group's total receivable balance of €14.1 million as at 31 December 2017 has been reduced to €4.9 million, all of which relates to the online financial trading vertical
How the balance was reduced is a little tricky to unpack.
For example, €4 million of receivables were cancelled by the debtor giving Veltyco the financial database mentioned above.
Another €2.5 million of receivables were cancelled by setting them off against a loan that Veltyco had received from a company owned by its COO (although the Board didn't know this at the time).
My opinion
This is an Isle-of-Man headquartered, fast-growing and high-risk online gaming stock.
I still feel compelled to take a bullish view on the shares, given the strength of trading momentum. The performance has been superb and the potential for further growth is excellent. So I'd be open to making a small investment in this.
I do think it will take some time for the company to earn trust from investors, given the recent complications with receivables and related party transactions.
CMC Markets (LON:CMCX)
This is another financial stock where I own its larger rival. I am a shareholder in spread betting/CFD giant IG Group (LON:IGG) (many of us are clients of IG, too).
CMC shares have produced a more than 100% return for shareholders, including dividends, since the height of regulatory fear in December 2016.
These results are excellent: net operating income up 16% to £187 million and PBT up 24% to £60 million.
Regulatory comment
I think that regulations have mixed effects on an industry - the overall effect on the larger players can be rather good, as competition gets muted. Understanding and complying with a complex set of rules becomes another barrier to entry, and limits the ways in which new entrants can compete for business.
As a shareholder in the industry, therefore, I'm not too scared by the new margin requirements on spread betting and CFDs.
CMC's view on recent regulatory measures:
The Group welcomes many of the requirements, and is pleased that we now have clarity; many of the ESMA requirements have already been in place throughout the Group for some time. Whilst these changes are likely to have some short-term adverse effect on the Group as clients adjust their trading behaviour to these new requirements, the Board believes that a stronger and better industry will emerge. In that process the Group will be a clear winner through its focus on high value clients, service and technology.
The important thing to remember about spread betting companies (and the same is true for online casinos), is that most of us are irrelevant to them, and they don't really want to deal with us. It's the high rollers who determine the financial success or failure of the operation.
Focusing on high-value clients
CMC has adopted the IG strategy of letting low-value clients head for the exits, instead focusing on those who are going to be active and in big size. Its internal measure of "premium clients" increased to 10% of the total client base.
Left-column is FY 2018, middle column is FY 2017:
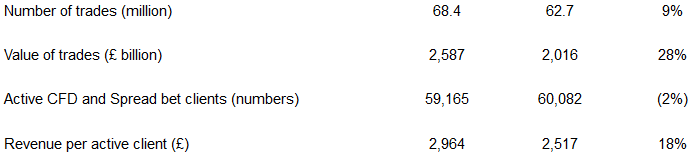
The value of trades is up by a higher percentage than the number of trades - good.
Active clients down, revenue per client up - good.
So the company has more high-value trades and a more valuable set of clients - perfect.
CMC expects that greater than 40% of UK & European revenue is generated by clients who will be classified as "professional", and therefore exempt from the rules on retail clients. This is another reason to expect a limited effect on results from the new rules.
(I think that IG still has a higher-value client base - it previously forecast that 50% of its revenues would be generated by professional clients.)
The company has only offered crypto trading since February, at a 50% margin, to professional clients. So whatever boost it had from that asset class was probably very small.
CMC also has a stockbroking arm and a partnership with ANZ Bank in Australia, which sounds like it is doing well. CMC is set to become the 2nd largest retail stockbroker in that country. Given its progress, I would expect CMC to expand its stockbroking activities in the future. Interesting that CMC and IG are both very active in this service now.
The dividend is unchanged and this likely reflects some caution ahead of the regulatory changes coming into effect over the next few months.
My opinion
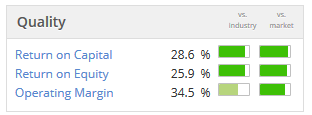
This is another stock which I would be happily buying if I didn't already own plenty of shares in its biggest competitor. The StockRank is 87 and take a look at these quality metrics:
Plus500 (LON:PLUS)
Plus500, a leading online service provider for trading CFDs internationally, is pleased to announce that its business continues to trade strongly. Accordingly, the Board has materially increased its expectations for the Group's financial performance for the year ending 31 December 2018.
This Israeli CFD provider continues to do spectacularly well.
Q1 was exceptional, thanks to market volatility and lots of crypto trading. Even though Q2 has returned to a more normal level of trading, it is still "materially ahead of management expectations."
Note however that guidance as to how ESMA regulations will affect Plus500 is much weaker compared to the guidance from CMC and IG:
As previously announced in the 1 May 2018 trading update, the full impact of the ESMA measures, which are now confirmed to take effect from 1 August 2018, are difficult to assess. Similarly, the Group's performance could also be impacted by the rate at which customers request to be reclassified, and are accepted, as elective professional clients.
I expect that very few Plus500 customers should qualify as professional clients. When you consider Plus500's enormous churn rates, you have to conclude that Plus500 serves the least knowledgeable, most amateur traders who are sucked in by an internet ad and quickly lose their entire account.
Cable Car Capital (with which I have no involvement) attempted to short Plus500 back in 2015, with a 76p price target. Clearly, that trade has not worked out particularly well so far. But I still share many of the concerns raised at the time.
My major concern is around Plus500's hedging policy. IG, for example, has residual exposure to client positions of close to 0%.
I doubt that Plus500 is properly hedged, which would help to explain its extraordinary profitability as it simply pockets the losses incurred by its clients.
There is no problem with that in the short-term but it significantly increases the risk levels in relation to black swan events when clients might be on the right side of the trade.
I could be wrong, but I suspect that this company will either blow up in a black swan event or be shut down by regulators at some point. The day is coming soon when it will have to deal with ESMA rules - that will be very interesting indeed.
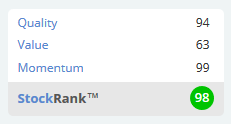
It enjoys a huge StockRank of 98 thanks to its amazing performance over the past several years, but I do think that a cheap valuation is more than justified:
Inland Homes (LON:INL)
£95 million sale and development of Ashford, Middlesex site
(Please note that I own shares in INL.)
A big sale to A2 Dominion, "one of the largest housing associations in the UK":
The transaction, which is the biggest land disposal by value undertaken by the Group to date, is for a total land and build consideration of £94.7 million, with the land consideration being £29.7 million in cash payable on completion. Inland Partnerships, the fast-growing construction arm of the Group, will undertake the development phase on behalf of A2 Dominion.
The CEO is very bullish about what this means for the continued progression of the business:
This deal, together with our pipeline and the supportive market backdrop, gives us confidence that within two years the Inland Group will complete the construction of over 1,000 residential homes per annum.
I was initially attracted to this by the discount to EPRA NAV (the net asset value including unrealised gains on properties). EPRA NAV was last seen at about 93p per share (today's share price is 69p).
Today's news offers additional confidence that NAV can climb (or at least not fall), while the discount in the share price has the potential to narrow from its current level. I would expect the discount to narrow somewhat as gains are realised (e.g. by today's deal) and show up in cold hard cash and physical assets.
The Stocko algorithms are very impressed by it, and I do think that we can get a pleasant return from this share, without taking on too much risk. Earnings will of course by cyclical. As always, please DYOR.
I might leave it there for now. If tomorrow is quiet, I'll come back to review Impax Asset Management (LON:IPX) and Onthemarket (LON:OTMP).
Thanks
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

54 comments
Graham / Paul / All
VLTY - Red flags
I have been looking into VLTY over the weekend and especially its links to a Uwe Lehnhoff, who seems to be involved in all the companies VLTY trade with. In summary I did not like what I found and have closed all positions in VLTY.
A few links and notes :
Option888 (Celestial Trading Ltd) seems to be the only client of VLTY in the On-line financial trading vertical
https://www.dailyforex.com/option888/option888-review/2240
Option888 is one of the fastest growing binary options brands on the market today. What sets them apart from the others is their intuitive and user-friendly website, live support and personal brokers in 7 languages. Navigation within the website is easy and confirmation after setting up a trading account is received within a few minutes of its submission. There are many nice features on the binary options trading platform and a nice choice of several different binary options.
https://www.trustpilot.com/review/option888.com
Close down of Option888 activities in Germany and Austria from 21/03/18
https://www.kanzlei-ebp.de/news/capital-force-option888-bafin.html?gclid=EAIaIQobChMIm56vjerI2wIVlcmyCh0qXQUhEAAYASAAEgKSl_D_BwE
Public warning - Altair Ltd
https://www.globalinvestoralerts.org/altair_entertainment_nv.shtml
Option888 Not registered in Italy 27/12/16
http://www.consob.it/web/consob-and-its-activities/warnings/documenti/english/entutela/cns/2016/enct20161227.htm
- the companies Altair Entertainment Nv, Payific Ltd and Capital Force Ltd are not authorised to provide investment services and business in Italy in any way, including through the website www.option888.com;
Uwe Lehnhoff - Related Parties
https://fintelegram.com/veltyco-group-related-party-transactions-and-offshore-business
29/03/18
RNS - ESMA Ruling
The Company confirms that none of the operators for whom Veltyco undertakes marketing activities offer a binary option product, as such products have previously been withdrawn in anticipation of such regulatory changes. Furthermore, the operators have confirmed to the Company that they are operating in line with the restrictions proposed by ESMA on CFD trading.
As part of the ESMA's submissions I actually mentioned that it is ridiculous:
1. A cfd provider is allowed to bet against its clients and not hedge risk.
2. A cfd provider is allowed to set its own prices which may or may not be true market prices to which they purport to represent.
3. A cfd provider can exist outside the jurisdiction of the ESMA like Plus500. In fact, I said that all cfd providers should have separate entities for every national office (as we have done with banks in the wake of the financial crisis). Frankly, I am just as worried about regulatory capture of a Malta or Luxembourg etc. as I am for them to be run from Israel.
Given the toxic cocktail above, I would have concerns that a provider could dodge 'risk' by essentially setting their own prices for events like the Swiss Franc. Try getting your money out of a provider located in Israel for instance if the sh*t hits the fan.
In short, the regulatory changes thus far are just the beginning would be my guess. And that further changes will favour the likes of IG and City...as per the editorial comment in the article.
I suggest Paul actually reads the Plus annual report which sets out their hedging policy rather than publishing his alarmist speculations on the subject.
I suggest Paul actually reads the Plus annual report which sets out their hedging policy rather than publishing his alarmist speculations on the subject.
Graham's writing the report solo this week. There's a nice big picture of him at the top of the page, looking suave and sophisticated.Anyway, the Plus500 annual report does have a few things to say about hedging, but I think it would be pushing the boundary to suggest that this gives a comprehensive view of the policy or addresses how the regulation is pushing it to change:
That doesn't really add anything to the debate. In the end there is some exposure, it's not entirely clear how tail event risk is being managed and there remains the suspicion that an extreme event might cause serious damage. And ESMA must have some impact on a high volume, low roller model.
On the other hand it's undeniable that Plus500 (LON:PLUS) has been a great investment. Whether you want to be in it now is probably a question of risk appetite, but it's certainly not one to put in the buy and forget box hidden in the dingy recesses of the attic.
timarr
Intercede (LON:IGP) reported today and appears to have attracted no comment here at all. A micro cap, with a former very underwhelming management, Intercede suffered a number of nasty surprises, that were covered in Stockopedia, but with the old managers replaced, things seem to be getting onto an even keel.
Their principal cyber protection ID product appears to be gaining ground and there is some indication that Intercede's days as a serial disappointment are drawing to a close, today's 7% price gain supporting this.
They are surely not yet safe and cash will probably need to be raised before too long, but if they can go on showing tighter costs and growing revenue the future could be a lot brighter
Intercede (LON:IGP) - looks interesting. Crap performance. I've had a punt on it.
P.
Graham,
I emailed the investor relations head at Plus500 (LON:PLUS) several months back asking if they hedged and how would they deal with a black swan event. I never recieved a reply and sold out over these concerns. It has cost me dearly with the price surge but their failure to address this is a serious red flag.
Dave
Hi Graham,
Few points to consider on Plus500 (LON:PLUS) (disclosure long)
With regard to risk management, the biggest recent black swan event in a major FX market was the Swiss franc de-pegging move in January 2015, which Plus500 handled very well. I think IG Group (LON:IGG) faired significantly worse from this event, seeing significant losses and also going after clients who had moved to negative account balances. See Plus500's comment here: https://otp.tools.investis.com/clients/uk/plus500/rns/regulatory-story.aspx?cid=1399&newsid=713242
Vs IG:
https://www.ft.com/content/fd345146-9ccc-11e4-971b-00144feabdc0
https://www.independent.co.uk/news/business/analysis-and-features/how-could-a-teacher-on-18000pa-lose-280000-spread-betting-10115157.html
Plus500 seem to prefer lots of small customers, who have small positions, as part of their risk management. Having high value clients who take big positions can actually be riskier, perhaps more so once ESMA bans negative client balances, if a big position moves quickly against the client and would have pushed them in to negative territory (by missing a stop), you may find the broker taking this hit instead.
It will be interesting to see the impact of ESMA on Plus500, they have previously often sounded quite positive about clarifying the regulatory environment. On this note, I wonder if the decision for them moving to main market (where they will likely join the FTSE 250 index) is related to the greater clarity on the regulatory side for Europe.
Will also be interesting to see how they grow worldwide, they have obtained various licences for other countries recently.
Hi clouds, thanks for the comment - do you think Plus500 (LON:PLUS) was hedged in EURCHF? I expect that it wasn't.
There is something magical about the idea that extreme leverage by clients can be combined with no risk of them losing more than their deposit. The risk of the net client position must be sitting somewhere - if it's not with the client, and if it's not externally hedged, then it must be with Plus500 (LON:PLUS).
Hi Graham,
Firstly I would welcome more transparency with regard to how Plus500 (LON:PLUS) manage their risk. My guess would be that they weren't hedged in the CHF incident... however I'm not sure that's necessarily worse than being hedged.
I haven't fully worked this through so may not be correct, would appreciate input, but:
- If you were fully hedged, and you give the winners the large gains, and the losers don't pay up (fully), then you are potentially left with real losses on your hedge, as the price you've exited the hedge at is substantially worse than that which customers effectively got i.e. they get a better "price" by failing to pay their debts. My understanding is IG did have to write off significant customer debts.
- If you are not hedged, you close out losing customers without issue, but do have to pay up for the winners. Big question to understand how Plus500 faired on the day would be what the balance of customers was, and how much they had to pay out for winning customers.
I wonder if they generally just don't allow any individual instruments exposure to get very high: "The Company's proprietary risk management system ensures that overall exposures to a single instrument, such as the Swiss Franc, are unlikely to have a material impact on the Company's financial position."
I'm not sure what you're suggesting, presumably you see the impact as sitting with Plus500 (and I can see how you get to that), but if you accept that's reflected in their accounts then presumably that shows it wasn't a big issue. If you're questioning the accounts, that's a whole different game, but I would point to the very strong cash generation and large dividend payments as supporting the idea the accounts are valid.
In their risk disclosure notice Plus500 (LON:PLUS) state: "...it is not possible to lose more than the amount invested and customers cannot be left in debt to Plus500. Trading CFD’s is not suitable for all investors; make sure you fully understand the risks involved."
So a user is protected to that extent. Figures bandied about for these platforms is that nearly 90% of people lose money. Would the resulting mountain of money in itself not act as a significant hedge?
Disclosure: took profits some months ago, (unfortunately).
re: Plus500 (LON:PLUS)
Hi shine,
The user is protected, yes, but my question is what about the broker?
For a hedged broker, the purpose of customer losses in excess of their deposit is to protect the broker in the event that it is not possible for the broker to exit their hedge in a timely manner, when the customer has a losing trade.
Or if we look at it at an aggregate level: if most customer trades by value are (say) net long, then the purpose of customer losses in excess of their deposit is to protect the broker in the event that the underlying asset collapses in value too quickly for an orderly exit - the broker will have had to buy that asset, to hedge the net long position.
But if the broker doesn't buy the underlying asset, then it doesn't care if the asset collapses, as it simply pockets the net losses of its customer base.
To clouds: I am not questioning the validity of the accounts. I am saying that the risks being taken to achieve its results are of a different magnitude compared to the risks taken by brokers who hedge. Plus500 (LON:PLUS) is a bucket shop.
there is slightly more to the debate than whether a provider is 'hedged or 'unhedged'. A black swan event like the CHF revaluation in January 2015 exposed a couple of risks that were either ignored or dismissed previously . Firstly it is important to remember that leverage in currency trading is generally much higher than in equities, heck we see 40% moves weekly in equities but a move of 40% in a currency pair is very rare. Secondly many of these CFD or synthetic positions are put on with guaranteed stop loss or 'limited risk' CFDs (option traders will immediately recognise this is akin to writing deep out of the money calls or puts). So even if the provider is perfectly hedged to start with, he may have a problem with his dynamic hedging on a gap up or down. The client hits his stop loss and so is out of the position but the provider may have to take significant slippage on the hedge before he exits. My understanding is that this was very significant in the CHF move. In addition, if the client takes a loss that is greater than the equity in his account, the provider now has a credit risk problem.
Thanks for the reply, Graham.
As you say, apart from the client being protected, what about 'the broker in the event that the underlying asset collapses in value too quickly for an orderly exit'?
I'm just looking back at the Swiss franc surge that has been mentioned on here. An Independent article suggests IG (who didn't protect clients from losing more than their deposit) struggled to close positions as the situation unravelled and yet surprisingly total client losses were just £18.4 m. (IG ended up £30 m down, as it was unable to close its hedging positions on bets because of the extreme volatility'.) Obviously some future event could/will be a lot more painful than this, but doesn't there come a point when Plus500 (LON:PLUS) with its cheapskate model (minimal or non-existent hedging cost) has found a way of making a mountain of cash and is using it? Having a quick look at their balance sheet on Morningstar they appear to have a quarter of a billion dollars as of end of Dec 17 (and that's before making a killing on the crypto craze earlier this year). Why hedge?
Interestingly, it took three years but the Swiss franc seems to have settled back to where it was against the euro.
Having a quick look at their balance sheet on Morningstar they appear to have a quarter of a billion dollars as of end of Dec 17 (and that's before making a killing on the crypto craze earlier this year). Why hedge?
Because one day the model could fail catastrophically. If you invest in IG Group (LON:IGG) you can be as close to certain that you'll never suffer a total loss of capital, while investing in Plus500 (LON:PLUS) doesn't carry the same level of certainty.
If you analyse what happened around the unpegging of the Swiss franc the only real explanation for Plus500's outperformance appears to be pure luck. Technically they were running a balanced trading book - basically customers can only lose what they have in their accounts. Now even a one-eyed, half-cocked analysis would suggest that if the amount people can lose is capped and the amount winners can gain is uncapped then there's a big hole, which the company has to fill. There's no magic to this, it's just bookkeeping.
Best guess is that Plus500's long tail of mug punters simply weren't betting on the Swiss Franc before the unpegging event, so their initial exposure was tiny. IGG's clientele were a deal more experienced and wise and IGG got caught on the wrong side of a Black Swan event. But they know this will happen, that's why they hedge, although no hedge can fully protect against the completely unexpected.
I don't have any view on what will happen to Plus500 in the future, it may well continue to make significant amounts of money and deliver extraordinary gains for investors: or it may not. I am, however, reasonably sure that IGG, where I hold a decent stake, will continue to thrive and in a decade or so will have grown its market cap significantly. At the very, least future surprises won't put it out of business.
As ever, you pays your money and you takes your chance.
timarr
Plus500 seems to "hedge" by crippling the product: sometimes they just close a side (disable trading), presumably when their book is imbalanced, e.g. it looks like that if a lot of people are say long the FTSE they only allow new short trades, until the book balances. Add size limits (no big trades) and it's pretty bullet proof. A normal broker's customers wouldn't tolerate that kind of "service", but as they concentrate on lower life forms they get away with it. The main risk is probably regulatory, or the principals doing a runner, or that copycats exhaust the addressable market.
I'd just like to thank Ed today for a great Webinar, been using Stockopedia for about 6 months now after the rec from the Naked Trader, it's one of the best written pieces of software I've seen
Another request for Impax Asset Management (LON:IPX) please!
IPX is on the list for tomorrow! Thanks.
A suggestion Graham. Friday is normally a quiet day in RNS land, why not carry a few over into tomorrow’s report? I would add to the requests for Impax Asset Management (LON:IPX) and Alliance Pharma (LON:APH) both of which I hold. I for one, would be happy to wait until tomorrow for these to be covered.
Hi Graham,
I'd be keen to hear your thoughts on Ramsdens Holdings (LON:RFX) PBT +60% really did wake me up this morning!
If you have time, certainly Inspiration Healthcare (LON:IHC) Alliance Pharma (LON:APH) Inland Homes (LON:INL) Sopheon (LON:SPE) have all released significant news this morning.
Thanks,
IG
Disclosure: I hold all companies mentioned
That's a lot of news IG! Let's see how far I get.
Ditto re: Inspiration Healthcare (LON:IHC), The IPO of NeuroproteXeon could unlock some 'hidden' value in IHC
Hi Graham,
Would be good to read your thoughts on Inspiration Healthcare (LON:IHC) announcement that a company they hold a 10% stake in NeuroproteXeon, will be considering an IPO for 2nd half of 2018. That 10% stake is valued at £111k on the books and NeuroproteXeon "is seeking a new money valuation significantly in excess of the $59 million achieved in its last round of financing, which completed in 2017" that should give some indication as to the value of that 10% stake.
https://www.investegate.co.uk/inspiration-health--ihc-/rns/potential-ipo-of-neuroprotexeon-limited/201806070700065742Q/
And
https://www.investegate.co.uk/neuroprotexeon/rns/announces-plan-for-initial-public-offering-on-aim/201806070700095761Q/
For those interested it's worth googling about the company neuroprotexeon and gauging the progress they've made and the potential of their product(s)
Disoclure: I hold, have added at times, and have declared it for a while over at twitter @mginvestor
Veltyco (LON:VLTY) : This is an interesting little play. Trading on a PE sub 10 now (9.5c eps full diluted) and growing at 60% in Q1. I reckon they could do close to €25m revenue this year and grown eps to circa 14c. Looks very cheap at 85p!
Trade receivables and cash was the key concern as they ballooned massively at y/e and would have been a big red flag for me. However, this appears to now be predominantly sorted. Post y/e TR have fallen to a much more reasonable level and net cash has effectively gone up £2.5m in last couple of months, with borrowings eliminated and €1.6m cash at bank.
A lot of upside too I think if they get their German sports betting arm, Bet90, functioning. Early signs look promising and of course a world cup year always helps too.
I'm interested in your opinion on Veltyco (LON:VLTY) too please, Graham, after the belatedly issued results.
Hiya, Veltyco (LON:VLTY) is in there now. Cheers! G
Ramsdens Holdings (LON:RFX) please, Graham. Although I think it's a given as this one is in your area of interest.
Yes, there was never any doubt I would cover £RFX! Cheers for the suggestion anyway. G
Good summary on Veltyco (LON:VLTY) Graham which, I think nails the salient points. I am bullish and have a small long position as I can see it doubling in the next year or so but I also agree that a couple of things are required for that
1) market confidence that trade receivables problems were a one off and indeed fixed per mgmt. we should see that in the net cash figure which, should be materially higher by end H1
2) evidence of strong continued growth in own brands, especially Bet90
Next set of results are important
Re Ramsdens Holdings (LON:RFX) The house broker has their projected their EPS up from 16.4p in 2018 to 17p for year 2019, which looks far too cautious. A counter cyclical play with excellent return numbers.
Re Ramsdens (LON:RFX) EPS broker upgrade is way too low. revenue growth has been 15%+ in the last two years driven by FX and retail, management very confident of continued growth opportunity. if FY19 sees similar revenue growth with stable gross margin (has been for 4 years) and continued controlled expansion of overheads to support growth sees EPS of 23-24p or up 45%. Would support a 5% dividend 2.5x covered by earnings and 2.3x by cash. Rock solid balance sheet and highly cash generative. £13m cash v market cap £57m and must be reaching the point where a special div needs to be considered.
I own this and H&T.
Interesting that the market is closed, but I can see live trades being placed for RFX. Buy price being pushed up from 190 to 195. This isn't the spread being changed by MMs, it's live orders being placed and accepted. Not much chance to get a top-up for RFX this morning.
Alliance Pharma (LON:APH) has had Dialectin (a morning sickness drug) approved by the european medical regulator. I believe its the only medicine of it's type approved for sale in the EU. It has sold very well for many years in North America. Really annoyed I missed out on this one!
Hi Is2g08.
Yes, Diclectin approval is a really big deal for Alliance Pharma. At the moment the share price is up about 6% today. So I have just topped up my holding.
I've just taken a quick peek at this for the first time (thanks for flagging!), including last year's North America sales for Diclectin and, given the success over there, I too am surprised by the lack of increase today.
This looks like a game changer for the company. Any idea why it's only up 6%?
Hi Abtan.
You ask why it's only up 6% today. Possibilities that I can see are:
1) Institutions are a bit slow to react to news due to their processes. I am hoping that this is the case because it would mean that the share price would continue to rise over a longer period of time.
2) Maybe the strong share price rise over the last 6 months has already taken into account the likelyhood of this approval taking place. I don't think this is what is going on because the value rank is only 42, so it's not expensive.
3) It's a fairly small company with a market cap of £430m, so might be too small for some of the bigger institutions to invest in.
Hope this helps.
Thanks for your thoughts, much appreciated
Hardman and Co have some good research pieces on this stock (commissioned by the company). The piece on Dialectin suggests that revenue per annum could reach as much as £40M per year (circa £10M in the UK and £30M in the rest of europe), within three years if uptake mirrors that in the US, however profit from Dialectin in the first few years will be outweighed by marketing and set up costs according to Hardman and Co. Also Brexit will be a factor in this, at the UKIS they named this as their top risk.
http://www.hardmanandco.com/docs/default-source/company-docs/alliance-pharma-documents/25.01.17-potential-of-diclectin.pdf
Alliance Pharma (LON:APH)
Thanks for the research link - it was a very interesting read, especially the section on Diclectin.
I actually think Hardman should look more than 3 years out; this is a drug that will undoubtedly reach the levels of utilisation seen within Canada where it has been sold for many years (80% of pregnant women seeking medical relief end up buying it there).
Looking at it from a long term view, and being conservative vs Hardman's stated potential customers (they seem to have added 80,000 live births in their note vs ONS published 2016 UK live births) gives me a long term mature revenue of $600m/£450m per year for the UK + 9 European countries. Huge potential for growth vs £120m currently being achieved.
My only hesitancy is what % of the profits is included within the licensing agreement.
On a personal note when my missus was pregnant she was unable to obtain Diclectin in the UK, but could get it in Portugal and said it was very effective. There does not appear to be anything like it on the market
Thanks again for sharing
A
I have also bought today. I saw them at the UK investor show, they were one of the few good companies there and I was quite impressed by them. Kept meaning to buy some but felt I needed to offload some stocks first. Missed out on circa 20% gains! Oh well.
(Bloomberg) -- The London Stock Exchange Group Plc said its opening auction has been delayed, a rare outage for the stock market.
A spokeswoman for the exchange couldn’t immediately provide more information.
The London Stock Exchange Group Plc said its opening auction has been delayed, a rare outage for the stock market.
Uncrossing now scheduled for 9am.
And Impax Asset Management (LON:IPX) just announced stonking figures, 57% increase to dividend and a special dividend of 2.6p. Very late RNS but luckily the LSE delay in opening makes it less serious. Worthy of comment Graham?
cheers
Francis
The figures for Impax Asset Management (LON:IPX) need unravelling a little due the the PAX acquisition which only affects the latter half of these Interim results. But the notes (3) in the RNS give some useful information.
From the date of acquisition, Impax LLC has contributed £4,840,000 of revenue and £964,000 of the adjusted operating profit of the Group. If the acquisition had taken place at the beginning of the year, revenue for the Group would have been £32,686,000 and the adjusted operating profit would have been £8,372,000
These figures look rather better than the quoted values in the RNS of
· Revenue: £25.7 million3 (H1, 2017: £13.9m)
· Profit before tax: £5.5 million (H1, 2017: £2.4m)
The full year figures should therefore be better than a simple x2 interim figures having 3 quarters contribution from the combined Impax-Pax entity.
The dividend increase is positive news with an increase plus a special dividend as a bonus.
Just wanting to second (third) the request for Impax Asset Management (LON:IPX) if you have time Graham. You have covered them before. The figures look great but what would be the like for like comparison:
1. New enlarged group vs the comparable figures from last year
2. or just the old Impax vs comparable from last year.
My initial impression is that the business and the acquisition are both going very well.
The risk as for any asset manager is that they can be a geared play on overall market sentiment. If the market goes down Impax Asset Management (LON:IPX) will suffer reduced revenues because assets under management (AUM) will fall due to
1. the decline in the market
2. customers selling out to avoid being caught in the crash
Having said this, Impax Asset Management (LON:IPX) coped really well with the last big recession. Many asset managers saw their share prices drop spectacularly whereas Impax Asset Management (LON:IPX) saw a relatively small decline and a quick recovery. At the recent presentation the directors said that this was because most of their customers are institutions rather than retail investors and that these institutions tend to be more 'sticky' - keeping their funds invested even through a recession. Let's hope they can deliver a similar performance when the next bear market turns up.
Disclosure - I am long Impax Asset Management (LON:IPX)
Looks like the London Stock Exchange's live price feed is down.
Intention to Float announcement from Amigo Holdings, another non-standard finance company, this time in guarantor loans, where they say they have 88% market share. Unusually they're heading straight for the main market:
https://www.investegate.co.uk/...
No new money being raised for the company, so it's an investor and management cash out. Free float only 25% to 35%. No prospectus published yet, so probably not worth more than a cursory look, but on a first glance it's interesting.
timarr
Sadly it's apparently more "non-standard" finance the world doesn't need, from the announcement:
Amigo's product is a single, simple product, under which individuals are currently able to borrow between £500 and £10,000 over a term of between 12 months and 60 months at a standard annual percentage rate of 49.9% [...]
Kudos that they managed to find mugs who fell for it. Surely the victims of this product would be considerably better off by having the guarantor borrowing on their own account at non-usurious rates and do a private loan to their poorer friend.
So we've got regulatory and market saturation risk, on top of psycho management risk (I wouldn't give a penny to the sort of twisted mind that can conceive such schemes, surely fleecing shareholders is their next hobby).
I understood this column was to debate the investment merits of shares. Whether you agree or not with the product being sold is for a different audience.
The Intention to List note from Amigo suggests that guarantor loans are very popular products. I am sure that the company would argue that guarantor loans are a smart way to deliver loans to consumers who wouldn’t otherwise be able to borrow OR can now borrow at a lower APR because of the existence of a guarantor. If any of the other companies in the UK now offering a copycat product to Amigo eg Non-Standard Finance (LON:NSF) is anything to go by, this note from Amigo is a valuable read across.
As it happens, you are misinformed about the owner of Amigo. James Benamor is a passionate investor in child education in the UK and one of the best entrepreneurs ever born here.
My morning smallcap tweet: Big talk from Feedback.
Artilium (LON:ARTA), Joules (LON:JOUL), NATURE (LON:NGR), Feedback (LON:FDBK), Avanti Communications (LON:AVN), Inspiration Healthcare (LON:IHC), Inland Homes (LON:INL), Ramsdens Holdings (LON:RFX)
Artilium (ARTA) rec offer by US Pareteum Corporation, mainly paper worth 19.55p, a slim 18% premium.
Joules Group (JOUL) FY trading: rev up 18.4%. Guides underlying pretax marginally ahead of analyst expectations, which is £12.6m.
Nature Group (NGR) the suspended basket case's FY results won't be ready by end June.
Feedback (FDBK) £8m tinpot grandly announces Revised strategy to build a global company. It is going to do everything better and "leverage its deep domain expertise."
Avanti Communications (AVN) awarded $20m in arbitration against Indonesia. Due end 31 July.
Inspiration Health (IHC) NeuroproteXeon in which it has a 10% holding plans IPO. Hopes for valuation "significantly in excess of the $59m achieved in its last round of financing."
Inland Homes (INL) sells Brooklands College site in Ashford for a total land and build consideration of £94.7m, with the land consideration being £29.7m. Dev will take 4 years. 619 sqm of commercial space will be transferred back to Inland for a nominal sum once construction is complete
Ramsdens Holdings (RFX) FY looks like a beat with rev up 16% and adj pretax up 60%. Hikes FY div to 6.6p from 1.3p. Current trading in line.
Morning Graham, can I request my daily regret: Ramsdens Holdings (LON:RFX) yearly results Basic EPS 16.3p (10.1p) up 61%, Dividend 6.6p (1.3p) Net assets up £4.2m to £27.6m, including cash of £14.6m, Net cash of £12.7m (FY17: £9.5m)
another one I sold out of a couple of months ago on fears that its exchange business's lunch would be eaten by the internet! Silly me!
Or am I? Cos I stuck it in Versarien (LON:VRS), which today has been appointed as the inaugural company in the National Graphene Association Industry Council in the US. I know Graham is wary of this highly-valued blue-sky stock so not a request but, though I've now stopped adding in order to find new minnows, with government, university and now 'official' backing in the US I feel this could be a fortune-maker, and certainly seems set to go global, as the CEO has been talking to two Chinese regions.
Good day to all!
Morning Graham, Ramsdens Holdings (LON:RFX) have released results for Y/E 31/3/18 and these look good overall with EPS increasing to 16.3p from 10.1p (adjusted for IPO costs). Pawnbroking, Retail jewellery and foreign currency all demonstrated growth in excess of 10% whilst Precious metals and other financial services also grew revenue. This is on the back of the store estate increasing to 131 stores. All in all it has resulted in the dividend increasing from 1.3p to 6.6p for the year.
It seems like a very well managed business with a considered increase in the store estate. I would appreciate your insights.
Good Morning to you Graham,
Can I be first up to request Veltyco (LON:VLTY) please? It demonstrating explosive growth,
and I see a upside from the current SP due to the World Cup. For the bears there is a question mark about agreed commissions not being received:
Looking forward to hearing everyone thoughts. I'm long.