Small Cap Value Report (Tue 14 April 2020) - Viral thoughts, JIM, CBOX, FLK, RBG

Good morning!
Graham here.
Viral thoughts
As you've probably noticed, markets are looking much more perky now, compared to three weeks ago.
Versus the recent lows:
- The S&P 500 is up about 25%.
- The FTSE-100 is up about 21%.
- The Euro Stoxx 50 is up about 24%.
(All indices measured in their own currencies.)
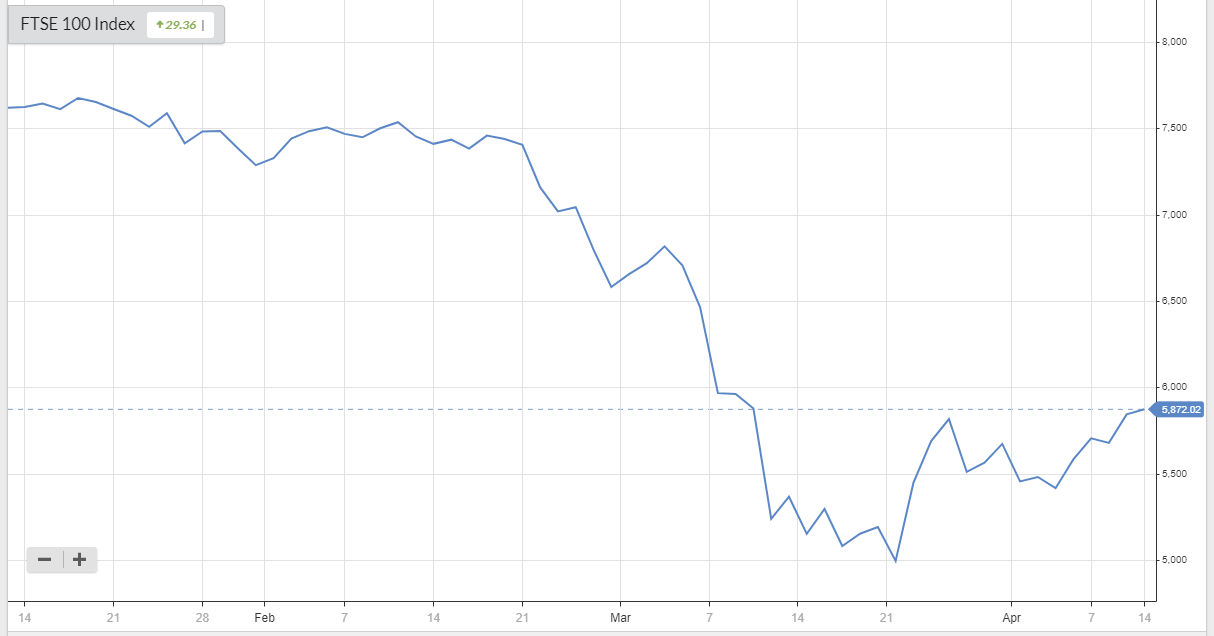
(Source:Stockopedia.)
Anecdotally, I am still seeing a lot of scepticism about these gains from commentators on Twitter and elsewhere.
As I said last week, the duration of "lockdown" measures is the most important unknown in the short-term, since many companies are closed for business until these lockdown measures are removed.
This is a truly unknowable variable - lockdown will only be ended when the combined weight of medical evidence and public opinion convinces national governments that it is feasible to make a change.
The data
I continue to check Worldometer for daily charts of coronavirus progression. The underlying data quality remains extremely poor, but these are the headline numbers which influence public opinion, so I think they're important.
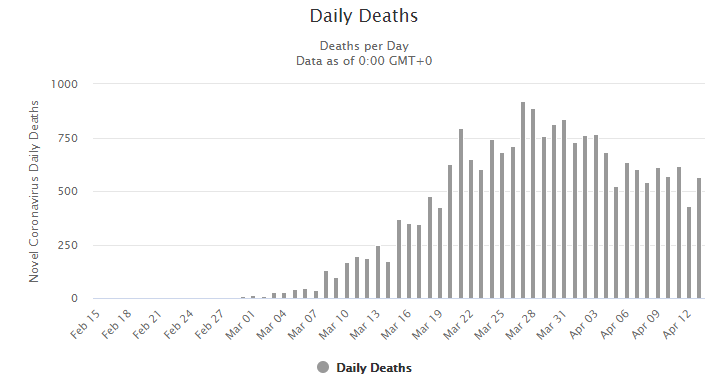
Itay has seen a steady decline in numbers dying with the virus in recent weeks:
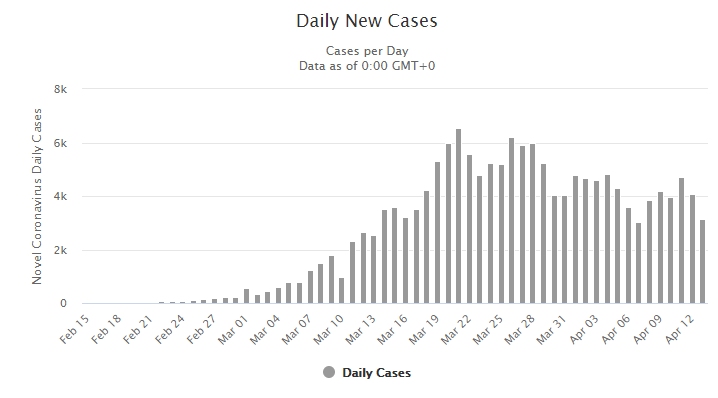
New cases are falling too:
In Italy, "bookshops, stationers and children's clothes shops" are open from today. Factories might open again on May 3rd (I expect that they will since I think the peak of the coronavirus has been seen for Italy).
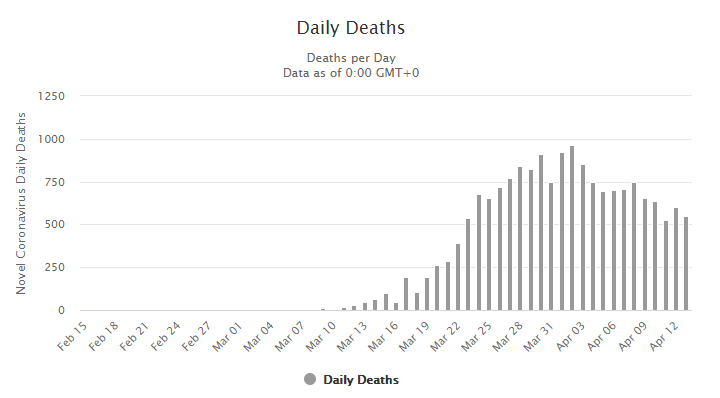
Deaths in Spain are on the decline too:
And new cases in Spain have plunged:
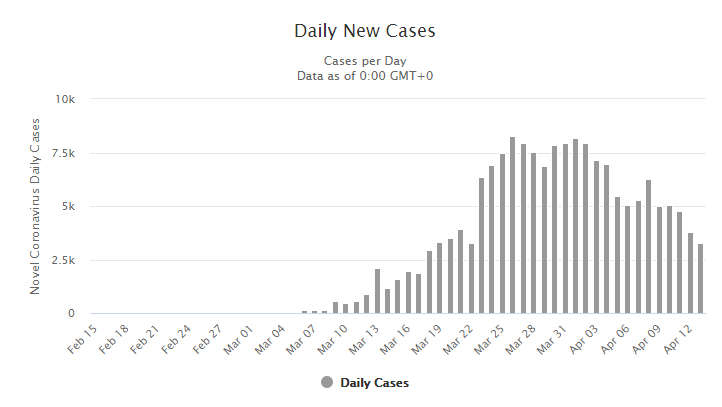
In Spain, construction and factory workers went back to work yesterday.
Elsewhere:
- Austria is reopening schools and some shops.
- Denmark is reopening primary schools and creches.
- Czech Republic has reopened hardware stores and a range of others, and is rumoured to publish its exit strategy today.
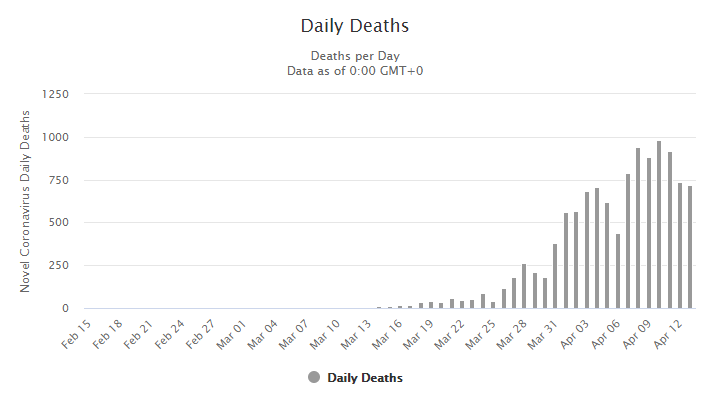
The UK figures show deaths still rising, though not at an "exponential" rate:
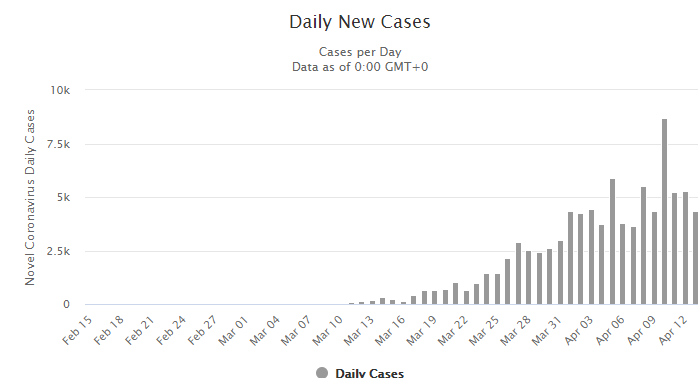
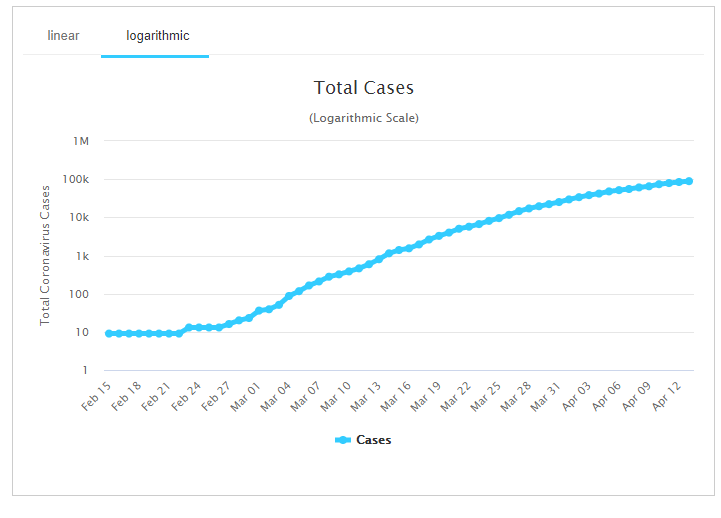
Barring the occasional daily spike, new cases in the UK suggest that exponential growth is now very weak:
We can see this on a logarithmic chart:
From where I'm sitting, the main "risk" to lockdown ending soon is that there is a lag in the process.
The process is:
- data is published, suggesting that the virus is under control.
- the public mood shifts from fear to calm, and risk aversion goes back from elevated to normal.
- governments take steps to re-open the economy, before the bill gets even bigger.
According to the CEBR, the daily lost production under lockdown is worth £2.4 billion per day, or 31% of pre-lockdown GDP.
Portfolio decisions
I can't say I believe in making a lot of investment decisions around the Covid-19 story.
We have never had a virus-induced lockdown before, and who knows when we will see one again? Maybe never?
Anything is possible, but I doubt that this will become a regular occurence.
I do believe in companies with sound balance sheets. A company with lots of cash and low fixed costs can survive pretty much any crisis. You don't have to worry about refinancing risk (which often leads to wipeout, in periods of distress).
For companies with unsound balance sheets, I would stay away whether there is virus-induced lockdown or not. If the virus doesn't ruin them, something else might.
On the other hand, if a risky company raises money to fix its balance sheet, then it might be worth a second look.
For example, I looked at Carnival (LON:CCL) after its recent refinancing, to see if I could be tempted. While I do think its equity is interesting at these levels, it is still too risky for me (I would prefer the debt).
My main point is that if you have a long-term portfolio, or are building one, you need to put this virus situation in context: for 99% of your holding period or more, the Covid-19 crisis will probably be irrelevant. Act accordingly!
In my view, all that really matters during this lean period is balance sheet survival. So long as you know that your equity position will survive, you can move on and worry about other things.
The heavy supply of RNS announcements this morning is something to behold.
Next (LON:NXT)
In big-cap land, I note that Next (LON:NXT) (in which I have a long position) has started taking online orders again, "with support from colleagues who are willing and able to safely return to work".
The UK homepage says "NO MORE ORDERS, WE'RE OPEN AGAIN TOMORROW" as of 9am. It will take orders every morning, until its warehouse staff can't take any more without breaching the social distancing rules.
I'm not under any illusion that this will generate normal revenues. At least it will keep up some degree of customer engagement.
In small-caps, we have:
- Jarvis Securities (LON:JIM)
- Cake Box Holdings (LON:CBOX)
- Fletcher King (LON:FLK)
- Revolution Bars (LON:RBG)
Jarvis Securities (LON:JIM)
- Share price: 413p (+3%)
- No. of shares: 11 million
- Market cap: £45 million
I'm familiar with this company from a customer perspective and as a former shareholder.
It owns X-O, which is the Ryanair Holdings (LON:RYA) of stockbrokers: very low, fixed-rate dealing costs and very few other costs.
The most important cost feature is the absence of percentage-based administration fees
For example, the annual SIPP fee at X-O is £99 +VAT (there are other fees for drawdowns, dealing, etc.)
At Hargreaves Lansdown (LON:HL.), by contrast, the SIPP fee is up to 0.45% (capped at £200 for a portfolio of shares).
A large portfolio of funds at Hargreaves will pay vastly more in annual administration fees than a share portfolio at X-O.
Why do people pay so much for Hargreaves? I've never been a Hargreaves customer, but I think the reasons are:
- it's a trusted name
- very slick website
- lots of information for beginners and those who need help
- a wide range of funds available
At X-O, on the other hand, you get a "bare-bones" website and are left to your own devices.
Today's RNS
This is a very reassuring letter from the CEO.
Disaster recovery planning at Jarvis has worked as intended. Service has been uninterrupted.
Some staff are in the office, "only where absolutely required" and are adhering to safe working practices.
It gets better:
At the same time, we have seen an increase in trade volumes following the election result in December and the market volatility as a consequence of COVID 19; and believe the reduction in the Bank of England base rate should have a negligible effect on interest income.
Nice!
On a personal note, I've only made one trade since the COVID-19 crisis began. That was a long trade on the FTSE, which remains open. My share portfolio hasn't been touched.
But I can see that many investors have been trading more frequently than usual over the past six weeks.
Typically this involves selling shares and then buying them back, hoping to pay less when buying back but in any event waiting for the threat of economic catastrophe to pass.
I'm sure that some investors will do this successfully. Others will find that doing nothing would have worked out better. The only guaranteed winner is the broker, who is making money in both directions.
This is a theme I frequently mention, and it's extremely important right now: the financial services firms which benefit from volatility are currently in the most perfect of conditions. This includes IG Group (LON:IGG) (in which I have long position), Plus500 (LON:PLUS), CMC Markets (LON:CMCX) and little old Jarvis Securities (LON:JIM).
Dividend - there is no change in the plan at Jarvis to pay a dividend in June.
My view
There's no change to my view on Jarvis. It's a well-run, high-quality little company.
Perhaps I shouldn't have sold my shares in it several years ago. At the time, I started to question whether such a bare-bones platform could remain competitive against disruptive new entrants in the brokerage space, such as Degiro and IG Group (LON:IGG).
Jarvis did subsequently upgrade its website and its growth has been consistent. There is evidently still room in the market for a value broker, without any of the bells and whistles.
Cake Box Holdings (LON:CBOX)
- Share price: 122p (+8%)
- No. of shares: 40 million
- Market cap: £49 million
This is a retailer of egg-free cakes (not vegan, since they do have cream). It has a big focus on personalised cakes for parties:
Egg-free cakes have wide appeal, from what I gather. You can read about the founders here.
Using the franchise system, the company earns excellent returns on capital. It makes most of its money from selling sponge and cake supplies to its franchisees, and it also charges a small franchise fee.
As such, it gets a QualityRank of 96 from Stocko.
Trading update
- like-for-like sales growth of 5.1% in franchise stores up until March 8th (pre-COVID-19).
- the rest of March was obviously not great. All of the stores closed on March 23rd.
- adjusted PBT expected for FY March 2019 of £4.1 - £4.3 million (last year: £4.0 million).
Covid-19
- CBOX helping franchisees apply for Retail, Hospitality and Leisure Grant.
- Advising and assisting franchisees with staff furloughs.
Being a franchise business, it doesn't directly face the problem of rent - its franchisees do. This is a key distinction.
The current situation appears tolerable for CBOX and its franchisees:
As a result of the above, noting that our franchise stores have relatively low levels of rent and overheads, we are very confident that our franchisees will be able to navigate this unprecedented period. The Group has very healthy stock levels and therefore is well placed to support the reopening of its franchise stores as soon as UK Government advice allows.
Balance sheet - £4 million cash balance. The only debt is a £1.6 million mortgage on properties.
CBOX expects to have monthly cash burn of £200k while franchisees are shut. That would be no big deal.
Dividend - not recommending a dividend, despite the strong balance sheet, as it would be "inappropriate" when there is so much uncertainty. That wouldn't bother me if I was a shareholder here, but views may differ.
My view
This share gets the thumbs up from me. I like what I see. Worth researching.
Fletcher King (LON:FLK)
- Share price: 33p (+12%)
- No. of shares: 9.2 million
- Market cap: £3 million
Financial health warning: this is a tiny company. Micro-cap value investors have sometimes found it to be of interest, since it can get exceptionally cheap with respect to the traditional metrics.
It's involved in the property business, doing all sorts of different things: valuations, advice, property management, fund management and direct property investment. Profits have been lumpy.
Some good news today: performance for FY April 2019 "is not currently expected to be materially affected by the current crisis".
But looking ahead, it sees the risk of a "severe and prolonged" economic impact from the COVID-19 crisis:
In this scenario, transaction-based fees such as investment deals and bank valuations are likely to be materially lower than would otherwise be expected.
The progress of rating appeals is also likely to be further delayed.
Property management activity (which is a core service of the Company) is not expected to be affected to the same extent, although fees may come under pressure should there be a significant decline in the collectability of rents from tenants in client properties (the Property Management team has been successful in collecting 85% of rents for the March quarter by the due date, compared with normal achievement of 99%).
FLK is too small for most people to invest in - I mention it because of the read-across to other property-related shares.
It's not easy to be bullish on commercial property in the current environment - it feels like the work-from-home and buy-online trends are speeding up.
Revolution Bars (LON:RBG)
- Share price: 19.01p (+23.5%)
- No. of shares: 50 million
- Market cap: £9.5 million
COVID-19 and Banking Facilities update
The lockdowns are a disastrous scenario for all sorts of businesses, but particularly for bars and pubs.
RBG shares had already dropped to around 20p as of mid-March, when it gave its first virus update.
At the time, I noted that RBG was "proactively exploring all the options" with respect to its funding requirements.
Having net debt of over £10 million, I reckoned that the company would need a major refinancing (unless the lockdown ended very quickly).
Today's RNS
The bad news is that net debt has ballooned to £17.8 million, almost twice the current market cap.
Its existing bank debt facility was set to reduce to just £18 million (from £21 million) at the end of June. If net debt is £17.8 million, then gross debt is £18 million+.
The good news is that Natwest is not pulling the plug:
...subject to final documentation, Natwest has agreed to increase the Facility to £30.0m until 31 August 2020, following which it will step down to £24.0m as the Group begins to benefit from its normal positive working capital cycle following an assumed recommencement of trade in July 2020. Natwest has also agreed to waive all financial covenant tests at March and June.
The lifeline should last until September, around which time Natwest will review "both the amount of available facility and the covenant tests applicable".
Debt load
Weekly running costs are said to be £0.4 million, i.e. £1.7 million per month.
At that rate, another 2.5 months of lockdown to the end of June would burn through £4.3 million and take the net debt level to £22 million.
The gross debt level will be higher again, so RBG will need to benefit from that "positive working capital cycle" it references above, and start generating some operating cash flow in July and August.
As a reminder, it will only be able to borrow £24 million in total from the end of August.
My view
It won't come as a surprise that I remain extremely cautious when it comes to these shares. The level of debt doesn't look very comfortable, and it therefore makes sense that management are still monitoring "the Group's funding requirements and all options available to it".
According to Paul's previous notes, RBG was looking to make £12.3 million in adjusted EBITDA this year, and pay down £5 - £6 million in debt.
If the turnaround plans succeed, post-lockdown, then maybe the debt load could be managed lower over the subsequent four years, say?
If you are very patient, and happy to wait for this thesis to play out, then you are more patient than I am.
I could be wrong, but even in a bullish scenario, I don't see this company having the capacity to pay dividends for the next several years. Cash flow will have to be devoted to debt reduction, a debt load that gets bigger every week the sites are closed.
Most of RBG's "enterprise value" is, appropriately enough, tied up in the debt held by Natwest.
And when the sites eventually re-open, we should be cautious about what the recovery might look like. Many people will be repairing their personal balance sheets, instead of going out for drinks. It could be a slow rebound.
Therefore, if it is possible to raise equity, I think RBG should try to do that now. If it can't or chooses not to, then existing ordinary shares are a bet on:
- a fairly quick rebound in consumer spending, after trading restarts by July, so that debt reduction can begin.
- Natwest being relaxed and happy in September.
These things could happen, and RBG shares could multi-bag from here.
But I agree with the market's current pricing of the shares: if these things don't happen, then RBG shares probably won't be worth anything.
If I was Stonegate, and I still wanted to own Revolution, what would I do? Having previously bid £101 million for the business, I could:
- Offer a premium to the existing market cap (£10 million), and take on £18 million of net debt. Enterprise value £30 million+.
- Put the feelers out at Natwest over the next few months, and check if they would like to sell their position.
I know that I'd look at the second option, before I even considered the first option.
As I said last time, I don't see RBG shareholders coming out of this situation any better than their landlords, the bank and the tax man.
I think they should raise equity and start again, if they can.
Calling it a day there, thanks everyone. Paul is back tomorrow.
Cheers
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

54 comments
Anyone invested in Hiscox (LON:HSX) might like to check out the BI wording on their SME property insurance.
many thanks for pointing this out.
On The Beach (LON:OTB) - business model. I remember wading through the admission document a good while back and discovering that Ryanair had initiated legal action against the company. My reading was that the success of OTB's business model was subject to a favourable outcome.
More detail can be found in the admission document here https://www.onthebeachgroupplc.com/~/media/Files/O/On-The-Beach/investor-docs/results-and-presentations/prospectus.pdf - section 13 , page 184.
It put me off investing and I have no idea how or whether this got resolved.
Yes good point on On The Beach (LON:OTB) & Ryanair, id forgotten about Ryanair not being happy other companies sell their flights & if OTB can’t it breaks the bus model.
I don't think resolved & i dont see Ryanair backing off now.
"I don't know what his chances are of getting away with it, but I'm sure there will be a lot of other cowboys trying something similar."
I, for one, hope "they throw the book at him".
on Avation (LON:AVAP) which is frequently commented on here. Note that Virgin Australia, its joint largest customer in terms of revenues, looks in some difficulty, with its shares suspended today and its bonds reportedly (according to the Guardian) trading at 39 cents in the dollar.
https://www.theguardian.com/bu...
On the Beach has said that travel companies may have to radically rethink their business models after the coronavirus crisis abates. OTB suggests that customer money should be ringfenced and not used to meet day-to-day running costs. The whole sector on this basis will have to be revalued given the deterioration in their cash position under this new schematic. Who would touch travel companies at the moment?
On the Beach has said that travel companies may have to radically rethink their business models after the coronavirus crisis abates. OTB suggests that customer money should be ringfenced and not used to meet day-to-day running costs
Hi Camtab
I haven't seen that they've suggested this, although their latest trading update pointed out the benefits to their customers. In fact I think something like this is inevitable. This is a bit technical but let me try and explain - if nothing else, it's a primer on payment companies!
If I pay online for something using a card I have protected rights either because of law (section 75 which only applies to credit cards) and payment scheme rules (chargeback rights). These rights mean that under most circumstances if I pay for something and don't receive it and the merchant doesn't refund me I can claim the money back via my bank - who then pursues the merchant (via the payment schemes, but let's ignore that).
If I buy a holiday then normally I put down a deposit. If, for some reason, I'm prevented from taking that holiday because the travel company won't let me go (for instance, if the government locks everyone down because of a pandemic) then I can ask for my money back. Unfortunately if everyone does this at the same time that's a problem because most travel companies will have spent the deposit money already, using it as working capital.
If there are enough claims then the travel company goes out of business - but anyone who hasn't got their money back can now go to their bank. The bank contacts the payment scheme (Visa or Mastercard mainly) and the scheme contacts the travel company's payment processor (technically known as an acquirer) who is responsible for standing in for the merchant in this situation. There are (say) 100 acquirers in Europe covering all of the merchants.
Now imagine that every travel company in Europe has the same problem simultaneously and they all go bust. Those 100 acquirers are now responsible for all of the unpaid refunds. Unsurprisingly they'll go bust if they have to pay and the entire card payments network will collapse. Clearly this won't happen - there'll be bailouts and other fixes. However, the issue has shown the acquirers that they have a massive risk problem and they will either be refusing to serve travel companies in future or demanding massive up-front fees.
This radically messes up the economics of the travel industry who will now have to find other ways of allowing customers to pay for things while not exposing them to more risk. The On The Beach (LON:OTB) model solves this and does so from a relative position of strength. Other travel companies have got to deal with their overhang of debts while suddenly losing the ability to use deposits for working capital. If I were running holiday flights or hotels I'd be looking very favourably on an agent that doesn't have any of those problems.
After 9/11 it took three years for flight volumes to recover and I'd expect the same here but if you've got the patience and want to invest in the travel industry then I think On The Beach (LON:OTB) is probably the way to do it.
timarr
Revolution Bars (LON:RBG) AND J D Wetherspoon (LON:JDW)
Nebraska1977
Paul, I agree with you. The debt levels of Revolution Bars (LON:RBG) are actually very low, rising to around 2x EBITDA (trailing) at end-June 2020 assuming bars stay closed until then. Compare that with other pub/bar groups and it looks very healthy: J D Wetherspoon (LON:JDW) was at over 3x before this crisis and will be now looking at 4-5x very soon. So, NatWest who is clearly being supportive aren’t going to force an equity issuance on Revolution, as if they did that they’d have to do it on the entire pubs/bars sector. Graham’s point on market cap versus debt is meaningless in my view, that is low because equity value is so low (i.e, cheap) and doesn’t reflect the debt/cash flow reality of the business.
That's a very apples and pears comparison IMHO - J D Wetherspoon (LON:JDW) own freeholds on approximately 50% of their outlets so they have much more flexibility with regard to playing with debt levels than Revolution Bars (LON:RBG) where i am pretty sure its all leasehold. Note last year alone J D Wetherspoon (LON:JDW) spent £70 mill buying back freeholds - this certainly pushes up debt short (or even long) term but they have the tangible sellable asets on the balance sheet to compensate - so not really a meaningful LFL comaprison here.
Fair enough and good point. The comparison to Wetherspoon’s isn’t the key point I am making, rather it is that 2x historic EBITDA net debt levels at end-June 2020 is low compared to where most other retail businesses will be and its cash burn rate is manageable. Assuming the lockdown ends at some point in H2 this will be an attractive entry point in my view as company can trade through until then and 6x EV/EBITDA feels more realistic for this business (about a 5-bagger for equity) which was performing well up until Covid.
Needless to say, I completely disagree with Graham over Revolution Bars (LON:RBG) , but that's fine, we like discussion of bull & bear cases here!
The way I see it, last week RBG shares were priced as little more than an option on the company possibly surviving. The share price suggested that heavy dilution of existing shareholders was highly likely. Today's announcement is game-changing, in that the bank is providing the necessary additional support (Nat West, part of RBS - Govt owned & apparently the major bank to be supporting businesses actively at the moment, according to recent press reports - so it's worth checking other distressed companies to see if they bank with RBS - if so, maybe their survival chances are better than others?)
What's changed today? The risk of heavy dilution has gone, for the time being. I'm really impressed with the extent of Nat West's support. When I last saw RBG mgt, I asked about the relationship with their bank, and mgt replied that it's really good, now that the LFLs had turned positive, and refurbs were generating strong ROI. So the bank definitely believe in the business, more than they would have done pre-turnaround.
Obviously CV19 has changed everything in the short term. We know all of that & it's why the share price has collapsed. Think of it this way, with improved trading announced earlier this year, the share price would probably have been around 100p by now. CV19 has taken that down to 20p. Hence I see opportunity, now that we know the bank is supportive. I'm not saying it should instantly re-rate to 100p, but with a (say) 1-year view, and assuming trading can resume in July, and be uninterrupted thereafter, then it's easy to see 100p becoming the recovery level. That's a 5-bagger - terrific risk:reward, in my view. Hence why I've backed up the truck this morning & quadrupled my stake, which is close to 3% now.
Another reason why the share price so low, is that Keith Ashworth-Lord has been dumping in the market - I bought 2 clips of 250k shares from him this morning, plus market purchases too. He's still got about 13% I think, so that provides anyone who sees opportunity more than risk, to fill your boots if you want to. Obviously, that's entirely up to each individual, I'm only giving my personal opinion here, not recommending anything, as always.
Re-negotiating the deal to dump nearly all the loss-making sites is also very canny of management.
Looking at strong upward price moves in many companies at the moment, I think the market is starting to price in a return to normal trading, i.e. gradual, and perhaps staggered lifting of lockdown. For example, why on earth are building sites shut down? That seems ridiculous to me, when the danger (statistically minuscule to healthy people under 65 working outdoors) is more for confined spaces with lots of people in them (like bars, I hear you cry).
In my view, once restrictions are lifted, the 18-25 year old core customers of RBG are likely to want to party like its 1999, not continue to hide away from CV19, so in the upside scenario we could see very strong LFL sales uplifts at RBG once it is allowed to start trading again. Maybe.
Downside risk is that CV19 cases flare up again, and new restrictions are imposed. That could prove terminal, or require an emergency placing, as Graham says. Hence the risk bit in risk:reward.
Obviously I'm talking my own book here, and seeing the potential from the upside case. This is a nicely cash generative business in normal times, especially now the expansion capex has been put on hold until 2021 - which might have to be pushed out to 2022 now.
I don't think shareholders are bothered about dividends. The upside case here is a 5-bagger on the share price, so I'm happy to forget divis in that scenario.
Re the net debt that Graham mentions, the company mentioned that net debt at 31 Dec 2019 was a seasonal low, in their words - we've collected in all the Xmas sales, but not paid the bills yet. So there's no surprise in the net debt movements to date. In fact I think it's quite encouraging, and could have read-across to other hospitality & retail sectors, that cash burn can be reduced to a very low level. Cash burn of £0.4m per week is much lower than I was expecting actually.
There are obviously a range of potential outcomes here, the worst ones could be a total wipe-out, or heavy dilution. But you could say that about many other big name retail/hospitality companies at the moment.
It's all about great management coming to the fore in a time of crisis, which I think today's RNS makes clear that the CEO & CFO at RBG (who are hands-on operators), seem very much on the case & dealing with it exceptionally well.
Let's see what happens, but for people like me who are risk tolerant, then this could be very good from this level. I'm surprised it's not up more actually today.
Regards, Paul.
Paul, I agree with you. The debt levels of Revolution Bars (LON:RBG) are actually very low, rising to around 2x EBITDA (trailing) at end-June 2020 assuming bars stay closed until then. Compare that with other pub/bar groups and it looks very healthy: J D Wetherspoon (LON:JDW) was at over 3x before this crisis and will be now looking at 4-5x very soon. So, NatWest who is clearly being supportive aren’t going to force an equity issuance on Revolution, as if they did that they’d have to do it on the entire pubs/bars sector. Graham’s point on market cap versus debt is meaningless in my view, that is low because equity value is so low (i.e, cheap) and doesn’t reflect the debt/cash flow reality of the business.
When we move into releasing the lockdown it is going to be Revolution customers (aged 18-25) who are out first and they are going to be hitting the bars as they feel invincible against this virus (backed up by the stats). That will quickly push Revolution into being cash generating versus the weekly cash outflow of £0.4m. If that happens then this is definitely multi-bagger territory. Risk reward very favorable at these levels.
Hi Nebraska1977,
We cannot compare debt levels at Revolution Bars (LON:RBG) and J D Wetherspoon (LON:JDW) because RBG operates entirely from leased sites, whereas JDW has quite a lot of freeholds. Or if you did want to compare that, you would need to use the IFRS 16 debt figures for RBG, which goes some way to make them more comparable, arguably.
Overall though, I do agree that RBG's debt levels are not high at all, and I find it perplexing why so many people seem to think debt is a problem, when it really isn't (or at least it won't be once normal trading has resumed).
Some time ago I looked back at the balance sheet of Luminar, a night club operator which went bust in the 2008 recession, and it was off the scale compared with RBG's balance sheet debt, hence why it went bust.
Regards, Paul.
Thank you Paul (and Graham) for your respective commentaries on Revolution Bars (LON:RBG)
I bought back into Revolution Bars (LON:RBG) over the last few weeks with the anticipation that the sell off was too deep and, like you Paul, that this could be a potential 5-bagger at the very least over just a couple of years.
Having said that, I was quite disappointed with today's update.
I would much rather have preferred a massive placing to ensure funds were available well into 2021. Instead, bank facilities have been extended that guarantee survival until maybe August 2020, which is not very far away at all.
What if things are not back to normal until say October/November? Why risk having debt facilities so low?
Further, I don't understand having a facility up to £30m if it has to be £24m by the end of August. Assuming a maximum of £6m can be paid back per year, that leaves a 4 year debt repayment period (at least) from the debt that will be on the books come August 2020.
It's only a small position for now, so I will hold, but sadly, I think the company has chosen the wrong financing option.
A
Thanks Paul, insightful as always. I have been following RBG for some time and have always agreed with your analysis. Also your commentary on the management team has been invaluable given this is insight I rarely get despite how critical it is. One quick question though on your comments below:
"Another reason why the share price so low, is that Keith Ashworth-Lord has been dumping in the market - I bought 2 clips of 250k shares from him this morning, plus market purchases too. He's still got about 13% I think, so that provides anyone who sees opportunity more than risk, to fill your boots if you want to"
What do you meant by purchasing clips and how do you go about purchasing directly? Sorry for my naivety however it is a phrase I haven't heard before and interest to know whether there is beneficial pricing when buying in large chunks?
Thanks again.
Regards, Claudia
As a trader, I want to see strength in the price action, and today has confirmed that. The low was just under 17p and it uncrossed at 21.9p. Big volume too, and an RNS shows Castlefield has exited completely. I'm bullish and will be getting in the auction tomorrow morning.
Apologies for this delayed addition. Re Fletcher King (LON:FLK) again, I thought it was relevant that the management here said "whilst there is huge uncertainty caused by the COVID-19 virus, it seems increasingly likely that the wider economic impact will be severe and prolonged." They have been about a while, and know their markets.
Si, re Boohoo (LON:BOO) - did you see this article in The Guardian last week?
https://www.theguardian.com/business/2020/apr/03/why-are-people-buying-boob-tubes-fashion-workers-anger-at-owners-and-consumers
Sounds like they're busy.
Si, re Boohoo (LON:BOO) - did you see this article in The Guardian last week?
No I didn't, but it's all a bit circumstantial tbh and the lack of social distancing within the warehouse sounds like a serious problem - what they don't need is a Next (LON:NXT) style walkout by warehouse workers. If that article contributed to the sharp increase then I'm happy to have taken some money off the table. Call me old fashioned but I'm happy to buy back at a higher price once the picture is clearer.
All the best, Si
Regarding Fletcher King (LON:FLK) , in which I have a tiny holding, please ignore the rise in share price shown on the boards. I could buy at no less than 33p for all of last week, and can still do so now. On the negative side the spread is ridiculous, at about 30%, and it is about as liquid as a tin of Golden Syrup at zero kelvin. But there is no debt, the directors hold a fair old chunk and consequently treat shareholders well, and the company has a long list of established clients who return regularly. Best of all, the company buys the occasional office building, renovates it and fills it with tenants, then sells it on as a going rental concern. The result is an occasional special dividend. The last ones were in 2010 and 2015. Such a project (SHIP) is currently in the undertaking. Fundamentally this is a play on central London property, so is not for everyone.
Hi Graham -
On a lighter side, today's RNS by £BAR says this:
"We have noted differences in sales patterns across different product types. Sale volumes of handcare products have increased significantly and we have been able to secure extra supply to support retailer demand whereas, for example, sales of male haircare and shaving products have, unsurprisingly, declined significantly in recent weeks."
Yep. We are a scruffy lot at the slightest excuse.
Thanks for that Ramridge! :)
G
Thanks Si - now I'm worried again :-(
Thanks Si - now I'm worried again :-(
With regard to Boohoo (LON:BOO)... yes, each day that passes without a RNS from them my worry level increases further, so much so I dumped half my holding at the end of last week, not something I expected to do as I'm generally happy to hold on-line businesses with very strong balance sheets, but it seemed any bad news was being totally discounted.
I was also hit by the statement by Lord Wolfson in the Next (LON:NXT) results to the effect that "no-one buys a new dress when they're not allowed to leave the house". This seems a pretty accurate statement tbh.
All the best, Si
I used to think that but young (for me that is under 30) people really do think differently.
If you were not out with friends one night but texted a lot to that group, I think they would say you were 'there'
With the rise of instagram and tiktok and zoom I suspect you can go out without going out if you are below a certain age.
As such, if I held Boohoo (LON:BOO), I would not be too depressed until the facts change.
I used to think that but young (for me that is under 30) people really do think differently.
I have always asked my four nieces in this regard to try and keep up with what they and their friends are doing. I can confirm that as of last week when I last spoke to them, none had been buying clothes while locked down. Of course, this is all very circumstantial, and none of them are Boohoo customers AFAIK...
As such, if I held Boohoo (LON:BOO), I would not be too depressed until the facts change.
I agree, and normally would do so, however on a PER >40, if the facts change so (very quickly) will the Boohoo (LON:BOO) share price. I am happy to be proven wrong if they are maintaining (or exceeding) growth in the current environment. But as I said, my main concern is on the supply side with regard to my remaining half-sized holding.
All the best, Si
Yes it's possible that Boohoo (LON:BOO) has seen business boosted by the lockdown, as High St shopping has gone but people want to buy new clothes. Don't think Lord Wolfson was thinking of the average BOO customer demographic when making his point.
On the social media your new outfit will be noted by the others in the group and you will be the centre of attention.
An earlier poster made comment as to no update from BOO..not surprising as the results are I believe on the 22nd April.
The negative in the results may be pressure on disposable income.
An interesting conundrum.
Re Next (LON:NXT) - has been forced to suspend orders on its online store within hours of re-opening after it was inundated by shoppers.
Next resumed trading on Tuesday but many customers visiting the site will be left disappointed. The retailer appeared to have been quickly overwhelmed by demand and had already hit its reduced sales capacity by 9am in London.
I had been a bit worried about the over enthusiastic recent climb in the share price of Boohoo (LON:BOO) (big holding for me) - but this news from Next (LON:NXT) seems to show that the demand for online clothing is definitely there.
I had been a bit worried about the over enthusiastic recent climb in the share price of Boohoo (LON:BOO) (big holding for me) - but this news from Next (LON:NXT) seems to show that the demand for online clothing is definitely there.
I think the main issue with Boohoo (LON:BOO) could be one of supply as much as demand - how are the manufacturing sites in India doing under lockdown? You have to remember the whole business model is not to hold too much stock for most of their lines and to turnover stock quickly. Most other companies have updated on the COVID-19 situation and my concern is that Boohoo (LON:BOO) is the dog that hasn't barked.
Also the Next (LON:NXT) statement says:
Initially only categories that our customers most need will be offered, such as Childrenswear and selected smallHome items
So there doesn't seem much read across to Boohoo (LON:BOO).
All the best, Si
Next have RNS'd they would be opening online in a limited fashion. Given they seem to be a top quality operation, I imagine they plan to up throughput once they have proved to themselves and to USDAW (per The Times article yesterday) that they can operate and keep to the social distancing rules.
Some other retailers, e.g. Crew and Amazon, have continued operating online without any hiatus, so I suspect some other retailers have been more cautious than the law requires.
On my 5 mile trip to get the morning paper, noticeable that 2 building sites (1 of about 50 houses and 1 of about 10 houses) are up and running again. Also building work (extensions, roofing etc.) on several houses also restarted. All of these after having been shut up for the past few weeks.
Might just be very localised or could be a more general trend.
Also building work (extensions, roofing etc.) on several houses also restarted. All of these after having been shut up for the past few weeks ... Might just be very localised or could be a more general trend.
Building sites haven't been asked to close as long as they can maintain social distancing - difficult, I'd imagine, but possible if done carefully:
http://www.constructionleaders...
There's been some confusion around the rules, but I'd expect to see sites reopening where it's safe to do so.
timarr
I have just been out shopping today and I also noticed so many builders working, last week I did not see many but today seems every site has men back working, these are all small works.
The other day I was told of a local painter & decorator who is forcing his handful of workers to attend jobs as normal, while simultaneously claiming furlough for them - in an attempt to 'double his money'.
I don't know what his chances are of getting away with it, but I'm sure there will be a lot of other cowboys trying something similar.
With such big govt subsidy schemes in play, if fraud does not happen on a significant scale by many different routes I will be astounded ! I hope the govt creates some extra jobs in the tax dept to catch them but prosecuting desperate SME business owners is bad politics; a few badly handled investigations lead to bad headlines: easier to let the bad eggs skim money.
Big business by contrast will typically 'play by the rules' but have skilled professionals to help them game those rules.
This is the whole problem with repeated promises by govt to clamp down on tax avoidance and similar schemes !!
Huge volatility all over, some holdings up 10%, some down 10% - seems to me so much automated momentum trading here.
Goldmans: US stocks past the worst.
Mark Mobius
“I don’t think we’re at the absolute bottom yet because the implications of this shutdown are incredible,” Mark Mobius, the founding partner of Mobius Capital Partners, said. He added that “things are pretty bad” from the perspective of corporate earnings.
CNN : China is giving cash to car buyers to revive sales crushed by the pandemic.
The S&P500 is now 10% below the Dec 2019 price. So terrible earnings for this year, massive debt taken on by many companies, massive job losses - is the future that bright?
Hard to sit tight though, but I remind myself we are at the start of this process & I keep getting the desire to buy, and have bought some, as this is easy right, every share going back to its pre-crash level, easy money. Too easy I think.
today I bottled it and sold most of my portfolio
I have two conflicting thoughts, one says the lockdowns are starting to finish and inflation is going to reduce cash value so stay in, the other says I dont trust this rally, many stocks are back to oct/nov 2019 prices which is crazy
I dont understand what is going on, it makes no sence to me. So for me to stay in the market is just gambling, for the sake of money preservation I sold out brought gold and will return when things become more familar and measureable
If you have invested in good businesses with a good track record and strong balance sheets it is not a gamble. You may find you have sold close to the bottom - doesn’t seem to me to be a sound approach especiialy as a number of countries seem to be over the worst
Buying Gold isn't leaving the market, it's just being in a different market. How would you feel if Gold fell 20% about your decision?
Hi Ambrosia,
Is your portfolio everything you own in the market, ie your pension/isa/investments, or your directly controlled share portfolio?
Too often, and i am not saying this is you, people say ‘i’m 100% cash’ - yes for your 20k share portfoliio but not for your pension & isa’s with legal and general ....which are still 100% in equities, and as such, just not true.
"I have two conflicting thoughts, one says the lockdowns are starting to finish and inflation is going to reduce cash value so stay in, the other says I dont trust this rally, many stocks are back to oct/nov 2019 prices which is crazy"
It's quite possible both observations can co-exist.
Yes, the money printing will eventually reduce the value of cash, inflation maybe. Fixed-rate investments will suffer, like bonds or ex-growth 'safe' stocks like the traditional high yield favourites. But, growth stocks would be bid to the moon. Don't forget how much money there is in the world desperately seeking growth.
I view holding growth stocks as fairly safe, in the scheme of things, versus holding financials, insurance, cyclicals which I think are risky in a monetary repression environment although their names and large cap status make them appear 'safe'.
Gold is a good idea. The irrelevance western governments have towards our savings now is extraordinary.
Some huge rallies today in small cap stocks. Back in Revolution Bars myself at below 18p after the update today so looking forward to comments on this one. Did very well on this when it had an offer at 200p ......which the shareholders then bizarrely rejected. A lot of business here for this tiny market cap. At the lows of 13p it was just £7 million. Very risky of course with the bars closed but if you think the lockdown will start to end in mid May and bars and restaurants will open again then this bombed out sector is one to consider imo. If we get to Xmas and the virus has mainly gone or there is an effective drug, then I see a lot more office parties than normal as people celebrate in style. AA. is also moving up strongly today....I think again anticipating a mid May end.
Re £RGB Also been thinking thinking about seasonality. Its key profit earning periods are run up to and including Xmas/New Year (plus Fresher's, Halloween, other Public Holiday weekends) although I disagree and think the net "incremental post lockdown party effect will be weak by Nov). So if we do get re-openings by start June but with limitations (eg headcount limits on numbers inside bars, Mon/Weds closure the norm), many of the best Fri/Sat nights will still be there. Thus, they may do better than expected (ie still very very bad, just less bad !!) over 6-12 month period and at the very least will survive at which point they will seem cheap based on historic cashflow. This will be especially true if lots of independent clubs do not get the same financial cover and go under and before they have time to be relaunched. (Obviously how much cash the target market will have to spend post summer is a critical unknown.)
What’s more £RGB claim in today’s RNS that cash burn is reduced £0.4Mn/mnth but they have put an extra £6Mn finance facility in place – so presumably can go at least another year. Amazingly, they also claim “completion payments (to re-set / give problem leases agreed only in Jan 20) have been reduced from £3.64m to £2.25m” and cash payments deferred. To me this shows 1) the CEO/CFO are on top of things and earning their corn and ii) that landlords must be desperate!
Other companies have even more pronounced seasonality (eg Portmeirion (LON:PMP) )and may be worth modelling for this effect. (Disc. Own both RGB and PMP)
Revolution Bars (LON:RBG)
Slight correction. Cash burn is now £0.4m per week
Big correction: x4 error when thinking about survival time, my no 1 concern. Thx.
Thanks to Graham for his very fair comments on RBG. It confirms it sure is a risky punt! I do wonder if Stonegate will come back at say 40p to 50p having previous offered 200p. I for one would take that!
A couple of thoughts. Will this become a regular occurrence? Regular may be pushing it, but the Asian Flu and Hong Kong Flue epidemics in the late 50s and 60s killed 2m and 1m worldwide. So that's 3 pandemics in 60 years (ignoring SARS). Had we had the testing and monitoring that we do now I have no doubt the previous episodes would have caused shutdowns. So this is a risk that perhaps we had not fully factored in before, that perhaps every 10-30 years the economy gets shut down for a quarter.
Secondly, the global economy was looking very weak before the virus hit. UK growth was 0.1% and US growth and inflation were both slowing (in what Hedgeye call quad 4). So any sort of bounce back seems partially to rest upon the idea that things will be better coming out of lockdown than they were going into it. That seems hugely optimistic imo.
What we have seen is a huge amount of money being printed and pumped into the system. How effectively it is being used is open to debate: I suspect a lot of zombie companies will be propped up causing long term damage to the growth prospects of the economy. Nobody has any idea what corporate profits will look like from here. Bonds are hugely expensive. In that environment, it is hard to look much beyond gold imo.
Revolution Bars (LON:RBG) City AM article ...
Revolution Bars shares jump on coronavirus debt facility extension http://dlvr.it/RTkq02
The world will find a way to co-exist with the Covid19 -what other choice is there? China, notably, started a careful return to industrial production (I recall) in late January. My guess is that their government, started into the economic abyss and didn't backed off from complete eradication of Covid19.
In Europe, some countries are already slowly loosening the lock-down arrangements. Meanwhile, in a country which seemed to have managed their crisis very well, Sinapore, there is a fresh wave of Coronavirus cases.
Hopefully at some point soon there will be a vaccine or effective anti-viral medicine. Meanwhile, though, I'd expect to see a partial lifting of lock-down followed by periodic localised lock downs when fresh clusters flare up.
I read that the virus transmits by extended, indoors contact with infections individuals within a metre's distance. (The 2M social separation rule is a margin of safety).
So the activities least likely to resume normally are things like flying, cruises, public transport, cinemas, bars, restaurants and indoors entertainment. Maybe those big cinema complexes could reopen with groups spaces out a lot? Maybe cafes and restaurants could change to have far fewer customers at any one time? Hand sanitizers mandatory on entrance.
Is there any reason why normal retail, construction and other industrial production cannot restart soon? OK, with shops you'd have to control numbers inside at any one time.
Landlords of retail property might have to accept their property in future can fundamentally accommodate fewer paying customers. So rents are permanently lower, and accordingly a building's valuation.
I guess some investors might multi-bag on companies like cineworld if it survives, and do very well on say Dart. But would that be good judgement or just good luck? I'm inclined to totally avoid any consumer facing business or property company where consumers gather inside, and focus on other sectors instead. Even a strong balance sheet cannot ultimately rescue any business without customers.
"From where I'm sitting, the main "risk" to lockdown ending soon is that there is a lag in the process."
In the short term, the risk to our portfolios comes from other investors' reaction to what happens.
The UK focused small cap market might drop sharply if there is a second surge in cases in countries where the lockdown is relaxed, because it would seem likely that the UK would decide to be more cautious as a result. The Government is getting criticised for not taking enough notice of what happened in the other countries where the epidemic is further advanced than in the UK. They are likely to be reluctant to be seen to make the same misteke again.
I had built a cash position of 25% before the crisis reasoning that things were becoming fairly heated. I used some of that money to buy lower down and I cannot see any reason not to start raising cash again. In particular as the World Bank sees a deep recession on the horizon. That said I think in times of change the money is in new ideas and ways to solve problems not in how have i made money in the past.
My morning smallcap tweet: Part 2/2
Iofina (LON:IOF) Steppe Cement (LON:STCM) Hyve (LON:HYVE) Proteome Sciences (LON:PRM) IXICO (LON:IXI)
Iofina (IOF) iodine plant IO#8 completed and is in production. Q1 production down 3%, plants remain fully operational. Some slowdown in shipments, particularly to and from India. Iodine price stable. Progress on IofinaEX, and the hemp industry in general, has slowed. CBD market has continued to decline. Co "confident that a debt solution will be realised ahead of the repayment date of the Company's current debt package on 1 July 2020."
Steppe Cement (STCM) Q1 production down 10% and mkt share fell to 13.3% (17.4%) as the Company decided to maintain pricing over volumes. Kazakhstan's cement market demand will decrease duw to covid and low oil price. Co does not expect any liquidity problems.
Hyve Group (HYVE) re press speculation: options under review include a potential equity fundraise.
Proteome Sciences (PRM) FY19 rev up 54%, pretax £0.15m (-£1.31m). Q1 rev broadly unaffected by COVID. Currently no issues with supply chains or staffing levels. Lockdown could impact production and delivery of samples and critical reagents but does not expect this to have a material effect on FY rev.
Ixico (IXI) wins £10.5m contract over 4 years, mostly in 23-24. Guides H1 rev at least 25% up. £6.7m net cash. Clinical trials affected by covid but co "has a significant backlog of image analysis and other revenue generating project requirements for short-term completion and delivery." Co well-placed for impacts of COVID.
My morning smallcap tweet: Part 1/2
£DOTD Mycelx Technologies (LON:MYX) Circle Property (LON:CRC) Brand Architekts (LON:BAR) Cake Box Holdings (LON:CBOX) Bagir (LON:BAGR) New Trend Lifestyle (LON:NTLG) Lamprell (LON:LAM) Checkit (LON:CKT) Revolution Bars (LON:RBG) SIMEC Atlantis Energy (LON:SAE) Nakama (LON:NAK) Fletcher King (LON:FLK)
dotdigital (DOTD) guides FY (July) slight softening of revenue but earnings in line with mkt exp. Impact of prolonged COVID lock down harder to forecast. Co has has 90% recurring revenues, (of which 90% is contracted). Net cash £22m end March. "Stress test modelling gives a high level of confidence that we could, if required, maintain our business model through a prolonged global downturn."
MyCelx (MYX) market conditions have deteriorated further. CO remains operational. Has applied for US Small Business Administration's Payroll Protection Program. Withdraws guidance. $7m cash at at hand.
Circle Property (CRC) NAV 290p up 5% in year. Q rent payment: 70% paid plus 9% expected before end April. Some paying tenants monthly now. No retail property. Has £6.68m liquidity available. Cutting costs. Will pay final div but delays payment.
Brand Architekts (BAR) handcare products strong but a number of international General Merchandise and Department Stores have shut, hitting sales.Online sales strong. Passes div. No guidance.
Cake Box (CBOX) sales to 8 March strong but franchise stores now closed. Guides FY(MArch) rev up 10%. Adj pretax £4.1 - 4.3m (£4m). Co "very confident that our franchisees will be able to navigate this unprecedented period.". £4m cash at hand. No FY21 guidance.
Bagir Group (BAGR) applies for a a temporary stay of proceedings against the Company. A trustee will assess "feasibility of maintaining the Group's business and assets and/or the optimal manner of their realization."
New Trend Lifestyle Group (NTLG) the Singapore-based Feng Shui tinpot says FY19 rev virtually unchanged. Q1 broadly in line YoY. COVID-19 has not had a material effect. Singapore closed non-essential businesses closed from 7 April. Gov stimulus may help.
Lamprell (LAM) cutting costs, working from only one yard. Net cash $77m of which $35m restricted. Asking to delay strategic capital expenditure in the Saudi maritime yard. Signs of deceleration and delays in some contracts. 2019 backlog $470m with ~$275m scheduled to run off in 2020.
Checkit (CKT) recent 2 months LFL rev up 14%. Cash at hand £13.1m. Says co "has sufficient cash for working capital purposes for significantly more than the next 12 months under all currently foreseeable economic scenarios." Withdraws guidance. I hold.
Revolution Bars Group (RBG) running costs cut to £0.4m per week. Renegotiated the surrender five leases, surrended payments now tot £2.25m (from 3.64m) and deferred payments. Bank agrees to increase facility to £30m (from £21m) to Aug, then £24m, waives covenants.
SIMEC Atlantis Energy (SAE) minimal disruption to the tidal business. Expects to deliver equipment and services to clients in Japan and Scotland this year as contracted. Uskmouth Power Station conversion project delayed.
Nakama Group (NAK) guides FY(March) marginally below management's expectations. Covid now has marked impact in UK. Co confident that business can continue to operate financially during the current COVID-19 crisis.
Fletcher King (FLK) first 11 months of FY in line with mgmt expectations. Likely that transaction-based fees such as investment deals and bank valuations are likely to be materially lower. Property management not expected to be affected to the same extent although fees may come under pressure. Co "in a good position to withstand the current crisis and continues to have a strong balance sheet with no debt."
Jarvis Securities (LON:JIM) Business update to shareholders. Steady as she goes, no adverse impact to business. There will be a dividend as usual. Still plenty of picks and shovels to supply the market.