Small Cap Value Report (Wed 23 May 2018) - AIEA, FST, SND, OPTI, BOTB

Good morning, it's Paul here!
There's plenty of news to report on today. A reader has asked me to look at Marks and Spencer (LON:MKS) results. I'm just printing off the RNS, and will have a look at it later. EDIT: I've read the MKS results, but as it's late now, I'll type up my thoughts in tomorrow's report.
Airea (LON:AIEA)
Share price: 54p (down 10.7% today, at 10:10)
No. shares: 41.35m
Market cap: £22.3m
(at the time of writing, I hold a long position in this share)
The unsolicited takeover bid approach from James Halstead (LON:JHD) has fallen through, with no agreement reached. It's interesting to compare the nuances of the statement from JHD here, and Airea's response here.
As you can see from the candlestick chart below, there was a big initial spike down in price first thing this morning. This is because the market makers would always heavily mark down any share where bid talks have ended unsuccessfully. Then they wait to see what happens in terms of buyers/sellers, and subsequently move the price in line with demand & supply, trying to keep as near as they can to a neutral book.
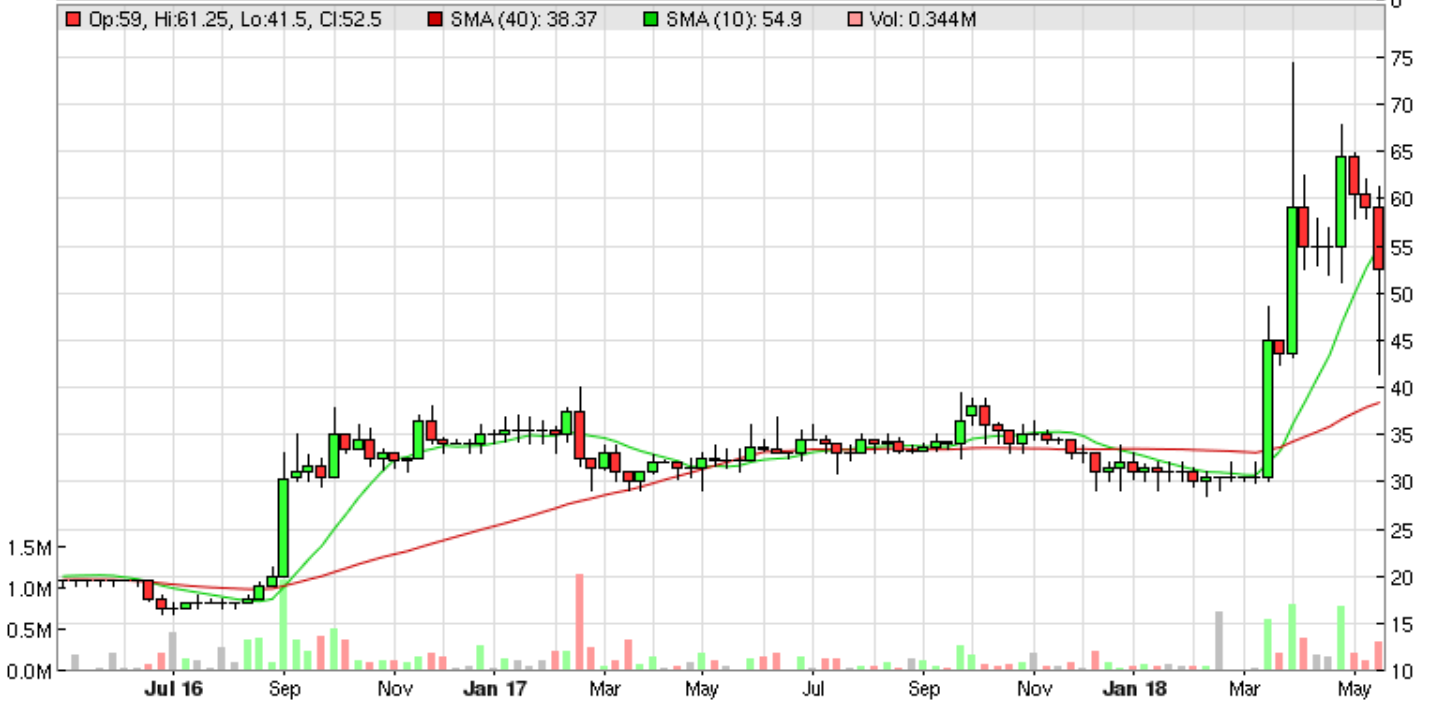
There seemed to be plenty of buyers in the market, and the price seems to have settled at 54p has
Fellow shareholders that I've been discussing this share with, on Twitter, seemed to be hoping that the bid talks would fail. Why? Well it's because the company announced very positive outlook for future profitability. I reported on that here on 21 Mar 2018. That's why I'm holding this stock, not for a takeover bid.
Therefore I think today is a transition day, when shares are passing from people who were hoping for a takeover bid, to people who are more interested in the company's organic growth potential.
Also, the liquidity that happens on a day like this means that people who wanted to buy shares, but couldn't get any, might be able to pick up a few. Anyway, I'm relaxed about the situation, as this is a long-term holding for me - I've already held for over a year, and imagine that I'll stay put for the foreseeable future, depending of course on newsflow & price.
Frontier Smart Technologies (LON:FST)
Share price: 89.5p (down 40% today, at 10:54)
No. shares: 40.65m
Market cap: £36.4m
Trading update (profit warning)
Bad luck to shareholders here - with the price down 40%, this must be fairly serious bad news.
The Group has two lines of business, Digital Radio (which is long established and profitable) and Smart Audio (which operates in a nascent market that has good medium-term growth prospects).
Although it's delivering bad news, I commend the company and its advisers for updating shareholders with specific guidance. This is far preferable to the silly coded words that many companies use to describe trading;
Challenging trading conditions in Q2-2018 are likely to have an adverse impact on the Group's FY-2018 trading performance.
Consequently, the Board is revising its guidance for FY-2018. The Board now expects full year sales of approximately US$47.7 million (£34.9 million) and EBITDA1 of c. US$1.0 million (£0.8 million).
It would have been helpful to have also stated what the previous guidance was, so that private investors without access to broker notes could see the extent of the fall in guidance. I'll have to try and work it out from previous announcements, which is a waste of my time, when the company could have included that information in today's announcement.
On 8 Mar 2018 the company said;
In FY 2018, the Board expects to see modest growth in revenues and EBITDA, as the Group continues to invest in Smart Audio (from RNS, 8 Mar 2018)
EBITDA for 2017 was £1.9m. Modest growth was originally expected in 2018, so that suggests maybe £2m+ EBITDA. Today's announcement reduces 2018 expectations to £0.8m EBITDA. In percentage terms that's a big drop, but not a particularly big drop in £ terms.
H2 weighting - investors don't tend to like this kind of thing;
Given the usual seasonality of the business, the Group expects to report an EBITDA loss in H1-2018 of approximately US$2.1 million (£1.5 million), followed by a stronger performance in H2-2018 when EBITDA is expected to be approximately US$3.1 million (£2.3 million).
The trouble is that there can be an element of wishful thinking involved, when companies hope to have a stronger H2. That may or may not be the case here, I don't know, but it often is the case at many companies - commentary indicating an H2 profit weighting can often be a deferred, second profit warning.
What's gone wrong? Here's my summary of the detail;
Digital radio - customers in Norway were over-stocked in late 2017, which led to reduced orders in Q1-2018. Orders now starting to return to more typical volumes - this sounds supportive of the company's belief that H2-2018 should be stronger.
Smart audio - aggressive pricing by Google and Amazon has...
...had a negative impact on Frontier's addressable market and the Board therefore expects growth in the Group's Smart Audio revenues in FY-2018 to be slower than previously anticipated.
Prospects here for FY-2019 are "more promising", apparently.
Forex - has impacted negatively EBITDA by $0.5m, the impact of which has been included in the revised guidance.
What's being done to fix things? - cost-cutting. The (large) R&D budget is being reduced by 20.8% this year, saving $2.2m. Other costs are being reduced by $1.2m in FY-2018.
Bank facilities have been renewed and increased, to help with working capital fluctuations. Net debt is expected to be modest at 30 Jun 2018, at $2.1m.
My opinion - I always try to categorise profit warnings into;
1) Short-term, fixable problems - where I would consider buying some shares after the dust has settled, and providing there is a sound balance sheet.
2) Structural, more serious problems - in which case I'd deploy my bargepole.
I don't know enough about this company to be sure either way. The issue with digital radio over-stocking sounds like a temporary problem, which would fall into the first category above.
However, the issues with the smart audio products sounds more serious. If you want a voice-activated device in your home (and personally I don't - Google & Amazon already control/monitor far too much of my life!), then you just buy a Google smart home device or Chromecast, or an Amazon Alexa or Firestick device. They're dirt cheap, and look nice. So I don't really understand why Frontier feels that it's worthwhile chasing a (probably small, maybe non-existent) future market for third party companies, designing more upmarket voice-controlled devices?
Therefore, I think this share is possibly best assessed as being a special situation where the smart audio business is probably worth nothing, and might even be a liability in terms of its future cash burn.
Accordingly, I would value Frontier shares purely on its digital radio business, and then deduct from that a provision for the shutdown costs of the other business. The digital radio business looks highly profitable, but mature. So that might see its profits decline in future?
Overall, this looks quite an interesting special situation. I like it when a highly profitable business is being obscured by a heavily loss-making fellow subsidiary. This was one of my themes at Mello Derby recently. A lot of us did tremendously well from Avesco which was this type of situation. French Connection (LON:FCCN) and Airea (LON:AIEA) (I hold shares in both) are similar situations where there's a heavily loss-making part of the business, which will be disposed of, or shut down in due course. As a result, group profits would soar, once the problem division has gone.
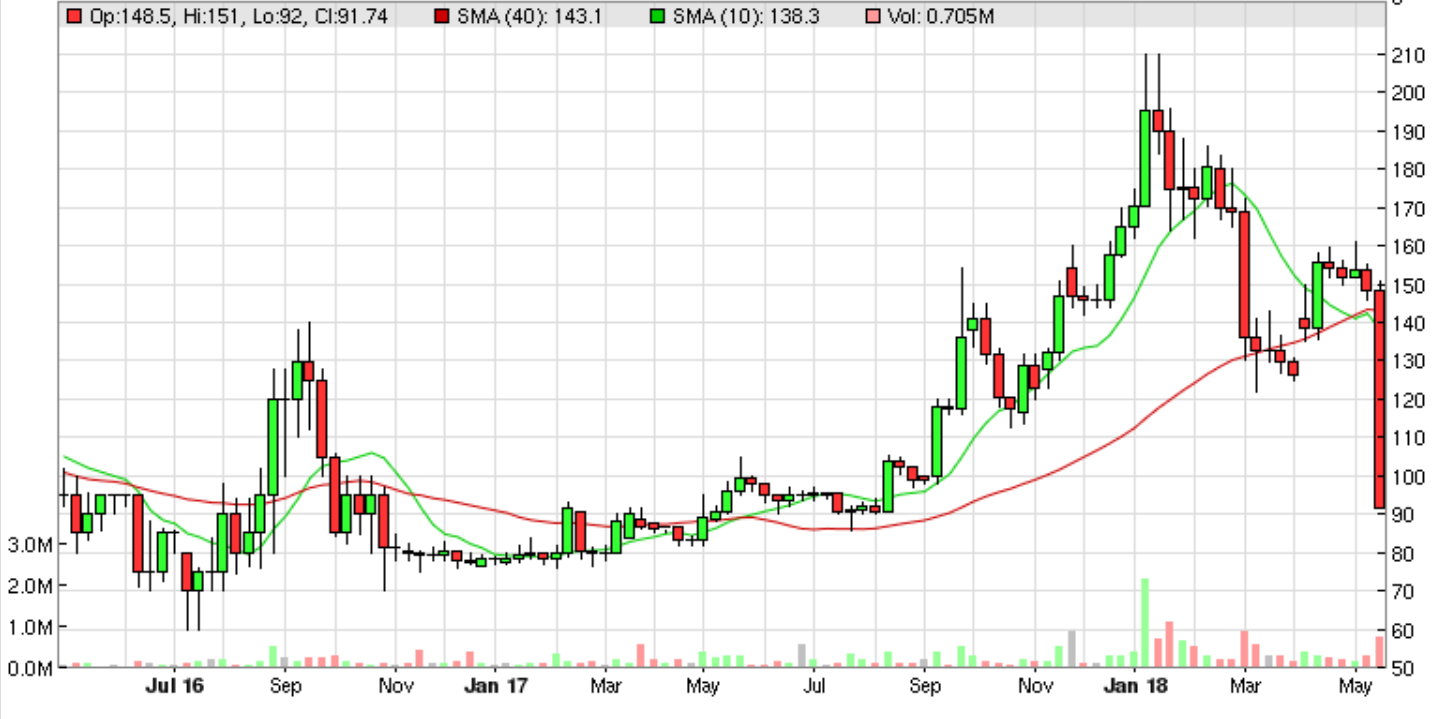
The 2-year chart below for Frontier seems to show that the froth in the share price, over hopes for smart audio, has now disappeared, which looks justified. The danger is that the company just keeps throwing money at something that probably won't work, or generate an acceptable return on investment.
I'll put this on my watchlist, but I don't see any rush to get involved. When growth companies go wrong, it can take quite a while for disappointed holders to (a) realise /admit that things have gone wrong, and (b) unwind their long positions if it's illiquid.
Best of the Best (LON:BOTB)
Share price: 270p (up 11.1% today, at 13:01)
No. shares: 10.07m
Market cap: £27.2m
(at the time of writing, I hold a long position in this share)
Best of the Best PLC, (LSE: BOTB) the organiser of weekly competitions to win luxury cars and other products wishes to make the following update on its VAT claim.
There are several elements to this, so here's my summary;
A long-running VAT dispute has settled in BOTB's favour, with £4.5m (before costs) being paid to the company by HMRC.
HMRC has told the company is liable to pay 4-years' back-dated Remote Gaming Duty - the company is disputing this, so overall this issue is not yet resolved in full. It seems to only be the back-dating of RGD payments that BOTB is dipsuting, as it now pays RGD on its current operations.
The wording of this bit suggests that the overall outcome should be positive for BOTB, once the RGD issue is settled. Although professional fees could end up being very large - this type of tax dispute work is an open chequebook job with most firms of accountants.
While the question of retrospective RGD remains unresolved with HMRC, the Company is unable to announce the full extent of the net positive contribution to the Company, following the payment of its £4.5m VAT claim from HMRC.
So we know BOTB will end up with a windfall, we just don't know how much.
Historically the company has paid out surplus cash in special divis, so I expect that to happen in due course with this too.
OptiBiotix Health (LON:OPTI)
Share price: 68.5p (down 5.5% today, at 13:23)
No. shares: 80.5m
Market cap: £55.1m
Audited results - for year ended 30 Nov 2017.
This is a jam tomorrow company, which has so far produced nothing of any commercial substance. Revenues are only £191k, and the operating loss was £2.1m.
Why has it taken almost 6 months to produce these results, given that the company doesn't really sell anything yet?
There was a £4.1m profit booked in 2017 for the disposal of a subsidiary, which now has its own AIM listing, called SkinBioTherapeutics (LON:SBTX) . I see that share price has put on a nice spurt recently. I've had a look on its website, and OPTI is shown as owning 41.9% of SBTX. So some of those shares could be sold to raise cash for OPTI.
OPTI itself looks to be nearly out of cash by now, based on it having only £1.25m at 30 Nov 2017, and cash burn of roughly £150k per month. Whilst investor sentiment is this high (evidenced by the £55m market cap), then I imagine raising more cash would be fairly easy - and I imagine is imminent.
Why am I mentioning this company at all, given that it's a jam tomorrow story stock? Well, only because the newsflow from the company appears to be impressive. There have been lots of announcements about contract wins, collaborations, etc, with apparently credible partners. Although the announcements I've looked at didn't seem to give any financial details of the deals done.
My opinion - the share price seems to entirely rest on punters bigging up the prospects for the company, "Just one product could be HUGE, and other projects are thrown in for free".
In my roughly 20 years in the market, I've heard so many stories like this, and only a tiny fraction of them actually work out anything like originally planned. For this reason, I don't punt on anything like this, because I have no way of knowing, or guessing at, whether the company will commercially succeed.
Whereas with Sosandar (LON:SOS) (in which I hold a long position), which is from the same company promoter as OPTI, Adam Reynolds, I do understand the sector they operate in, and trust my judgement in deciding whether or not it is likely to work. That is not the case in the sector where OPTI operates, where I haven't got a clue if products are credible or not!
For that reason, I'll happily sit on the sidelines with no position in OPTI. I would only get involved if and when it is able to demonstrate commercial success, rather than jam tomorrow promises, which is all we've got at the moment. The price might be higher once commercial success is a fact rather than an aspiration, but so be it.
Sanderson (LON:SND)
Share price: 112.5p (up 7.1% today, at market close)
No. shares: 59.8m
Market cap: £67.3m
(at the time of writing, I hold a long position in this share)
Sanderson Group plc ('Sanderson' or 'the Group'), the software and IT services business specialising in digital retail technology and enterprise software for businesses operating in the manufacturing, wholesale distribution and logistics sectors, announces Interim Results for the six month period ended 31 March 2018.
The market has responded positively to these half year results, which are "slightly ahead of management's expectations"
- H1 Revenue up 34% to £14.6m, but this is nearly all down to an acquisition (called Anisa). Organic revenues were only up 1.7%
- Recurring revenues are 56% of total revenue, and this rises to 90% if you include incremental sales to existing customers. I like the sound of that, as it suggests that customers have confidence in the software, if they buy more of it.
- More "selective" acquisitions are under consideration.
- Cash generation is good.
- Like-for-like operating profit grew over 12% to £1.74m in H1.
- Net cash of £1.4m at 31 Mar 2018.
- Strong order book of £8.6m
- IFRS 15 might become an issue in future. Note 1 in today's accounts says;
The Group is in the process of assessing the impact that the application of these standards will have on the Group's Financial Statements.
I've not looked into IFRS 15, has anyone else?
Outlook comments - key points;
- Not detected any major loss of confidence amongst its customers (suggests that there has been some minor loss of confidence!)
- Sales cycles can be protracted
The company's conclusion is;
... the Board has a good level of confidence that Sanderson will make significant further progress during the current financial year ending 30 September 2018.
Balance sheet - this is where it goes wrong for me. The company claims to have a strong balance sheet, but that's not true in my view. On my key balance sheet tests, it's weak, e.g.
NAV: £31.5m, but this is dominanted with intangible assets of £43.2m. Take that off, and;
NTAV: is negative, at -£11.7m. That latest acquisition of Anisa hasn't helped, because Anisa had a ropey balance sheet (negative NTAV of £6.1m at the time of acquisition), including some debt, which Sanderson has now taken on. No equity was raised to fund the acquisition, although £2.8m of new Sanderson shares were issued as partial consideration, with a 3-year lockin, which amounts to the same thing as issuing new equity, I suppose.
Trade receivables looks too high, even allowing for the fact that Anisa's balance sheet figures are fully consolidated, after only 4 months trading in the P&L.
The whole business is run on deferred income - i.e. customers paying up-front. This is reflected in £9.0m deferred income - which is a lot larger than the £5.1m cash pile. So the company spends almost half of the client cash before having provided the service that they're paying for.
There are various other sundry creditors which add up to a fair bit - e.g. £1,047k loan notes, £1,138k deferred consideration, £916k bank loan/overdraft, in current liabilities.
Then there's another £2.75m in bank loans, and £500k in deferred consideration in long-term creditors, plus a £6.1m pension deficit (that requires cash injections of £360k p.a.). It all adds up, and paying these liabilities means less cash for dividends.
The current ratio of 0.78 is very low - which reflects the favourable working capital nature of the business, in that customers pay up-front.
I'm not saying there's anything to be alarmed about, as it's a decently cash generative business, which should be able to operate fine with a rather stretched balance sheet - providing nothing goes wrong with overall trading. In the next recession, management here might regret that they didn't strengthen the balance sheet by raising a bit more equity along the way.
Cashflow statement - looks fine. Note that the company capitalised £321k in development spending in H1, which is quite modest. So no issues here.
Valuation - the house broker update is available today on Research Tree. It maintains a current year forecast of 6.5p EPS. That gives a current year PER of 17.3, which strikes me as probably fully priced.
My opinion - I quite like this company. The detailed commentary today contains lots of interesting detail, and things seem to be going well, with a decent outlook.
I'm less keen on a stretched-looking balance sheet, but I don't think that necessarily presents any immediate problems.
A product worry is that clients might decide to re-platform, to a bigger competitor. There seems to be a trend towards some big American platforms becoming almost industry standards, e.g. Spotify, Magento.
Given the recent share price surge, 'm tempted to bank my profits and move on. Although the very high StockRank and the general "run your winners" catchphrase, are pulling me in the other direction! Decisions, decisions...
That's all for today.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

40 comments
Good report from BOWL
Paul
In relation to IFRS 15, many companies have undertaken projects of how their business is impacted by IFRS and have been making summary disclosures in their accounting policy disclosures. Therefore, I am a little surprised by Sanderson (LON:SND) saying they are currently assessing the impact, although I don't think this is anything untoward.
Anyhow, here is a "quick" 5 step summary of the impacts:
1 Identify the contract with customer:
- who are the parties, what are the commitments/obligations, rights to goods/services and payment terms can be identified -> commercial substance.
2 Identify the performance obligation:
- this is the promise to deliver goods/services and can be distinct or part of larger contract (but distinct nonetheless) eg mobile phone contract which can be broken into the phone element and the data service plan. IFRS15 will apply to the data service plan and how it is recognised.
- Also raises questions of warranties and service plans, and application of discount vouchers
3 Determine the transaction price
- there could be a financing element involved eg mobile phone contract where the repayment of the phone is over 24 months.
4 Allocate the transaction price to performance obligations
- this may be an observable price if available. Or residual approach.
5 Recognise revenue:
- "transfer of control" principle. Recognise revenue as or when control of the good or service is transferred to a customer. Control may be transferred over time, or at a point in time. Assessed from customer's perspective and at the performance obligation level.
Previously revenue recognition was driven by risk/reward transfer.
From SCW
Frontier has developed silicon solutions incorporating Google and Amazon’s software and voice algorithms, so that third parties can launch VPA products. Companies like Microsoft and IBM will also want to get in on the action and I suspect there will be deals with Frontier in 2018.
Potentially there is a market. how big?
JBL are to use FST for their integration with Alexa & Google assistant on their speakers
https://uk.webfg.com/news/aim-...
Many thanks to everyone, Paul of course included, for taking the trouble to comment on the update from Frontier Smart Technologies (LON:FST).
Thought I would just add the results of my own further look at the Frontier Smart Technologies (LON:FST) update.
The exact wording on Smart Audio is "the Board therefore expects growth in the Group's Smart Audio revenues in FY-2018 to be slower than previously anticipated". That is a significant warning, but it is well short of being a disaster. The missing growth relates to hoped for revenue from wireless speakers which are voice assistant enabled. The implication is that FST's existing revenues for chips for wireless speakers, i.e. without Google Assistant, etc, are continuing to grow.
As I interpret events - and there is an element of guesswork here - to date FST's Smart Audio solution has been tied to ChromeCast and Google Assistant. Currently, Alexa has a much larger share of the market than Google Assistant. FST has only introduced modules for Alexa and for AirPlay this year, and necessarily won't be seeing any revenues from them until 2019. On the face of it, the preferred option for FST's customers is a product which offers the option of any of them, and this FST is now offering.
I have been successful with companies with a similar business model in the past, e.g. CSR - however, it is a characteristic that a lot of time elapses between the design wins and the revenue, and you are at the mercy of events outside your control. Also, "true" margins are thin - FST's customers are outsourcing their design work. As against that, the adverse impact of sterling movements is currently being unwound. I appreciate the excellent advice from some of you to cut my losses - I am not actually that far under water - and I will continue to mull swapping them for Marks & Sparks, as per Paul's latest thoughts - but at the moment a market cap of 36 million odd doesn't look out of order, so am putting it on the watch list, rather than selling.
Frontier has developed silicon solutions incorporating Google and Amazon’s software and voice algorithms, so that third parties can launch VPA products. Companies like Microsoft and IBM will also want to get in on the action and I suspect there will be deals with Frontier in 2018.
Potentially there is a market. how big?
This is always the case with these companies - seemingly huge addressable market with huge revenue potential. It's a big hook with a big lump of bait for investors. And yet the SR contains an unremittingly grim amount of negative numbers over several years. And yet they are cutting R&D as the cash from the last fundraising dwindles away. I just looked at their website. Look at this lot for a top heavy management team for such a small company:
http://www.frontiersmart.com/b...
As an engineer, I find it very annoying that when costs are cut the R&D team takes the hit when you still have this lot in place. Surely there's a bit too much fat in the management team? It's enough to make you wonder who's benefit the company is being run for?
I feel sorry for people that buy into these small cap UK tech stories. How many of them ever work out?
All the best, Si
Hi Abtan
The £4m run rate is my best guess of pre tax profit ..not revenue !
I posted elsewhere pre AGM my best guess;
‘
It was taking a view on the rate of climb, the CAPEX to permit new ranges & product variations took place in the early part of the reporting period;
‘Broader product range of new products based on new technology investment in 2017 has opened up new markets & opportunities as planned
..and
‘xport sales growth of 58 % over last six months following entry into new geographical markets, strengthening of international dealer network, and successful launch of new products’
..and
‘ In the eighteen months to 31 December 2017 the commercial floorcoverings division generated an operating profit before exceptional items of £4.3m on sales of £26.9m. The investment in new technology made earlier in the period is now coming to fruition with the launch of a series of new products, which will open up new higher value markets. This adds to the successful launch of a competitively priced entry product, which has already established a significant market share in its own right as well as opening up new opportunities for the rest of the product range. Burmatex now has a range of products to profitably compete across the broad spectrum of price points. We are already seeing the benefit in sales growth both in the UK and internationally.’
So trying to model this I assumed the 4.3m was back loaded , so first 6 mths say 1m, 2nd 6 mths 1.5m , 3rd 6 mths 1.8 m.. so that gives me an annualised current run rate of £3.5-£4m less the central costs previously borne by Ryalux
The critical piece of information is the timing of the Capex & the launch of the new products which to me suggests I may even be being too conservative ‘
AGM confirmed my sense of the timeline but I’d over estimated how long the new products had been in place..so maybe my guess is overly conservative ?
Cheers
Re Airea (LON:AIEA)
Rhomboid
Thanks very much for the detailed response and for going through your workings.
I can see why many might think 2018 will be a stellar year. Sadly I still have niggling doubts around why revenue has remained constant over the previous 2.5 years (it has not increased!), but operating margin has gone up significantly. IMHO there's a piece of the puzzle missing!
So I'll wait with interest for the next results, and no doubt kick myself when the price rockets up.
GLAH
A
Re Airea (LON:AIEA)
Sorry, I still can't get the text editor to link the Y/E 2016 accounts directly.
But for anyone interested you can access them here
Re Sanderson Plc
Results look good but am I missing something based on today results working capital is minus 4 million and
NTAV is minus 11.7 million (as they have 43 million of intangibles which I believe most is goodwill) anybody any thoughts ?
Paul - With respect, you need to take more care. Increased losses c£460k are related to the transfer of IP to SBTX. Likewise, increased admin down to SBTX IPO. Your cash burn is double the £90k pm. SOH stated at the UKI that funding is not required ahead of 2018 break even.
You are a retail man, and not one that is familiar with low risk, low cash. OPTI only started its transition from an R&D to commercial May 2017, since then it has signed 12 commercial agreement, not only increasing in size, but well geographically spread, all with no increased spend. Partner pickup the tab for promo, marketing and any additional R&D. There is also growing evidence of pharma interest. Which brings me to the fact ALL OPTI's platforms are phase 3 ready, saving pharma millions in R&D and 6-8 years.
OptiBiotix commercial progress for LP-LDL & SlimBiome
Cholesterol, hypertension and weight management.
SlimBiome is a multi award winner
Small Companies – £300k + pa (EACH)
THWLC (GoFigure) SlimBiome (May 2017)
HLH BioPharma – LP-LDL (May 2017) Germany and EU
PharmaBiota – LP-LDL (September 2017) New Zealand & Australia
Medium Companies – £500k to £1m pa (EACH)
Nutrilinea – LP-LDL (May 2017) EU
Knightons – SlimBiome (November 2017) UK
Cambridge Commodities – SlimBiome (April 2018) UK & EU
Seed Health – LP-LDL (TBC)
Large Companies £1.5m + pa (EACH)
SACCO – LP-LDL (August 2017) Global
Galenicum – LP-LDL (October 2017) EU, Middle East, Japan, America's
Cereal Ingredients Inc – SlimBiome (December 2018) USA
TATA – SlimBiome (December 2016) ASIA
TATA – LP-LDL (September 2017) India & Asia
Tigren pharmaceuticals – LP-LDL (April 2018) Pakistan
FineFoods & Pharmaceuticals -LP-LDL (March 2018) EU
AKUMS – LP-LDL + LP-LDL pharmaceutical (May 2018) India & South Asia
Undisclosed US partner – SlimBiome (TBC)
3 large UK Retailers – (TBC) these could yield **£5m – £6m pa
2 global corps interested in using SweetBiotix
Bened MOU cross partnership IP Asia & EU, USA
PLC costs under £1m pa – DO THE MATH
Note: No additional cash injection required from OptiBiotix as commercial ramp up progresses.
The market is missing a significant NEW development with AKUMS announcement. As well as OTC products, AKUMS has the option to take OPTI LP-LDL IP down the pharma route. Given OPTI platform is pharma based and phase 3 ready, this save 6-8 years R&D saving millions in the process.
It's no coincidence these last 3 commercial agreements have been with pharma companies with a who's who client list within the pharma industry; Abbott, Novartis, P&G, Pfizer, Bayer, Sanofi and Sandoz.
moonglum re:OPTI
Well reasoned but I understand Paul's hesitancy. In this instance OPTI are signing an impressive number of deals and are carving up the market, based on products, geography and where each partner sits in the supply chain.
I understand the market's and Paul's view on visibility of revenue and profits; OPTI have little control over such things, especially in the ramp-up phase. However, later on, the ability to drop incremental revenue largely to the bottom line whilst maintaining strict fixed cost control is very attractive - as are the four healthy spaces OPTI/SBTX are working in.
If they find they do need a little cash to tide them over then raising it or parting with 5-10% of SBTX should solve the shortfall.
Of course I understand Paul's hesitancy and that of the wider market. Frustrating as it is for me as an investor I have to trust the BOD on their strategy. Offering revenue guidance at such an early stage is fraught with dangers. For example; how do you guesstimate revenues for a new product, even though historically, there is a billion$ market? Also, OPTI would be at the mercy of partner product ETA, any slip in guidance in the order of 20% would result in a profit warning - potentially more damaging.
As much as it frustrates us, we have to be thankful the BOD are not the typical AIM BS ramp BOD. Sure they do a lot of interviews, they report a lot, but always understated and there is always a surprise partnership announcement. Never ever a sneaky rise ahead of the RNS. Very tight ship.
Ref SBTX; I don't think they will use any for funding purposes. Either way, we won't need to wait too long to find out if Paul is correct.
PS. Those figure I used, SOH thought they were good.
PPS. Except the small corps. He prefer I used £250k pa not £300k pa
Would be interested in any view on Hollywood Bowl (LON:BOWL) after interims today - revenue £63.6m+9.2% with lfl well up on last time at 4%, ptp $14.6m+17.4%, margins up, debt almost halved, positive outlook, forward PER around 16
Any chance of Graham covering PCF ?
Frontier Smart Technologies (LON:FST) isn't this another heavily promoted share tip from SCSW that appears to have crashed and burned?
Frontier Smart Technologies (LON:FST) another heavily promoted share tip from SCSW that's crashed and burned!
I've been following Airea (LON:AIEA) developments on the side and I still don't understand why so many are interested in it post a Ryalux sale.
Stripping out a c.£2m Ryalux operating loss for 12 months (my figures are based on a previously announced £3m operating loss over 18 months) would have increased 2017 group operating profit to c.£1.4m (from a group reported -£0.6m).
This doesn't seem that impressive for a company currently worth c£22m.
I understand that big growth numbers were thrown about for Burmatex, namely a 58% increase in non-UK revenues, however this was only from a base of non-UK revenues amounting to 22% of total Burmatex revenues.
I feel I must be missing something, but I really can't see what it is.
For more in-depth thoughts here are my comments from a couple of months ago:
https://www.stockopedia.com/co...
Hi abtan,
I think you've done your figures wrong on Airea (LON:AIEA)
By my calculations, it should be making £3-4m p.a. once the carpets division is gone.
Also, the core business is growing strongly, and introducing new products, and makes an operating profit margin of about 16%. So it's entirely feasible that Airea could be making maybe £5m+ annual profit in the not-too-distant future.
Point taken re the export sales growth being on a smallish percentage of total sales.
Regards, Paul.
Re Airea (LON:AIEA)
Hi Paul
Thanks for the reply.
I took a look at the last Burmatex accounts filed with Companies House* and compared the figures with what was RNS'd a couple of months ago.
REVENUE
12 months to June 2016 (Companies House) = £18m
18 months July 2016-December 2017 (RNS) = £27m
OPERATING PROFIT
12 month operating profit to June 2016 (Companies House) = £1.94m
PROFIT MARGIN
12 months to June 2016 (Companies House) = 9%
18 months July 2016-December 2017 (RNS) = 16%
I must admit that I couldn't see any reason why operating profit would jump 50% from £2m to >£3-4m in the space of a couple of years, or where (if?) I am making a mistake with my numbers.
Comparing 2015 with 2016 accounts at Companies House, there appears to be an additional lease cost from 2016 (£600k per annum) and stable staff costs (c £4.5m in each year) so no big movements there - all seems pretty consistent. The only thing that I could think that would increase Operating Profit % so much was therefore hedging FX exposure.
It also doesn't help that there are intra-group sales between Ryalux and Burmatex that are not quantified - it really masks what the true picture is for me.
I continue to be confused!
Thanks again
A
*(link to Companies House file in a separate post as the window keeps crashing when I try to paste it in as a link)
Hi Abtan
The key thing you’ve missed is the rate of climb at Burmatex, they’ve been launching new products off the back of acquiring a mega capability 1.5m bit of kit from the US, it only got installed in the first part of the period and took c6 months for them to get fully to grips with first new products launched in November 2017 & the latest to complete the range launch next month, my guess is they’re at a run rate of c£4m per annum now..here are my notes from the AGM
‘Neil Rylance CEO
Martin Toogood Chairman
Roger Salt FD/Co Sec
James Halstead sent a mute observer..who’d bought one share
NOMAD in attendance
c 20 shareholders..many ex employees
V warm welcome , great overview from Martin Toogood detailing Ryalux closure etc
Formal business passed on show of hands..nearly 100% proxy votes in favour
Then Q’s which for me boiled down to these key points in no particular order
They spent years getting ducks in a row to sort Pension scheme, now in surplus..could suspend contributions..up to the Board, been v creative to de risk it ..
Same re Ryalux closure ..shrinking it down to the point where it was possible to exit without risking the core business
Same re Surplus properties..5 leases down to 1 which ends soon leaving 10.5 acre freehold Ossett Mill site -Burmatex & £3.2m investment site in Bury leased for 10 yrs at £270k pa
Tenant is rock solid ..see attached
Most important point was rate of improvement in Burmatex post investment..took 1 yr for new loom to bed in, new launches only started end 2017 ..reception “amazing ‘
Now got full range covering all price points/market niches..2 more launches scheduled for next month..no crossover with Halstead..other than they’re both flooring related
Burmatex now 70-80% capacity utilised..1.5m USD loom might well need a duplicate..it took a year to get to grips with it but new one would be quick, Ossett plenty big enough 4 growth
My take..18 mths report is concealing a classic business reinvention..run rate in terms of P&L is c£4m per annum (my guess)
Mgt are on top of the business..in short I’m v happy to hold
Re Airea (LON:AIEA)
Hi Rhomboid
Thanks for your notes from the AGM, they are very much appreciated for folk like me who don't have the chance to go.
I didn't notice the $1.5m CAPEX expenditure for a new loom. Presumably that is in reference to the following:
"Capital expenditure of 1,280,000 (2016: 704,000) was made in renewing and enhancing manufacturing plant and equipment."
It's a shame that they don't explicitly state this if so.
I also had a thought on one of the comments.
Presumed run rate of c.£4m per annum@70-80% capacity. I'm assuming that this is additional revenue, implying maximum additional revenue@100% capacity of £5m per annum (on top of the c£18m booked on average over a 12 month period between July 2015 - December 2017) .
This would imply, assuming all else being equal, maximum annual revenue of the new company would be c£23m.
If I have misunderstood anything, thoughts from anyone would be appreciated.
Many thanks
A
I don't know how long MrContrarian has held his short in Restaurant Group but it has gone up from around 235p a couple of months ago to over 330p at one time this morning. Sometimes I wish I shorted shares but often I am glad I don't! Their pub business is sensational which proves they can run a restaurant but Frankie and Benny's obviously doesn't have the same type of customers. What a shame they don't just have the pubs.
Premier Asset Management (LON:PAM) mid year results look very strong.
Would welcome Paul's, or others', comments on the update from Frontier Smart Technologies (LON:FST). The market took fright and the shares have about halved. I hold. The main negatives are the postponement of expected revenues from Smart Audio into 2019, and the dependence of a cash flow breakeven on a good H2. Some sensible cuts in R&D spend to conserve cash. The market's worries look a little overdone to me.
HI Paul
I know it is not on your list and not sure if you have ever even mentioned it but do you have any comment on - Brave Bison BBSN. I would be very interested to hear your thoughts.
It does not have to be today.
Frontier Smart Technologies (LON:FST) 's business appears to be mostly in two markets I'd want to avoid:
1) Digital Radio (which appears to be limited to DAB / DAB+) - FM switch-off in many countries has been delayed / looks in doubt. The technology is basically obsolete and has few advantages over listening over the internet.
2) Making platforms to 3rd party voice assistants. Why anybody thinks there is a significant market for more than 2-3 manufacturers is beyond me. Even in their heyday no more than 2-3 companies got traction in MP3 players.Voice assistants are worse because they are sold cheaply by Amazon, Google in the hope that sales will drive the use of their services.
Hi Leoleo,
Re Frontier Smart Technologies (LON:FST), globally there were lots of manufacturers of MP3, and that is exactly what google wants to happen with voice assistance, lots of cheap products and thats why they making their platform open source and working with companies such as Frontier Smart Technologies (LON:FST) - highly likely to be a huge market and FST are signing up customers, just need to do it faster for less cost!
Frontier Smart Technologies (LON:FST) - I know somebody who used to work there. The CEO has a reputation. Put together a design team to design something. Once that's ready sack the design team. Milk product until obsolescence. Rinse and repeat. It's fair to say that such an approach does not engender much loyalty. It is also a small world and word gets around.
I asked about the cuts in R&D. "I didn't think he had anybody left to cut".
(No position)
BlueFrew, really sorry for the downtick, I meant to uptick but the mouse didn't want to comply and it won't let me fix it. Maybe someone could uptick to compensate? Kind regards Richard
Would welcome Paul's, or others', comments on the update from Frontier Smart Technologies(LON:FST). The market took fright and the shares have about halved. I hold. The main negatives are the postponement of expected revenues from Smart Audio into 2019, and the dependence of a cash flow breakeven on a good H2. Some sensible cuts in R&D spend to conserve cash. The market's worries look a little overdone to me.
Hi ST,
All I would ask is, why do you own shares in Frontier? Are they exercised share options from employment with the company? Just 10 seconds looking at the StockReport is more than enough time to waste researching this company. Frontier has been around for ages, I have known people that worked there, and it is one of those crappy UK tech companies (CyanConnode etc.) for which the only reason for a stock market listing is to get funding to keep the lights on. Funds that they would not get from many other sources. They inevitably make very poor investments although I imagine the management have done OK along the way.
Obviously, I'm sorry to hear you have lost money on this crock today but sometimes we all need a bit of tough love.
All the best, Si
I think Graham holds PCF (LON:PCF) which released in-line half year results today "strong growth" etc.
PCF is providing a dial-in facility for analysts and investors for a results briefing today at 1030h. The details are set out below:
UK Toll Number: +44 (0)2031394830
UK Toll-Free Number: 08082370030
PIN: 22896508#
Sanderson (LON:SND) - I looked at this for the first time just now. As Paul highlighted previously it has the red flag of claiming a strong balance sheet.
I see that the current ratio has now deteriorated badly, but perhaps if the "quality" of the deferred income is high then some allowance could be made? As I understand it they have taken pre-payments for services not yet provided, but if it is at a low risk of being subject to refunds (e.g. provision of more of the same rather than bespoke work) then for cashflow risk purposes deferred income can be ignored?
I think I a couple of weeks ago you talked about Airea (LON:AIEA) and possible takeover by James Halstead
I note this morning that the takeover now will not happen
Airea plc
("Airea" or the "Company")
Statement Regarding James Halstead plc
The Board of Airea notes the announcement made by James Halstead plc ("James
Halstead") that it does not intend to make an offer for Airea.
Best Of The Best (LON:BOTB) - the HMRC claim for back gaming duty should not come as a surprise to anyone, but I suppose we will see in the share price reaction this morning. My other concerns from December were sales to 16-17 year olds and (thanks to daveinthelakes) to US nationals whether or not living in the US - both of these still appear to be allowed by their latest T&Cs. I am also surprised by how little their T&Cs have changed to refect GDPR. My concerns over a delisting risk seem to have been a red-herring for now.
If looking for previous commentary the following will not show up in your search because it wasn't tagged in the main article: https://www.stockopedia.com/content/small-cap-value-report-wed-13-dec-2017-placeholder-252758/?page=1#comments
Hollywood Bowl (LON:BOWL) have had a good 6 months-
"Hollywood Bowl has produced another strong financial performance this period due to our continued progress in delivering against our strategic goals; the acquisition and opening of new centres that complement our already very high quality portfolio, creating modern, family friendly entertainment environments, and our refurbishment programme which has continued to drive organic like-for-like growth through the constant evolution of our customer experience."
Like for like revenue growth up 4% and PBT up over 17%, culminating in an EPS increase of 18%.
I hold.
'Wey Education (AIM: Wey Education (LON:WEY) ), the educational services group, announces that it has appointed Tony Knowles as Executive Director of Human Resources. Tony joined Wey on 15 May 2018 and he will head up the Company's human resource function.
Tony is a member of the CIPD and has held director level roles since 1996. He joins Wey Education from his position of Human Resources/Business Support Director of Veezu Holdings Limited, a private hire company based in Wales.' ...Anybody know the guy? Sounds like they're hiring. He gets options at current price, not exercisable till 2021.
Wey Education (LON:WEY) 's HR director recruitment and options incentivisation was mentioned in the recent private investor evening and quite possibly in previous statements. Having a well managed pool of teachers for use across the group is a major competitive advantage and so (despite my personal feelings about HR departments), it makes sense that this is a director level position.
I can see how his previous experience managing a pools of taxi drivers has its relevance, however I would prefer to have seen more experience managing professionals and ideally in education.
My morning smallcap tweet: Snowflakes at RTN expect FY in-line.
Clear Leisure (LON:CLP), Restaurant (LON:RTN), Sanderson (LON:SND), Frontier Smart Technologies (LON:FST), Mediazest (LON:MDZ), Bagir (LON:BAGR), Catalyst Media (LON:CMX), Best Of The Best (LON:BOTB)
Clear Leisure (CLP) placing to keep the lights on at 0.95p, a 9% discount.
Restaurant Group (RTN) trading. Last 20w LFL -4.3%, but snow-adjusted -3.1%. Guides FY in-line. I'm short.
Sanderson Group (SND) H1 slightly ahead of management's expectations; with rev up 34%, EPS up 44% to 2.3p. Outlook 'confidence'.
Frontier Smart Technology (FST) Trading. "Challenging trading conditions in Q2-2018 are likely to have an adverse impact on the Group's FY-2018 trading performance." Cuts FY sales guidance to $47.7m (£34.9m) and EBITDA of c. $1.0m (£0.8m). Cutting R&D spend by $2.2m and other cost cuts of $1.2m in FY. New revolving credit facility replaces one expiring Sept.
MediaZest (MDZ) guides FY revenue in line with the prior year but profitability marginally behind. £200k of profit from some last-minute orders won have fallen into FY19. Expects 'considerable' YoY improvement in H1.
Bagir Group (BAGR) Shandong Ruyi's aquisition of 54% of the Company's enlarged issued share capital taking longer than expected but both Ruyi and Board confident they will complete the deal.
Catalyst Media Group (CMX) Sports Information Service (in which CMX has 20% holding) will be hit by £2 max bet on FOBT. "The new media rights contracts that SIS has been entering into with UK and Irish racecourses will though partially mitigate the impact of the change on SIS's business, along with other mitigating actions that are being and could be implemented by SIS."
Best Of The Best (BOTB) The HMRC Strikes Back. HMRC has paid £4.5m claim but expenses need to be paid but now claims retrospective Remote Gaming Duty for a period of four years. No figure, is contesting.
Good looking set of interim results and outlook for Sanderson (LON:SND) this morning.
https://www.investegate.co.uk/sanderson-group-plc--snd-/rns/2018-interim-results/201805230700059353O/
EPS up 44% and still net cash despite Anisa acquisition.
Likewise Hollywood Bowl (LON:BOWL) is doing pretty well in it’s half year results. Still rolling out new/re-furbed venues while managing to reduce debt position. Margins/revenues per customer improving too.
https://www.investegate.co.uk/hollywood-bowl-group--bowl-/rns/half-year-results/201805230700037801O/
Gus.