Small Cap Value Report (Wed 21 Mar 2018) - MOSB, AIEA, LPA, CPR, MTC

, MTCHi, it's Paul here.
To get you started, here is the link to yesterday's completed report, where I looked at results from Cloudcall (LON:CALL) and Blancco Technology (LON:BLTG) , plus a positive update from Pennant International (LON:PEN) .
I'm not sure about timings for Wednesday's report, as I have to hire a car first thing in the morning, and take our dogs to the other side of London to the doggie hospital, to have a few things fixed. As they'll be under general anaesthetic, I could have to hang around all day. So will take my laptop with me, and I'll try to get something posted once I find a quiet corner with a plug socket and wifi.
EDIT: Good news! The dogs survived their operations, and are recuperating well :-)
Moss Bros (LON:MOSB)
Share price: 45p (down 23.2% today)
No. shares: 100.8m
Market cap: £45.4m
Trading update (profit warning)
Moss Bros Group PLC ("the Group"), the 'first choice for men's tailoring' today issues the following Trading Update for the 52-week period from 28 January 2018 to 26 January 2019.
The first thing to note is that the current financial year has barely started, so it seems an odd time to be putting out a trading update. Particularly as full year results are due out in a week's time. So trading must have deteriorated, necessitating a profit warning.
This is clearly bad news;
Following a review of projections for the year ending 26 January 2019, the Board now anticipates that the Group will deliver profit at a level materially lower than current market expectations.
There are no changes to results for year ended 31 Jan 2018, which will be announced next week, on 27 Mar 2018.
What's gone wrong then? As you would expect, consumer confidence is mentioned for 2 of the 3 reasons given;
· Hire sales continue to be challenging, although the peak trading period for Hire is still to come. As such the Group has remained prudent in its outlook.
· The reduction in store footfall that was experienced towards the latter part of December, has continued, reflecting a more cautious consumer environment.
However, there has also been some self-inflicted pain;
· Following the consolidation of the Group's supplier base in response to Sterling weakness, there have been material short-term issues with the resulting availability of stock. This stock shortfall across all categories has had a negative effect on sales in all retail channels and will continue to do so until late Spring.
Hmmm. You just can't afford to get the basics wrong in retailing. Buying the correct amount of stock, and getting it into the right place, at the right time, really is just basic stuff. So I'm deeply unimpressed with this - it tells me that there are management shortcomings at this company.
Dividends - are being cut. This is sensible, as the existing divis were not properly covered by earnings. So people chasing the high yield were arguably not thinking straight. High yields are often not sustainable. So sometimes it's better to go for medium, but growing, and sustainable divis.
As a consequence of this revised view on FY18/19 results, the Board has reviewed its approach to dividend. The Group has a strong balance sheet but, given the more challenging trading environment, the Board is taking a prudent approach to capital management and has decided to modify the existing dividend policy to ensure that we are able to fully cover our future dividends with profits in FY20/21 and onwards.
The Board will therefore be recommending a final dividend of 1.97p, meaning a total FY dividend of 4p per share for FY17/18 (5.89p FY16/17).
That's not a huge cut in divi, and would leave the yield at 8.9% - a level which is the market telling us that it doesn't think the reduced divi is sustainable. If it is sustainable at that level, then the share might be worth buying for income. Although that looks a risky strategy to me - buying a high yielding share, in a company that is struggling with current trading, often works out badly.
Balance sheet - is it really strong? Regulars here know that whenever I read narrative from a company boasting of a strong balance sheet, I have to check it! Very often the reverse is true.
In this case, I'm pleased to report that MOSB does indeed have a strong balance sheet. Here are the key figures from the latest (interim) balance sheet;
NAV: £35.6m
NTAV: £33.8m
Current assets: £41.1m (including £21.5m cash)
Current liabilities: £23.3m
Net current assets: £17.8m
Current ratio: 1.76 - retailers can manage on a lower current ratio than most other companies, because they sell direct for cash, so don't have much in receivables. So anything about 1.0 is usually fine. In this case, the working capital position looks very healthy. This company won't be going bust any time soon, even if trading deteriorates further. Maybe the divis are sustainable then, if trading stabilises?
Outlook comments seem a bit unrealistically upbeat to me. So maybe management are trying to put a positive gloss on a deteriorating situation?
That said, a key thing I look for in profit warnings, is short-term, fixable issues. The stock availability problem here ticks that box, as it looks to be sorted fairly soon;
"The beginning of the year has been hampered by short term stock delivery issues caused by the consolidation of our supplier base. The resulting stock shortage has undoubtedly driven a significant shortfall in sales, which will continue until late Spring.
Although this has been a painful experience, I am confident that the availability issues are well on track to being resolved and the margin benefits from the consolidation will flow through.
This year's poor H1 could therefore turn into next year's soft comparatives, and stronger results, perhaps?
Broker updates - I can't find anything, unfortunately. In this MiFID II world, we are now heavily restricted in what research is available to ordinary investors. Therefore, it is imperative that companies provide guidance in RNSs, as to what the expected range of profits for the current year will be. More & more companies are doing this, thankfully. However, in this case, MOSB has not given any guidance, thus leaving investors in the dark. Inevitably then, the damage to the share price is likely to be greater than if they had properly managed investor expectations by providing profit guidance in today's update.
I think it will be a long process to educate companies, brokers & PR people, that individual investors need proper information, now we often can't get hold of broker research any more. If this is not done, then liquidity will just dry up. How can investors buy this, or any other share, where we don't have profit guidance?
Woolly, wordy updates, whilst briefing research analysts on the side, is not good enough. Proper guidance needs to be provided to the whole market, at the same time, direct from companies. Just look at other retailers, in particular Next (LON:NXT) which absolutely excels in this regard - giving a specific, and gradually narrowing range of profit expectations for each year, as the year progresses. Everyone needs to get into this mindset, and there's really no excuse for not doing so.
My opinion - without updated profit guidance, it's impossible for me to accurately form a view on this share.
Having said that, I've been saying for literally years that this share was over-priced. It's now coming down to a more sensible valuation, where I would consider a purchase, if more information was available.
Bull points;
- Strong balance sheet
- Very high dividend yield - could possibly be sustainable, but I wouldn't bank on that
- Little direct competition on the High Street, and has a strong position in the wedding hire market
- Valuation has now come back down to earth - is bad news now in the price? Recovery possible
- Promising higher gross margin once supply chain issues fixed - which look like a temporary, fixable problem
- Recent very extreme weather is a bit of a one-off, so should not really affect the long-term value of the company
Bear points
- Will this be the last profit warning?
- Lowish profit margin
- All the usual rising cost pressures facing retailers - higher wages, business rates, imported goods cost (although pound now stable against US dollar)
- Subdued consumer confidence likely for 2018 (and possibly beyond, who knows?)
- Internet competition
- General problem for physical retailers of upward-only rent reviews on leasehold sites - so fixed/rising costs, versus potentially falling sales
That's not exhaustive, it's just what I could think of.
Overall, I think this is starting to look potentially interesting. I don't see any particular need to rush in and buy now, but will be adding it to my watch list.
What I find interesting, is that the squeeze on real incomes is coming to an end. The latest stats show that inflation has fallen from 3.0% to 2.7%. Whilst average wages are rising by 2.5%. Inflation should continue falling, because the impact of the devaluation of sterling is now dropping out of the figures. Also, consumers are resisting price rises, leading to a lot of discounting.
Therefore, looking ahead, I think there are potentially some excellent bargains, if you're very, very selective, in the retailing space. The market is incredibly negative on retailers right now - rightly so, as companies like Debenhams (LON:DEB) , Mothercare (LON:MTC) , and Carpetright (LON:CPR) look to be in real trouble - needing to raise more cash, and stuck with problem leases.
However, other companies with cash-laden balance sheets can ride out the current downturn, and may then end up with greater market share when consumers do start to relax the purse strings a bit, when real incomes begin rising again - probably later this year, based on the trajectory of inflation (coming down), and wages (rising).
Could investors be throwing the baby out with the bathwater? In one or two carefully selected cases, quite possibly. The key is having cash in the bank. Anything that needs to raise fresh equity, in the current very depressed environment for retail shares, is probably best avoided in my view. Why take the risk? Conviviality (LON:CVR) (in which I hold a long position) has recently given me a painful & expensive refresher course about this issue.
Airea (LON:AIEA)
Share price: 44.5p (up 27.1% today)
No. shares: 41.35m
Market cap: £18.4m
(at the time of writing, I hold a long position in this share)
This is a small company, based in Yorkshire, which makes niche floor-coverings. I've just noticed that its address is "Victoria Mills", so wonder if it historically had anything to do with Victoria Carpets?
I bought a small long position in this company over a year ago, and it's been lying dormant in my portfolio ever since. My reason for purchase, was that it came up on a value share screen that I run from time to time - looking for low PER, decent yielding, sound balance sheet companies. The thorn in the side with Airea was that it had a pension deficit. Even so, it looked cheap to me.
The share has sprung into life today, with a couple of announcements, this one from yesterday afternoon;
Proposed closure of Ryalux - this is a high quality carpet business, owned by the group, which has been loss-making. So they are closing it down;
...The closure which is anticipated to be completed by 30 April 2018 is likely to be cash generative and proceeds will be distributed to shareholders.
Obviously this is bad news for employees, although the company says that some may be able to find alternative employment in other parts of the group. For shareholders though, who fund the losses, the closure of a problem division clearly provides upside - not just with a cash distribution, but also that group profits should rise significantly.
Final results - for the 18 month period ended 31 Dec 2017 came out this morning, and have really put a rocket under the share price. I really dislike non-comparable results periods, as you don't really know how the business is performing, particularly if it has a lot of seasonality. So an 18-month period could contain 2 buoyant halves, and 1 quiet half year, thus presenting an overly favourable impression. It's helpful when companies produce pro forma 12-monthly comparisons, but that hasn't been done in this case. Never mind, I'll have to work with what we've got, and with the share price up 27% today, giving my portfolio a much-needed boost (as all my retail shares are being hammered), I won't complain too loudly!
The highlights list is pretty spectacular;
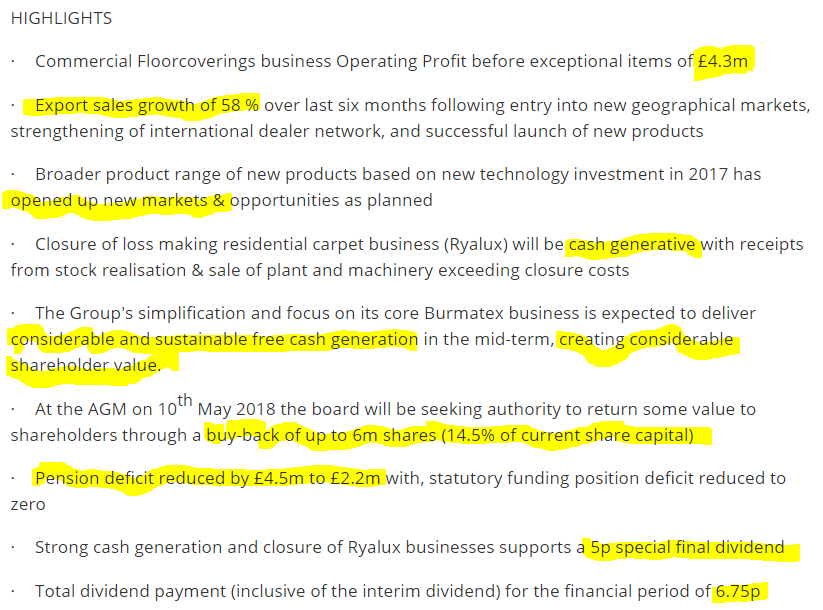
That all looks self-explanatory to me. I think it warrants a complete re-assessment of what this company is worth.
The losses at Ryalux have obscured a highly profitable core business, as explained in this section of the narrative;
In the 18 months to 31 December 2017 Ryalux Carpets Limited generated an operating loss before exceptional items of £3.1m on revenue of £9.9 million. The Company has incurred exceptional costs of £1.7m, inclusive of £1.1m of asset impairment and provisions, associated largely with a reduction in working capital and impairment of assets. Overall, the closure is likely to be cash generative, with receipts from the realisation of assets being greater than closure costs.
Going forward the increase in free cash generation arising from the proposed elimination of losses previously incurred by Ryalux will enable increased investment in the highly profitable commercial flooring business operated under the Burmatex brand ("Burmatex"). In the eighteen months to 31 December 2017 the commercial floorcoverings division generated an operating profit before exceptional items of £4.3m on sales of £26.9m.
Clearly then, the core business of Burmatex is excellent - that's a 16.0% operating profit margin.
It sounds as if Burmatex has good growth potential too;
The investment in new technology made earlier in the period is now coming to fruition with the launch of a series of new products, which will open up new higher value markets.
This adds to the successful launch of a competitively priced entry product, which has already established a significant market share in its own right as well as opening up new opportunities for the rest of the product range.
Burmatex now has a range of products to profitably compete across the broad spectrum of price points. We are already seeing the benefit in sales growth both in the UK and internationally.
(I'm taking some time now to read the full 2017 Annual Report, which is on the company's website. I've just spotted the remarkable news from CarpetRight, so will do a section on that now)
Later: I'm too tired to read the Annual Report, so have printed it out to read at some point in the future. Just a final quick point, re the;
Pension deficit - this was a big deal in the past for this company, but 2 factors have made it far less of a worry now;
- The deficit has greatly reduced, as announced today.
- The scheme doesn't need more company contributions, but the company has decided to continue paying in, to help reduce the riskiness of its assets (I assume that might mean rotating out of equities into high quality bonds). So an end is in sight for the deficit, the way I look at things. That means it is less of a detriment to the valuation of the shares.
- Earnings looks set to significantly increase once the carpet business has been shut down. Therefore the pension scheme will be diluted by much higher earnings. So again, less of a valuation worry.
My opinion - I've seen enough from today's update to be enthused by the outlook for this share.
Sadly it's very illiquid, so difficult to buy or sell. However, I've seen enough from today's announcement to want to sit tight, very firmly, on my existing shares.
I'll do more research to try to ascertain what they might be worth in future. As is so often the case though, there's a lack of broker research. I hope the company might get some decent research put out by the house broker, or better still by a decent quality commissioned research company.
Carpetright (LON:CPR)
Share price: 41.0p (up 1% today, at market close)
No. shares: 67.9m
Market cap: £27.8m
Shareholder loan & strategy update
The unravelling of share prices in weaker retailers is fast becoming the biggest story of 2018. Just look at the chart for CarpetRight to see how quickly this one fell apart;
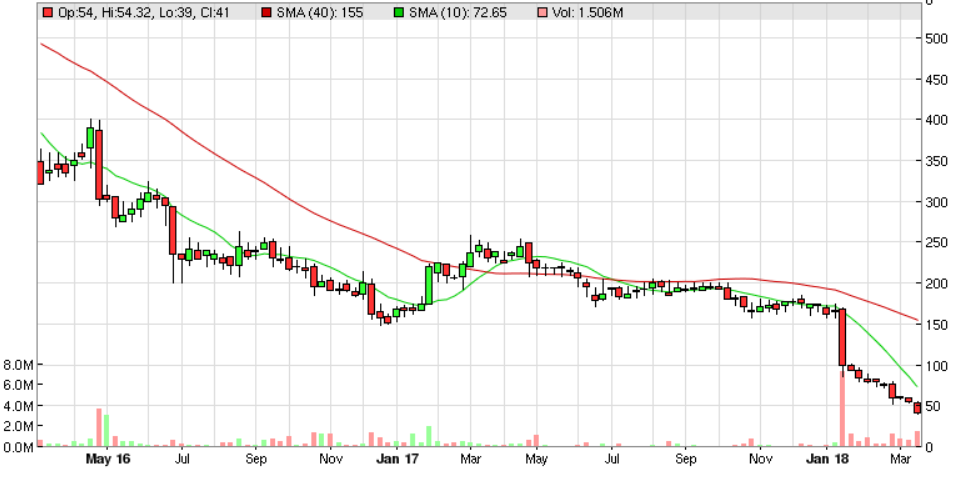
Today the company announces;
Shareholder loan - of £12.5m, from Meditor European Master Fund. The latest RNS indicates that Meditor owns 12.29% of the equity, worth only £3.4m at present. So this is a substantial loan compared with its equity holding.
It's just a short-term bridging loan, is unsecured, with a repayment date of 31 Aug 2018, and modest interest of 3% p.a.. The huge 15% arrangement fee, of £1.875m, is mainly being used to subscribe for new shares, which doesn't seem so bad in the circumstances. Also note that they haven't demanded a discount on the new shares - it's at the current share price. This suggests to me that Meditor seems to want to protect & rebuild the share price, perhaps? (as opposed to diluting everyone else to oblivion - although that might come later, who knows?)
[Arrangement fee of] ... £1.875 million (of which c.£1.379 million is to be applied by Meditor in subscribing for 3,396,200 new ordinary shares of 1p each in the capital of the Company at 40.6 pence per share (being the closing price per share on 20 March 2018) (the "Subscription Shares"))
Given that beggars can't be choosers, this arrangement looks pretty reasonable to me - the company probably had few to no alternative offers. Every company would wish to have shareholders prepared to step up and bail them out, if things go pear-shaped. It's a pity that large shareholders in Conviviality (LON:CVR) (in which I, unfortunately hold a long position) didn't display similar support when needed, before those shares got suspended, and existing shareholders look likely to be almost wiped out in that case.
Possible CVA - this is massive news. CVAs are really the only way for struggling retailers to ditch their onerous property leases, so this looks a very sensible move to me, if it can be pulled off. The trouble is, if landlords refuse to back the CVA, then the company is almost certainly bust.
On 1 March 2018, the Company announced that it was examining a range of options to accelerate the turnaround of the business and strengthen its balance sheet. Further to that announcement, the Company announces that it is currently exploring the feasibility of a company voluntary arrangement (the "CVA"), the objective of which would be to address the legacy property issue inherited from the previous leadership by rationalising the Company's property portfolio in order to improve the long-term prospects of the business. The Board believes that a CVA would not adversely affect the Company's ability to serve its customers.
Following the CVA, the Company intends to raise between £40 million and £60 million through an equity issue. If launched, the Company expects that the proceeds of the equity issue would be used to fund the Group's on-going strategy, reduce indebtedness and cover the costs associated with the CVA.
As part of this process, the Company remains in discussion with its lenders and will seek to agree amendments to the terms of its banking facilities, including a relaxation of the Company's covenants and an extension of the facilities. It is anticipated that the approval of the CVA will be a condition to any extension of the facilities.
To my mind that all makes complete sense. I imagine that the landlords would probably agree a CVA, as it's better than letting the whole business fail. Once that's done, the bank maintains support to give enough time for the company to raise fresh equity. Investors are likely to be prepared to put in fresh equity, because the loss-making property leases would have been ditched in the CVA, so the cleaned up company would be a lot more profitable - hence a more attractive investment.
At the end of the process, there should be a clean company, which is much more profitable, because it's jettisoned loss-making sites - arguably giving it an unfair advantage in future.
My opinion - this totally makes sense to me. I previously wondered whether CarpetRight's buffer of freehold property might enable it to survive without such a restructuring. Clearly though, the problem leases must have been worse than realised.
The trouble is, we simply don't have the information we need to assess how situations like this work out. What is needed is to find out individual site P&Ls, together with the terms of each individual lease. If problem leases only have a year or two to run, then they're not so much of a problem. If it's say 15 years, then those leases could pull down the whole company.
Carpetright's CEO comments today reinforce this point, as this excerpt shows;
"The aggressive store opening strategy pursued by the Company's previous leadership has left Carpetright burdened with an oversized property estate consisting of too many poorly located stores on rents which are simply unsustainable.
The Company has worked hard over recent years to address this legacy issue and reduce the size of its property estate, however many of these poor performing stores still have long leases to run, which has limited our ability to exit a meaningful number in the short-to-medium term.
I think this situation raises questions for the auditors. It seems that the reality is that a far larger onerous lease provision should have been made in the accounts. We need to be wary of this issue at other struggling retailers. It's too easy for management to pull the wool over auditor's eyes, by giving them unrealistically positive forecasts for struggling sites, thus reducing onerous lease provisions far below what is actually needed.
I suspect we might see a wave of CVAs amongst household name retailers this year. It's frightening how a relatively small drop in sales, can end up crippling retailers with inflexible leases, and rising overheads. No wonder investors are panic selling many other retail shares.
The quandary now for CPR small shareholders, is that the outcome is out of your hands. If landlords reject CVA proposals, then the shares would probably be a 100% loss.
I suspect that the CVA is likely to succeed, which is good for shareholders, but you don't know at what price you'll be diluted in the subsequent equity fundraising. Raising £40-60m in a distressed situation, with a current market cap of £27.8m, means existing holders are going to be heavily diluted. However, what if there's little appetite to refinance it, and the new shareholders will only stump up fresh equity at say 10p per share? Or less? In that case, existing holders would be all but wiped out.
Overall then, I reckon Carpetright is likely to survive, and should be much more profitable after the mooted CVA. How much of the cleansed company is actually owned by existing shareholders, is the big question mark. On balance, if I had already lost 90%-ish of my money on this share, and with a credible route out of its current problems, I'd probably just stick with it, making a mental note that it could be a total loss if things don't go smoothly.
My commiserations to shareholders here. It's a real eye-opener just how quickly a situation can unravel. It won't be the last one either.
The other question mark is who the landlords are, of all these retail properties that are going to have to be re-let at substantially lower rents? The only thing that can give, in the current retail crisis, is rents - they have to come down, substantially. There are no other costs that can be reduced. So holding shares in property companies which own retail sites, is not something I would want to entertain.
Mothercare (LON:MTC)
Share price: 16.4p (up 4.5% today)
No. shares: 170.9m
Market cap: £28.0m
The banks are being co-operative. Of course they will, because they want shareholders to stump up more cash & rescue the business.
Much like the other distressed retailers, this one is now a special situation, where there's quite a high likelihood that either insolvency, or a highly dilutive rescue fundraising might be the only feasible outcomes.
The trouble is, these days people are buying things on Amazon. There's not really any reason for Mothercare to exist any more, other than as a showroom, or perhaps for affluent areas where people like to physically see the goods, in an aspirational environment, before buying. I saw a Mothercare in Abu Dhabi a while back, in a glitzy mall. These days, though, those previously highly profitable overseas areas, are becoming less profitable.
I think investors might also baulk at refinancing Mothercare again, since the ambitious turnaround plan of Mark Newton-Jones hasn't worked, and a lot of fresh funding was just wasted in exiting loss-making sites.
A CVA here looks the only feasible option. Or perhaps putting the UK business into Administration, and keeping the overseas/franchise business? A market cap down to just £28m tells us that, sadly, Mothercare is very much in the last chance saloon.
It's not that we're in a recession, it's just that the internet has changed everything. People are buying stuff online now, and Amazon seems to be taking over. Only the best physical retailers are likely to survive - the ones that offer something unique, and scarce, that you can't buy online, and retailers that offer a genuine experience, that recognise non-food shopping is now an experience, that should be enjoyed.
Again, it all boils down to fixed costs. If 20% of your business disappears online, then a once-affordable set of fixed costs (rent + rates + utilities) suddenly becomes burdensome. Watch out landlords, I think another CVA may be coming your way. One of many, probably. The rents are just far too high now.
LPA (LON:LPA)
Share price: 173p (up2.1% today)
No. shares: 12.38m
Market cap: £21.4m
(at the time of writing, I hold a long position in this share)
This was issued at 11:49 today, when the AGM started at noon. That's not right. I appreciate that they are trying to announce information at the same time, but in practice it means that people at the AGM cannot take action if good or bad news is announced, whereas people in the City behind their screens can act immediately, and have 11 minutes advance warning. People don't usually leave AGMs to urgently issue buy or sell orders to their brokers, but it does happen - I know of several people who have texted or phoned their broker to dump their entire holding during an AGM.
The solution is that an AGM statement text should always be announced at 7am, so everyone can see it before the market opens. Then the Chairman should just read it out at the meeting.
Why, oh why, are basic things like this done so badly?
The first paragraph of the announcement has done a good job of tying me in knots - is it good, is it bad, who can say!
"In my statement included in the Annual Report published in January, I reported that output during the first quarter of the current financial year was at record levels. I am pleased to report that this has been sustained during the first half of the financial year, and the order book for delivery during the remainder of the year should present us with an excellent result.
While this performance should be at an exceptional level, well above recent historical levels and not necessarily sustainable in the immediate future, it has established the Company at a new level and in a very strong position to exploit many opportunities for major future growth in the medium and longer term.
If you can make sense of that, you're a better man than me! It sounds like it was written by the script writers of Father Fed!
The next paragraph also leaves me befuddled;
"The UK rail market is enjoying unprecedented, and quite possibly unsustainable, demand for improved infrastructure and new rolling stock, much of which may be satisfied in the short term by imports and in the longer term potentially by the establishment of new assembly facilities in the UK by international companies. We are seeking to establish ourselves in the supply chains of these new, mainly European, suppliers, but this is challenging because it requires us to displace existing members of their supply chains. As an established exporter, we are used to this challenge; to which our response is to work hard at building new relationships with those new customers whom we believe will be here for the long term while sustaining our relationships with our existing export customer base.
What the hell does that mean?!!!
I think they're basically saying that things are great, but might not be that great. It depends.
My opinion - I tried to buy some shares in this a while back, but found it too illiquid. So only a scrap of my buy order was filled.
It looks potentially interesting - with a StockRank of 90, Stockopedia seems to like it.
Suggestion - perhaps the company could find someone with more mental clarity to write the RNSs in future?
All done for today. Graham's relieving me of my duties for the rest of the week, and next week. So you might get some reports on time, hopefully!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

43 comments
Paul,
I, too, appreciate your insightful analysis on Carpetright.
Re LPA (LON:LPA): I think the writer of their releases needs to put himself into the mind of an average investor. What might be clear to him/her does not seem that way to the more distanced investor. A couple of years the ceo was using horse racing terminology to describe progress...'galloping along nicely '..that sort of thing.
Truly outstanding writing Paul, thanks very much for this. I don't care about the timing, we have plenty of great subscribers who provide timely information. However, for the depth and quality of your writing, there is no one else out there doing this to such a standard.
Paul - Agree about the poor LPA (LON:LPA) English. This is how Reuters "interpreted"...
March 21
* RECORD LEVELS OF OUTPUT SUSTAINED DURING 1ST HALF
* UK RAIL MARKET IS ENJOYING UNPRECEDENTED, AND QUITE POSSIBLY UNSUSTAINABLE DEMAND FOR IMPROVED INFRASTRUCTURE AND NEW ROLLING STOCK
Re Airea (LON:AIEA) results released yesterday.
I don't hold, but was intrigued enough to do some digging.
Despite initial enthusiasm I'm now in 2 minds on whether I like it or not. It's worth noting that I'm especially put off by the vast number of unknowns inherent in comparing 12m vs 18m figures.
Some thoughts below, which mainly focus on Burmatex, which will presumably (and essentially) become Airea going forward:
I imagine I'll be kicking myself for not buying in, but for now, I'll wait on the sidelines until there is more clarity in the numbers.
A
Share abtan’s sentiment
Re: cherry picking the 58% export sales growth, they do not point out that it is offset by a decrease in UK sales.
Re: pension deficit. I do not like the fact that it is quite a mature scheme but all plan assets invested in equities/property, and consequential vulnerability to market correction. The scheme liabilities are quite large relative to the market cap
A great write-up of Carpetright (LON:CPR) , thanks, Paul.
Micro Focus International (LON:MCRO) - Heavy director buys today after profit warning. I mention partly because it has many of the same red flags as Conviviality (LON:CVR) - high debt to market value, losing control of business after transformational merger, heavily negative NTAV and of course the director buying. The big difference is that they seem to have no covenants, loads of cash and debt headroom, plus good gross margins.
Paul writes I suspect we might see a wave of CVAs amongst household name retailers this year in respect of Carpetright (LON:CPR) and now another has just been announced for New Look:
http://www.bbc.co.uk/news/busi...
Conviviality (LON:CVR) update: https://investegate.co.uk/conviviality-plc--cvr-/rns/update-on-progress-and-potential-equity-fundraise/201803211800325212I/
EDIT:
Headline: Going to meet institutions to discuss a £125m placing. £5m open offer if successful.
Three things stood out for me.
1) They have payments overdue with their creditors and are not operating normal trading terms.
I don't see how this can have happened in the last few days and even if it has by not paying their dividend their cash position is better than expected. If they could have paid suppliers surely they would have done so to avoid default rather than saving money for the HMRC who they are certain to default with.
2) Expected adjusted EBITDA drops another £10m, if recapitalisation successful.
Detailed reasons are given, but this suggests they were hoping / expecting to push through quite a lot of lumpy earnings (like new franchises) in the last few weeks of the reporting year (ending 28th April) and this may have always been optimistic. Also some suggestion that wholesale customers have stopped purchases (whether through destocking or buying elsewhere).
3) Confirmation that if it can't raise funds then they are toast.
Clearly management were completely clueless about what was really going on, their share dealings being proof if nothing else. It seems quite likely that PwC will discover more issues.
The recapitalised CVR would have a enterprise value of £125m raised + £100m debt assuming no value for the existing equity, and EBITDA of £50m (assuming no more nasties). So looking at it simplistically, any valuation above 4.5 EV/EBITDA implies some value for existing equity, anything less implies they are bust.
Taking the best case as 8x EV/EBITDA, this imples a £175m premium. If the institutions target a 20% rise on the first day (again, optimistic), that's £25m leaving £150m for prior shareholders, only a 17% fall. That seems very unlikely.
Statement implies that profits have been overstated for some time.
If restated accounts don't come with the placing, then I'd anticipate a substantial period of even more price weakness. Any institution worth its salt would insist on seeing restated accounts before agreeing to put money in, whatever terms are offered.
Conviviality (LON:CVR)
Following on from/expanding on your point two the RNS states:-
"On the 13 March 2018, Conviviality announced it expected adjusted EBITDA for the year ending 29 April 2018 to be in the range of £55.3 million - £56.4 million. In addition, net debt was expected to be £150.0 million as at 29 April 2018.
Assuming the Placing is successful, the Board would expect that the adjusted EBITDA* for the year ending 29 April 2018 to be in the range of £45.5 million to £46.0 million and net debt to be below £100.0 million. For the financial year ending 28 April 2019, the Board expects adjusted EBITDA* to show modest growth compared to the expected outcome for the current financial year.
The reduction in the expected adjusted EBITDA outturn for the current financial year from that announced on 13 March is principally due to (i) the Company managing its customer and supplier base through the issues associated with its short term funding requirements and (ii) the deferral of franchise income arrangements as a consequence of the Board delaying completion of further franchise agreements."
Adjusted EBITDA has gained a *.
" * References to adjusted EBITDA are stated before the application of International Accounting Standards Board's IFRS 15, Revenues from Contracts with Customers, which is to be adopted by the Company from 30 April 2018. While it has no impact on cash flow, it is expected to have an impact on the recognition of franchise income."
The implication is that EBITDA will fall on adoption of IFRS 15 in FY 2019, even allowing for prior years - can't see how they can get a fund raise off the ground without having these numbers. (IFRS 15 was brought in to promote more conservatism in revenue recognition - to go ahead and produce accounts on the current basis in the current circumstances is crazy).
Still seems a complete mess to me - the more they communicate the worse it seems.
Phil
Xaar (LON:XAR) share price reacted very positively (up 18% at close) to unexceptional results. Perhaps I am getting sucked into the world of conspiracy theories but why do I suspect the price has been forced down prior to the results announcement (see the chart over the last 6 weeks) enabling those 'in the know' to buy immediately prior (yesterday) to the announcement and make a tidy profit!
Softcat seem to be dampening expectations a bit, perhaps partly because share has had such a good run.
e.g in addition to points posted by slopsjon:-
“We will continue to monitor potential impact of Brexit process, although the Company’s focus on the U.K. domestic market means that risk from this is centred round macro economic factors which may impact customer appetite for business investment.”
Share price down over 80p just now but up over 60p yesterday.
Softcat (LON:SCT) It seems to be the Outlook statement that caused confusion.
Outlook
The Board is confident of meeting its expectations for the full year but we have some important months ahead and will remain very focussed on delivering outstanding service for customers.
It also says:
14. Seasonality of operations
Historically, revenues have been marginally higher in the second half of the year than in the first six months. This is principally driven by customer buying behaviour in the markets in which we operate. This increased revenue weighting in the second half of the year has traditionally resulted in higher operating profit in the second half.
I would also like some comment on Airea as I believe the company's management are in the middle of a clearly described, rational and effective turnaround strategy and this is now really showing through in the results. I would tend to agree with the earlier comment that this might be another James Halstead in the making as the current management also appear to be quite conservative in their outlook.
Would be good to get Paul's view on AIEA, a Yorkshire carpet maker whose full year results are out today. Shares up more than a quarter today. Selling its loss-making retail carpet operation to concentrate on its profitable commercial flooring business. Could this be another James Halstead in the making?
Paul,
Hope your dogs are okay. If you have time would like a view on Premier Technical Services (LON:PTSG) which you have covered before.
I posted on Matylda's thread-
"First time I have seen Premier Technical Services (LON:PTSG) and they look very interesting. My main concern is the level of debt
"Net debt at 31 December 2017 increased to £18.3m (2016: £13.6m) following payments of £2.3m of cash in relation to acquisition of businesses. The Group's working capital position has necessarily increased due to the very substantial increased scale of the Group's activities at the period end."
Receivables are up to £32M, which is huge for a company with revenue of £53M. Not checked the interest rate but they appear to continually run a large overdraft whereas presumably a term loan would be cheaper?
Any thoughts on the debt ? "
Thanks, Dave
Hi Paul,
Would also much appreciate some Sherlock Holmes style feedback on Premier Technical Services (LON:PTSG) which on the face of it looks OK...
“Another year of exceptional growth delivering record turnover and profits” - Revenue up 35% to £52.9m (2016: £39.2m), Adjusted PBT up 36% to £10.2m (2016: £7.5m), Adjusted EPS up 28% to 9.73p (2016: 7.63p) with the Final Dividend up by 14% to 0.80p (2016: 0.70p). This year has started well, further acquisitions being considered.
Thanks in advance (woof woof!).
The last time I looked at PTSG I was put off by high receivables and also by the involvement of Bob Morton (a founder of the company I believe).
Mr Morton has been reprimanded by the Takeover Panel multiple times and found himself on the receiving end of its worst possible sanction back in 2017 – the ‘Cold Shoulder’, which prevents FCA regulated bodies from acting for him for a number of years.
Re Premier Technical Services (LON:PTSG) & Bob Morton - well done for pointing that out - saved me a job. Those considering an investment should consider searching for his name on www.shareprophets.com & on Google.
PTSG management come across as being super-efficient. However, the involvement of tainted Bob Morton, and the excessive level of debtors (with unsatisfactory explanation of - we make a high profit margin, so we allow customers to pay us slowly) simply didn't ring true to me.
Take a look at Director remuneration & share options, and what looks like nepotism to me too.
Looks great superficially, but I'm not convinced.
Yep, re Premier Technical Services (LON:PTSG) I couldn't concur more! Nicely summarised too.
Not necessarily a bad idea to follow Bob Morton sometimes. I made a large profit a few years ago when I followed him in buying shares at a low price in a company (sorry the name escapes me at the moment) and then got out right at the peak a couple of minutes after a RNS disclosed that he had sold half his holding. A year later the company was as good as bust. So well done Bob Morton as far as I am concerned!
Yes, Re Premier Technical Services (LON:PTSG) (I didn't give you a thumbs down but you were pushing your luck a bit with a "well done Bob Morton" - he's thoroughly unscrupulous)
Paul Scott makes good money too sometimes trading in and out of companies he is sure are fraudulent* (he did it with Globo for instance). Operators as canny, alert and aware as you and he can make money trading all sorts of dangerous situations: it can work a treat if you get your timing right, stay lucky and don't get caught with the crap you bought when it does actually implode (which usually happens over-night).
But for the benefit of those tempted by the apparent charms of Premier Technical Services (LON:PTSG) and considering a long-term investment you might be interested to know that, according to information on www.shareprophets.com and from links provided there some time ago, that Bob Morton was censured by the Take-Over Panel for serious breaches of the Take Over Code as chairman of Amour Group and then founder-investor in Premier Technical Services (LON:PTSG). The Code requires an offer for all outstanding shares to be made if an individual or group acting in consort owns >30% but <50% of outstanding shares - Bob Morton has repeatedly arranged clandestine sales of shares to each of his four sons etc without disclosure and knowing he is, again, in serious breach of the Rules. My notes from 28/9/16: " Premier Technical Services (LON:PTSG) also took nearly 3 months to report results; it has ropy working capital, excessive share options and material 'adjusted' items to profit, plus net debt - see SCVR, 28/9/16, comment #27 (TMFMayn). Debtors (receivables) also excessive: 141 days!"
* I don't know of any other 'funny business' at Premier Technical Services (LON:PTSG) beyond that just described above and by Paul Scott - I haven't looked.
(No position.)
Just for clarity I am not suggesting anyone speculates on Premier Technical Services - I don't know the first thing about it.
Xaar (LON:XAR) well ahead of consensus EPS expectations according to Stockopedia metrics. Significant cash pile at c. £45m representing in excess of 20% of current market capitalisation. Revenue & profitably growth not great but new product lines starting to make a significant contribution and there is always the ‘holy grail’ of 3D printing. Ink jet businesses in the Cambridge scientific ‘bubble’have been attractive to corporate acquirers in the industry over the last 15 years (Linx Printing Technologies, Domino Printing Sciences) so if Xaar (LON:XAR) products & IP attractive could be a acquisition target. I continue to hold though more in hope than anticipation!
Half year report from Softcat (LON:SCT), looks very strong, but market doesn't like it - currently 12% down. Wonder if it's just pent up expectation due to recent trading update advising exceeding expectations? Anyone have a view?
A bit of profit taking on Softcat (LON:SCT) I think, share price has gone up a fair whack over the last month. Still well above 500p where I was stopped out not that long ago.
Judges Scientific (LON:JDG) video of analyst presentation given yesterday (c.50 mins).
Great overview of strategy. They've had a cracking year. Order book 16.6 wks (v. 14.8 wks 1.1.17). Focus on high margin and ROTIC. 100% cash conversion of op profit.
Full year results presentation for the year ending 31st December 2017 by David Cicural (CEO), Brad Ormsby (CFO) and new COO Mark Lavelle. (c50 mins)
http://www.piworld.co.uk/2018/03/21/judges-scientific-jdg-full-year-results-presentation-20th-march-2018/
David Cicural, CEO
Introduction – 00:17
About Judges Scientific – 00:39
The Judges group- 02:32
Key messages from 2017 results – 3:14
Introduction of new COO Mark Lavelle – 04:12
Brad Ormsby, CFO
2017 results highlights – 06:00
Performance – 08:02
Order intake – 09:22
Revenue summary – 11:19
Profit bridge – 13:06
Balance sheet & cash flow – 13:58
Return on total invested capital (ROTIC) – 15:13
Diversification – 16:44
Financial history – 17:13
David Cicural, CEO
Strategy – 18:04
Growth drivers – 18:34
Acquisitions criteria & delivery – 22:35
Oxford Cryosystems – 26:29
Summary & outlook – 29:27
Q&A – 31:11
Tax – 31:14
US offices – 32:17
ROTIC historical performance – 33:21
Armfield – 37:37
Increasing the performance – 38:45
Cash conversion – 39:33
Selling of business’s? – 42:05
Integrating the business’s (to Mark Lavelle, COO) – 43:22
Non UK acquisitions? – 46:26
Xaar. Not great result on the surface at revenue up 4% for a company on a PE of 22. But not surprised the market likes it currently up 9% . They have managed to shake off the overreliance on the ceramics market. As CEO states: We are making good progress in transforming Xaar to a more diversified and customer centric company. Although we have had some challenges during the ramp up phase of multiple new products, the quality of our business continues to improve. I am particularly pleased that 80% of our product revenue is from new products launched in the last 24 months and acquired business which has helped product revenue excluding Ceramics grow by 23%. We regained share in the Graphic Arts market; our Thin Film technology and our 3D and Advanced Manufacturing sectors demonstrate exciting prospects for the future.
I continue to hold
Morning Paul, updates from PTSG and ACSO today. ACSO looks plain sailing as ever unless I've missed anything; PTSG with lots of bolt-on extra income, and many adjustments to cloud the issue, your experienced eye would be appreciated.
Could I make a request for Personal Group (LON:PGH) please
FY EBITDA £10.8m marginally ahead of market expectations. EPS-cont 26.1 (29.7). Div hiked 3% to 22.7p.
They had some delays through the year "due to the transient issue of the HMRC review into Salary Sacrifice, which delayed sales at our PG Let's Connect business into 2018", and Royal Mail which has now launched.
But I think going forward it looks interesting
Paul I noticed youve sold all your BOO.L stock, have you given up this boohoo, or just waiting to see if it gets out of its rut
Hi ambrosia,
Boohoo.Com (LON:BOO) is nice and liquid, so I've sold most of my stock in real life, and I wanted to use the funds in BMUS to take a decent-sized position in French Connection (LON:FCCN) , which I've also done in real life.
The share price of BOO just wasn't doing what I expected it to do, in the short term, so I've decided to take a wait & see approach, as it's very easy to move in & out of, in reasonable size.
Regards, Paul.
SCS (LON:SCS) interims out this morning.
https://www.investegate.co.uk/scs-group-plc--scs-/rns/interim-results/201803210700033530I/
Achieving single digit like for like growth - reasonable result in the current gloomy consumer atmosphere. Looking at the stock ranks seems to be a good solid company but in a difficult sector. Thinking longer term, may be one of the survivors to profit from higher market share if there’s a shake out of some of the weaker players, especially given general robustness in the housing market.
Gus.
SCS (LON:SCS) seems to have been marked down this morning on a reasonable set of results - Is this more a result of sector concerns than company issues?
As Gus says the stock ranks are good so some additional value as long as there are no issues buried in the interims.
I asked myself the same question about the interims from SCS (LON:SCS) and decided it was a reaction to this:
Interim reported: Like-for-like order intake up 2.2%
Outlook: Sales order intake up 0.9% on a like-for-like basis for the 33 weeks to 17 March 2018
That's a turnaround to -4% in the last 7 weeks
Re. SCS (LON:SCS) and apparent dip in recent weeks, bear in mind there has probably been a fair bit of weather related disruption due to the two more or less nationwide “freeze” weekends. (Reference to this effect is in the company commentary.) I suspect this may impact on a lot of discretionary retail over this period. For once I have some sympathy with them. Would you be out buying carpets in a blizzard?
Gus.
SCS (LON:SCS) business model seems to be working well. The LFL tail off seems nothing structural probably (see snippet from previous year below). Cash of £50m for £80m market cap is quite remarkable. Since 2015 IPO they've moved from £15m cash to £50m whilst still opening a good handful of stores. Note that depreciation runs ahead of investment capital needs as they work some rather expensive and less well judged store opening and long leases from the noughties (they had a mega program about 2006/7 ish).
Some of the cash is working capital but only a bit. They are at least £40m clear (probably more like £45m but I haven't updated my numbers with these results).
Margins are edging up. Peak cyclical op margin likely to be about 7-8%. They are pushing it up at the moment towards 4% in tough environment. Looks like good operational management from team on the ball. House of Fraser is a drag given their tough trading environment and it has shaved a bit off of results reducing shine.
What weighs against it?
1) UK consumer and negative perspective on UK generally. They sell mainly outside SE England to Cs and Ds. That doesn't make good narrative at the moment.
2) As with 1 above and its a small company - so ignored and unsexy
3) Overhang of private equity investors (approx 40% of stock) who wants to exit in the next year or so.
Whatever the narrative background the reality has been good. The stock is exceptional value on p/e and divi of c.8% and putting in the cash means p/e of 4.
They have a target of 30 more stores but disciplined in waiting for the right location (out of town furniture orientated locations).
What the eps upside story?
a) What do they do with the cash? My preference is buy back stock (perhaps the PE overhang). That would be a massive boost to earnings. They may also make acquisitions...IMO that is likely to be driven by the ability to speed up locations that they like so perhaps its a competitor going under or picking up some of the sights of a struggling competitor. I like this less than cash back and organic 30 store opening over next 5+ years
b) UK consumer growth. No ones counting on it but it doesn't stay meh...it goes down or it comes back up. On the former they are robust given model and that they already service the financially challenged. It may actually be a growth source for them with some trade down.
c) Surprise us. HoF strategy was good and diversifying for the business.
I bought at 150p couple of years ago picking up 10% dividend that has grown since then. Obvs its not blown the lights out but I was looking for a double from 150p. I think I'm looking for a double from 200p given progress. With the right moves this can be a mult-bagger and long term hold. Mgt seem to know who they are and what SCS can do so hopefully no rash moves
Here's the LFL from H1 17 report, seems similar to this year:
"“For the 33 weeks ended 18 March 2017, like-for-like order intake growth was 0.9%. This is a pleasing performance against very strong prior year comparatives, and represents a two year like-for-like order intake growth of 12.5%.
Trading in February was challenging, largely driven by reduced footfall. However, we have seen an improvement since the start of March.
We remain mindful that the Group still faces the key Easter and May bank holiday trading periods and faces very strong comparatives during the remainder of the year. The Board believes the business remains in a strong position to maximise opportunities as they arise and to grow market share.
Given the year to date performance of the business, the Board currently expects results for the financial year to be in line with expectations.”
Only if it was a magic one - Imagine that in a blizzard!
But yes, even Ten Pin Bowling venues were affected, and quite a lot - Ten Entertainment - 11 weeks of 2018 started with LFL Revenue affected by weather, 1.7% up instead of 2.8%.
My morning smallcap tweet:
Imaginatik (LON:IMTK), Science in Sport (LON:SIS), Moss Bros (LON:MOSB), Mothercare (LON:MTC), Personal Group (LON:PGH)
Imaginatik (IMTK) sale of co proceeding - "detailed discussions with certain parties about the sale of the Company, with the aim of announcing the outcome of the process by the end of May."
Science In Sport (SIS) FY in line: rev up 28%, pretax -£3.9m (-£2.8m). Outlook "Year has started well...We continue to invest heavily in brand awareness* in all markets, as well as aggressively building our e-commerce consumer database and seeking to improve conversion and loyalty." *This used to be called advertising. Cenkos F/C loss to inc. this FY. Will they ever make money?
Also a separate RNS to trumpet "Olympic Champion Adam Peaty Becomes SIS Ambassador." He's a swimmer. Need to step away from the bicycles after all that unpleasantness.
Moss Bros Group (MOSB) Not even 2 month into FY brings a warning that 2019 profit will be materially lower than current market expectations. Blames shortage of stock after consolidation of the Group's supplier base in response to Sterling weakness. Also those bloody customers are hiring and buying less. "The reduction in store footfall that was experienced towards the latter part of December, has continued."
Mothercare (MTC) discussions with lenders progressing constructively. Covenant tests deferred, preliminary discussions on securing additional financing "to support and maintain the momentum of our transformation programme." Er, because you will breach covenants surely? I'm short.
Personal Group (PGH) FY EBITDA £10.8m marginally ahead of market expectations. EPS-cont 26.1 (29.7). Div hiked 3% to 22.7p.
Hope your dogs are OK Paul.
Don't worry about the market's dogs!
Jon