Small Cap Value Report (Tue 20 Mar 2018) - CALL, PEN, BLTG, GETB

Hi, it's Paul here.
Sorry this is rather late again.
Cloudcall (LON:CALL)
Share price: 165p (down 6.5% today)
No. shares: 24.08m
Market cap: £39.7m
(at the time of writing, I hold a long position in this share)
CloudCall (AIM: CALL), a leading cloud-based software business that integrates communications functionality into Customer Relationship Management (CRM) platforms, is pleased to announce its audited full year results for the year ended 31 December 2017.
This company has been a long-standing favourite of mine, and I'm firmly of the view that it is (at long last) gestating into a decent company. The problems before were that it kept running out of cash. As is nearly always the case with blue sky shares, it failed to meet the original targets. Also, it has taken much longer, and burned a lot more cash, than originally planned.
However, to my mind this company is now very clearly on it way to becoming a decent SaaS business - so think in terms of an earlier stage dotDigital (LON:DOTD) , or LoopUp (LON:LOOP) - both of which soared in value when they reached a tipping point where profitability became assured. The key features for a SaaS business to soar in value are;
- Strong organic growth
- High gross margin (hence lots of operational gearing as revenues rise)
- Mainly recurring revenues
- Low customer churn rate
Those elements are clearly in place with CloudCall, hence why I think it's now looking very interesting.
Here are my notes from skimming over the 2017 results;
- Revenues up 42% to £6.9m - organic growth of 40% or more very much interests me.
- Gross margin up 150bps to 80.0% - very impressive.
- Net cash of £4.9m should be fine for now (but how many times have we thought that before, only to find another placing is done?!)
- Bullhorn relationship is key - maybe it might acquire CloudCall in future?
- Overheads increased again, and set to rise further in 2018, due to beefing up of sales & development teams - this pushes breakeven out further, again.
- Strong growth in 2017, despite cash constraints, before the last placing.
- 2018 outlook - fast growth from Q2 suggested, as new sales team exit training & begin selling.
- New product launches imminent, which should drive incremental sales from existing customers.
- Outlook - strong start to 2018, in line with market expectations.
- EBITDA loss of -£1.9m looks an improvement on 2016 of -£3.0m.
- However, capitalised development spend shot up from £0.15m in 2016, to £0.91m in 2017. Add that to EBITDA, and there was little improvement in cash burn.
- R&D tax credit of £0.6m due to be received in the summer. As this is a material sum, we should probably measure performance using PAT, not PBT.
- Balance sheet looks strong, with sufficient cash.
- Cashflow statement - I make the cash burn £2.6m - the same as in 2016.
My opinion - I can see why some will see these results as glass half full. That's how I see it. For me, the company spending money on better products, and faster growth, is money well-spent. However, other investors might be frustrated that breakeven always seems so near, yet so far.
Broker forecasts have been revised down today for 2018, due to the increased spending to drive growth. However, that should pay off in 2019.
I'm in this one for the long haul, and am very confident it's likely to be a considerable success. You only have to roll the growth figures forward manually, to see that in say 2-3 years' time this could easily be a £100-200m market cap company. It's very difficult to find companies generating 40%+ organic revenue growth, on very high gross margins, and those revenues being monthly recurring revenues.
Admittedly I was about 5 years too early, with my bullishness on this share. But it's coming good, so I'm happy to continue holding for another 5 years, so long as the organic growth & high margins continue to hold. With growth companies like this, it's not about short term profitability. There is a big opportunity to build a much larger business, and it's right that short term profitability is subordinated to properly financing the growth. So this share perhaps suits long-term growth investors better, rather than people looking for a fast buck.
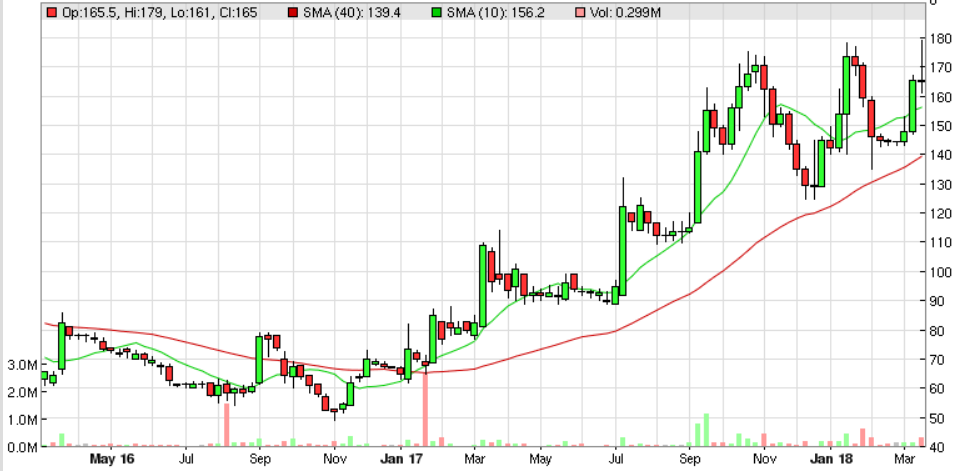
In a time when many smaller, more speculative stocks have sold off heavily, this one remains strong;
Pennant International (LON:PEN)
Share price: 94p (up 13.9% today)
No. shares: 35.7m
Market cap: £33.6m
This maker of simulation equipment seems to be on a roll.
An existing major contract has been extended by £3.5m.
Also, a £10m letter of intent has been received from a potential Middle Eastern customer. Although this is not yet a firm contract, it sounds like good news.
The valuation metrics are already looking attractive, and perhaps today's contract news might lead to further forecast rises?
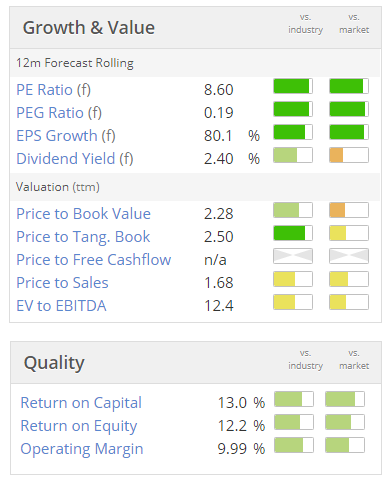
My opinion - this seems a nice company, although subject to the vagaries of large, lumpy contracts. That's fine when orders are rolling in, but can lead to profit warnings when any gap appears in the order book.
I've struggled to get in or out of this share in the past, hence consider it too illiquid for my portfolio. However, for small portfolios, liquidity doesn't matter, so it might be worth considering if you're in that position. The company seems to be a successful operator, in a niche market.
Blancco Technology (LON:BLTG)
Share price: 62.9p (down 2.5% today)
No. shares: 64.0m
Market cap: £40.3m
Blancco Technology Group plc, the leading global provider of secure data erasure solutions and mobile device diagnostics, is pleased to announce its half yearly results for the six months to 31 December 2017.
Just a few brief comments from me, as I can't see anything of interest here. If you recall, this company was beset with problems & accounting corrections, under incompetent previous management. It's currently looking for a new CEO, said to be at an advanced stage.
- H1 revenue £12.6m (2016 H1: £12.8m)
- Adjusted operating profit £0.8m (2016 H1: £2.5m)
- Weak balance sheet, with negative NTAV
- Net debt £3.4m
- Cashflow was heavily negative, at -£5.1m in H1 2017
- No divi
- Outlook statement - waffle
My opinion - I don't see any attraction to this share. Maybe the new CEO can do something positive with the company?
Maybe GDPR might provide a stimulus to the company, as managing data securely is becoming an increasingly important thing? Personally I wouldn't be willing to pay a £40m market cap, just on hopes that new management can make something viable out of what has previously been a complete mess.
It might be worth looking out for any future substantial Director share purchases here. That can sometimes be a precursor to recovery. As things stand though, buying this share would currently be a total punt. I think it needs to strengthen its balance sheet too, which could be a discounted placing on the cards. It's not for me.
GetBusy (LON:GETB)
Share price: 30p (down 17.8% today)
No. shares: 48.4m
Market cap: £14.5m
2017 full year audited results
GetBusy plc (AIM: GETB), a leading document management software business, is pleased to announce its audited results for the year-ending 31 December 2017.
We don't have anything in our archive yet for this company, which floated on AIM in Aug 2017. Although I recall having a quick read of its admission document when I was bored, one weekend last autumn. So I have a "potentially interesting" mental note of it.
- Revenue growth of 20% in 2017, to £9.3m, most of which is recurring (i.e. good)
- Adjusted EBITDA improved from a -£1.7m loss in 2016 to a -£1.2m loss in 2017.
- Stripping out the IPO costs, it made a loss of about £1m in 2017. This seems to be a long way below the forecast shown on Stockopedia of a net profit of £1.0m.
- There might be some confusion over performance against forecast. I'm reading a broker note out this morning, saying the IFRS 15 has impacted the results negatively. On the old accounting basis, the broker says its forecast was beaten.
It therefore seems that IFRS 15 is a big issue. I should probably do some reading up on it.
My main concern with GetBusy is its weak balance sheet. Whilst there is £2.8m cash, this has more than all come from up-front payments by customers of £3.95m (deferred revenue creditor). The problem with this, is that deferred revenue can move about during the year, which might mean that cash could be tight at another point during the year. This looks to me like a company which needs to do a placing to strengthen its balance sheet.
My opinion - I like the growth, and the high margins, and recurring revenues. So it ticks the boxes which I mentioned above as being things to like at SaaS companies.
At a guess, it looks like another company which might benefit from GDPR.
On the downside, I'm not keen on the weakish balance sheet.
Overall then, it goes on to the watch list, as something which might be worth keeping an eye on, for a possible future purchase. I'd rather wait until its balance sheet is a bit stronger, and it's moved into profit (or closer to it than at present).
That's it for today, see you at some point tomorrow.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

105 comments
I was going to let the subject of IQE (LON:IQE) lie, but I've spent a bit of time on this now and before I do I am aware I've made encouraging statements on the long-term potential of photonics (in relation to a broad industry that will eventually replace micro-electronics, rather than the narrower impending applications IQE (LON:IQE) has in mind, such as for 3D sensors for smartphone face recognition) that could give a distorted view of the risk and only state the upside. So I wanted to point out a few things about IQE (LON:IQE) (I have no position):
IQE (LON:IQE) was founded in 1988 (and floated in 1999). It's entire history has coincided with an almost unimaginable boom in micro-electronics. In the meantime it has been buying up other companies and other people's intellectual property, so it bloody well should be the global leader in its field that it says it is (and which I don't question). Like any commercial business, IQE (LON:IQE) is first and foremost in business to make money, only IQE (LON:IQE) hasn't been very good at it. After all this time, and many, many, innovations and opportunities in the industry it STILL. IS. NOT. MAKING. DECENT. MONEY. Meanwhile, the chipset designers got minted and became household names, but I am yet to buy a computer that tells me it has "IQE Inside" - not one of the computer companies think there is added-value and a brand advantage to be gained by explaining that the substrates for their integrated circuits have been lovingly made by IQE. Nor does IQE (LON:IQE) seem much to need making a good profit since their directors are happy to fill their own pockets ahead of company coffers and to get rich on share options and a hyped share price.
At this stage, I think I would sooner buy a producer of bulk commodity plastics, so long as it was run by competent and honest management. At least its business would be easier to understand, its position in the market easier to establish independently and less at risk of sudden disruptive displacement. Nor would such a business make a pretence of doing anything other than supplying a commodity item. My advice to anyone on IQE (LON:IQE) that wants it given it's fairly long-established track record: make sure the profits are real and sizeable before you invest.
Hello Paul,
I agree with your sentiments entirely re. CALL.L; however:
".....
Broker forecasts have been revised down today for 2018, due to the increased spending to drive growth. ....".
I can find only one broker's note on this company, that of Arden Partners (initial forecast of GBp 300 on 7th February 2018) and re-iterated yesterday, 20th March, unless I am mistaken.
Are the others to which you refer generally available please?
Thanks.
Bob Pond
Re IQE (LON:IQE)
What they are doing is epitaxy. That’s clear from their website. In such a highly technical field it is not possible to know how much protection they have by way of IP from potential competitors because all companies will have a multiplicity of unpublished trade secrets on top of any public domain IP such as patents, even if evaluating the merit of individual patents in this field is within one’s skill set.
What surprises me is how much people fret about competition in this high tech area where there obviously is some IP but are then quite happy to invest in companies in other sectors where there is no IP protection at all.
The most important thing to know about the photonics market is that it is growing massively and thus all companies that serve it are likely to do well for the next few years. Additional to that, the most important thing to know about IQE is that not only are they the go to company for wafers for this photonics market (which is not just Apple iPhone X by the way) they are also well placed for the nascent 5G market and many other applications.
Once that is accepted then it is a question as to whether or not they can make money doing so. Whether one believes they can or cannot largely depends in my view on whether one believes that the “adjustments” are mostly one offs or small enough to be unimportant long term, or if adjustments will continue to hold profitability back long term.
Disclosure: I hold a long position.
Re IQE (LON:IQE) I agree with much of what you say, Graham. My focus on competitors and competing semi-conductors and manufacturing processes is in light of considering an investment ahead of decent profits. I do know enough about this to know that others 'do epitaxy'. Anyone making single-crystal wafer barstock does epitaxy, for instance. The majority of those will likely have the same kind of background that IQE (LON:IQE) does in coating wafer substrates too - the same kind of experience that led IQE to deposition of semi-conductor layers by epitaxial deposition. My guess is that IQE's best hope of ring-fencing market share is probably via robust patents rather than know-how that others don't know, which may not last too long given the huge scale of long-term global research in all these areas. So, as you say, to answer those points needs advice from industry specialists and a patent lawyer. Electronic materials is one of the most intellectually challenging fields I have ever encountered (far harder than anything useful in investment and finance).
Of course, most of us (myself included) rely heavily on Company management convincing us that they are much better than the competition, but usually in such cases we wait for accounts that back up their confident assertions.
(No position.)
Re. CALL.L:
".....
Broker forecasts have been revised down today for 2018, due to the increased spending to drive growth. ....".
I have seen only one broker's note on this company, that of Arden Partners (initial forecast of GBp 300 on 7th February 2018) and re-iterated yesterday, 20th March, unless I am mistaken.
Any ideas about others please?
Thanks.
Hi Ed Miller,
Here are some links you might find relevant to IQE's technologies, some of which might hurt your brain to understand, but I'm not sure they'll tell you something financially useful:
http://www.iqep.com/about-iqe/our-core-is-business-is-epitaxy/
https://seekingalpha.com/article/4053636-iqe-plc-focus-photonics-vcsels
https://www.rp-photonics.com/surface_emitting_semiconductor_lasers.html
http://csmantech.org/OldSite/Digests/2015/abstracts/100R-
6-inch%20VCSEL%20Wafer%20Foundry%20Economics.pdf
https://www.google.co.uk/search?q=vcsel+fundamentals&rlz=1C1LENP_enGB662GB662&oq=vcsel+fundamentals&aqs=chrome..69i57.4711j0j8&sourceid=chrome&ie=UTF-8
https://www.azom.com/article.aspx?ArticleID=11585
https://www.researchgate.net/publication/260403078_Optical_Physics_of_Quantum_Wells
Re Cloudcall £1.85m of RCF it me or is 7.45% very high I would expect 2 or 3 above base ?
Anybody have any thoughts ?
.
On 11 July 2017, the Company agreed a revolving credit facility with Barclays Bank for an amount of £1.85m
which expires on 11 July 2020. Interest is set at 7.45% above base rate and the non-utilisation fee is set at
2.98%.
It seems GetBusy (LON:GETB) have decided to adopt IFRS15 a year earlier than they were required to, so it's interesting to read the impact on their accounts as it may provide an early pointer to how it will affect other companies.
In this case, their deferred income balance is £1.0m higher than it otherwise would have been, which is a pretty large figure in the context of revenues of £9.3m. Presumably most of that £1m would have been recognised as income were IFRS15 not being applied, although I'm a bit confused in that they say the impact on their income statement is only £53k. I think some of that difference must relate to prior year restatements.
The biggest change appears to arise from their consulting income where they do implementations for their customers. Previously this income was recognised up front when the work was done, but is now being lumped in with their licensing and support contracts, so has to be spread over the license term of 3 years.
So less income recognised up front and more income pushed into future years and a move further away from cash accounting. This is going to affect a lot of ratios from PERs, ROCEs, cash converstion, margins, EPS...
On Cloudcall (LON:CALL), can someone point me to where I can find more information about the commercial agreement between Cloudcall and Bullhorn?
As they're seemingly a very important lead generator for Cloudcall products, I want to do a bit more digging to see what sort of commercial teams the deal has been structured, and also if any financial engineering (forward sales, revenue recognition, etc) is taking place from Bullhorn generated leads.
Bullhorn looks like a saint coming as a saviour to Cloudcall's need to drive growth, I just want to make sure the interests are aligned long-term.
The valuation of GAME Digital (LON:GMD) looks very tempting at these levels especially with the sell off today. Cash seems to be quite close to the market cap and the company doesn't have pensions or debt. Given that most of their leases are up for renewal in the next couple of years I'm certainly interested in what they say about closures next week.
Mortgage Advice Bureau (LON:MAB1) reported full year results today. These appear in line with the Jan trading statement though EPS is ahead. Most everything is ahead low double digits. Somewhat unusually, the MAB adjusted EPS only strips out 2016's exceptional gain on sale of a subsidiary. Share based payments were £670k (2016: £315k) (from note 6) but are not excluded from the adjusted EPS calcs. There are some potentially interesting developments in the pipeline. Direct to consumer marketing is due to begin testing in Q2. It looks like last year's hire of a head of the protection business (insurance etc.) is looking to standardise a review of protection into the mortgage process (https://www.moneymarketing.co.uk/issues/8-march-2018/mortgage-advice-reform-boost-protection/). There are also reportedly technology improvements in the pipeline for this year to reduce paperwork. They also seem to be experimenting with phone and robo-advice delivery.
Company says it's trading in line for 2018. It looks like Zeus have taken 2019E EPS down about 5% on the back of a "material" increase in IT investment though that only seems to explain about £300k of a £1m(ish) movement.
Re IQE (LON:IQE) - Apple are supporting a large VCSEL investment by Finisair in Texas. To be expected as they would never be happy being dependant on a single source.
https://www.apple.com/newsroom/2017/12/how-apple-and-finisar-are-transforming-the-future-of-this-texas-town/
I may be mistaken, but from the article it doesn't sound as though Finisair are intending to make wafers but VCSELs. If they're not making the wafers, then they'd need to get them from a company like IQE in order to make the VCSELs.
@Glorenfeld
This article says it's a 6 inch wafer fab.
"Optoelectronics company Finisar is to expand its VCSEL production capacity dramatically next year, with more than $100 million of investment earmarked for a 6-inch wafer production fab in Sherman, Texas.
The facility, a short drive from the company’s existing VCSEL wafer fab in the Dallas suburb of Allen, has been acquired to address what Finisar’s CEO Jerry Rawls anticipates will be “gigantic” demand for VCSEL arrays in 3D sensing applications."
http://optics.org/news/8/12/14
@John Eustace
I think there may be a case of some confusing terminology here. As I understand it, and somewhat counter-intuitively, 'wafer fabrication' is the process of turning wafers into circuits for components (generally using lithography). What IQE do is to manufacture/grow the substrate that is subsequently processed in a fab.
Edited to add that it may be the case that Finisair is going for a fully vertically integrated epitaxy to component operation, but I don't think that's evident from the press releases that have been put out (and seems to me to be somewhat unlikely).
I think Finisair are a vertically integrated competitor to IQE, but we're reaching the limits of my knowledge so I'll refer to a Dave Sweeney post on iii.
He thinks Finisair will struggle, but I noted a comment from them that they have hired staff with experience of making 6 inch wafers, so my guess is some IQE US engineers got offers that were too good to refuse.
http://www.iii.co.uk/investment/detail/?display=discussion&code=cotn:IQE.L&it=le&action=detail&id=12194513
Ah - in that case thanks for taking the time to correct my ignorance :) The Apple investment looks rather different in that light...My initial feeling that it was unlikely to be vertical was borne out of a similar ideas about the logic of doing so that Dave Sweeney's post seems to suggest. Given that Apple are investing heavily, it seems like that initial feeling might well be unjustified.
Apple already have made very serious commitments to build up their presence in the design and production of components by their interest in Toshiba's chip business:
"Toshiba Reaches Deal With Bain-Apple Group to Sell Chip Business"
https://www.nytimes.com/2017/09/28/business/dealbook/toshiba-bain-apple-chips.html
They have the money and it wouldn't be surprising to see them invest in a vertical supply chain.
Jane,
I was going to say Apple would be going a long way down the supply chain to get as far as IQE and if they went any further they would be buying mines. Then I remembered reading they are in fact negotiating to buy cobalt direct from miners!
I still think it’s a matter for them of having security of supply from multiple sources for such a key technology. But the day they think they can do it better in house that could quickly change.
http://fortune.com/2018/02/21/apple-buy-cobalt-miners/
"He thinks Finisair will struggle, but I noted a comment from them that they have hired staff with experience of making 6 inch wafers, so my guess is some IQE US engineers got offers that were too good to refuse."
Isn't that very similar to the scenario that lead to Apple taking in-house what they had formerly procured from Imagination?
1) The 6 inch wafers they are trying to design/build that they can't do today are heavily protected by patents. If Finisair have employed IQE US engineers they will have to avoid patent or license it from IQE (more likely).
2) Finisair CEO said that they can't possibly even meet their own demand in an industry opportunity he describes as gigantic and worth some potential $5bn (I think) so the opportunity here is not for one player necessarily. There is plenty to go around. There will be 2 or 3 in the market. Leadership is key and IQE own 90% of the market currently and will own less market share eventually, but even if that goes down to 30% and the market is $5bn that is $1.5bn of revenue (30* higher than what they just did in photonics alone)
3) IQE doesn't rely on Apple like Imagination did and comparing the two from a tech point of view is an apples and oranges exercise. Specialism in this area is key.
David, Re IQE (LON:IQE)
"The 6 inch wafers they are trying to design/build that they can't do today are heavily protected by patents. If Finisair have employed IQE US engineers they will have to avoid patent or license it from IQE (more likely)."
I don't know how easy or otherwise it might be to circumvent those patents with an alternative semi-conductor (perhaps just a minor tweak; perhaps not) or a slightly different approach to growing the single-crystal. I'd need an industry-insider's view on it or, at the very least, a cogent explanation from IQE themselves. If they are superb at writing patents that ring-fence generic technologies/approaches without being overly specific they might be able to corner a large part of the market for themselves, though I'd be surprised. As I've said, my hunch would be that their photonics microcomponent-fabrication patents would be a lot more valuable and more effective at ring-fencing valuable market share. I'm sure I'm not being too subtle in my suggestion that to focus on wafer production is not to focus on where the highest value is.
David
IQE supply 90% of the "outsourced", market currently. There are at least a couple of vertically integrated companies out there that fabricate the wafers and also make the chips, namely...
Finisair
11-V1
IQE supply the following companies with their wafers for them to make into chips...
Skyworks
Qorvo
Lumentum
Oclaro
Malcom
Macom
Himax
Raytheon
Philips
Please double check the above as they have come from notes that I made about 7 months ago and I may have made a mistake.
I read the 2017 RNS this morning and came away quite positive about my holding here. However, there have been some rather pessimistic feedback so I looked again to see if I had my rose tinted glasses on. Some notes I made are here....
Total revenue £154.5m (2016 - £132.7m) +16.4%
Adj. op. Profit £26.4m (22.1m) +19.2%
Wafer revenue £152.6m (£126m) +21.1%
Wafer adj. op. Profit £24.5m (£15.5m) +58.4%
Licensing £1.9m down from £6.7m last year -71.9%
"IQE delivered outstanding performance in 2017. Wafer revenues were up 21%, propelling adjusted operating profit from wafer sales up 58%. This reflects the high operational gearing in our business, and a more profitable sales mix.”
“Photonics revenue expected to grow c.35% to 60% in 2018” ...
...“Expected Compound Annual Growth Rates over the next 3 to 5 years, based on current products, in the ranges of: Wireless up to 10%; Photonics 40-60%; and InfraRed of 5-15%. Potential for higher growth with new product introductions” Mybold.
…“Potential for strong growth in 2019 and beyond. Increasing VCSEL adoption for 3D sensing expected to accelerate across multiple smartphone OEMs, introduction of world facing 3D technology, and first deployment of LIDAR and several other high volume sensing applications”
Measure of 2018 profit will be met by wafer sales as license fees tail off however, licensing fees could become a feature in future years as they leverage their “over 180 patents.”
...”5 tools are now in-situ and on track for production in H2 2018 as expected, and a further 5 tools are scheduled for installation and commission by end Q3. Preparation is underway to acquire at least a further 10 tools within the next 12-18 months as demand requires.”
The following really impressed upon me the scope of IQE's capability...
“However, we are not resting on our laurels. IQE's expanding portfolio of intellectual property, including over 180 patents, is enabling the group to differentiate itself in the marketplace, and strengthen its business model by not only being the global leader of choice in the supply of advanced semiconductor wafers, but increasingly able to provide comprehensive "advanced materials solutions" providing chip designers with a new "toolkit" to develop chips which push the boundaries of performance, enable higher levels of integration, and reduce the barriers of cost.
A couple of examples illustrate the power of this strategy:
Wireless "Front End Modules" - The Front End Module (FEM) refers to the communications module in a smartphone. It is the FEM that performs all of the wireless communications. The FEM is made up of many individual chips, which can essentially be grouped into Filters (for filtering out undesired wireless frequencies), Switches (for high speed, high efficiency switches), and Power Amplifiers (for high efficiency amplification of wireless signals). Each of these three types of chips are made from different semiconductor materials technology. The sweet spot for IQE has historically been the Power Amplifier, but it has also developed the technologies for Switches (SOI) and for Filters (AlN). Armed with its patented cREO technology, IQE has a clear route to combining these three material systems on a single wafer, which paves the way for the complete integration of the FEM on a single chip. This would be highly disruptive. A FEM solution on a single chip would be more efficient, with a smaller footprint at a dramatically lower cost of production.
3D sensing solutions - tear downs of the first 3D sensing solutions show a combination of advanced technologies in a complex module: a VCSEL light source, optical components, and silicon sensing components. Again, IQE has the underlying materials technologies for these components, and the benefit of several patents including Quasi Photonic Crystals and Nanoimprint Lithography for wafer level optics and diffractive optical elements. So again, with its advanced technology, IQE has a route to integrating many of these technologies on a single wafer. This would be highly disruptive as it would result in a 3D sensing solution on a single chip which would again be more efficient, with a smaller footprint at a dramatically lower cost of production.” Again my bold
In conclusion
We have operational gearing with higher margin VCSEL wafers going gang busters at circa CAGR of 40% to 60%, many more CS wafers in the process of being proven and the kind of IP and technological know how to achieve the above combination of applications on a single chip.
Thanks for all the detail on IQE (LON:IQE) kalkanite re smartphone Front End [Communications] Module on a single chip and Quasi Photonic Crystals and Nanoimprint Lithography for wafer level diffractive elements, do you or any other readers know the status of competitor technologies or good sources briefing on current research status please? While we wait for large profits to show up, I'm particularly keen to understand the technical status of competitors, their patented technology and the field as a whole.
There's a guy on Discussthemarket.com called Dave Sweeney whose posts are worth looking up. He has, amongst other technical analysis, looked at the strength of IQE's moat and found it considerable. Apple have been rumoured to be investigating setting up their own large scale wafer VCSEL chip manufacturing facilities, but IQE's head start is substantial. Besides, IQE have multiple customers across numerous applications for their products, so Apple isn't the only fruit in their basket.. The one bone of contention with IQE of course is the 'jam tomorrow' principle is constantly being extended, meantime, no dividend and seemingly over-amply rewarded directors. Hopefully, that vintage jam will be worth the wait?
Hi CliveBorg,
Actually Dave Sweeney posts on iii's IQE discussion board rather than Discussthemarket.com. I agree with you that he is very knowledgeable about IQE's technologies and customers, although he is a medical doctor rather than an electronics engineer by training. He is incredibly optimistic about IQE's prospects, and he claims to have a very high percentage of his portfolio invested in IQE's shares, so one should read his posts with those things in mind. He also posts regularly on ADVFN's IQE discussion board using the name Sweenoid.
Thanks pka & CliveBorg,
Yes, John Eustace mentioned Dave Sweeney's name & his iii posts in a comment above, and I was thinking I should wade through the murky bulletin boards to see what light he might shed. Useful to know his background thanks pka. I probably won't buy IQE (LON:IQE) for all the reasons I've given, but coming at this from a materials science background (I only studied electronic materials as part of my degree, I've not worked in the field, as is apparent I think) I am intrigued as to why the focus on wafer production as opposed to the micro-fabrication technologies that IQE (LON:IQE) has.
Hi Ed
I would also like to know the competitors status and IP, unfortunately this is tightly held throughout the industry as companies vie with each other to get ahead of what is becoming a massive industry.
IQE certainly seem to be ahead of the game but give little away in terms of their technology. I thought yesterdays RNS was quite revealing, they clearly seem to want to draw a line under the recent shorting activity hence revealing their ability to combine different technologies on one chip, that sort of tech does not happen over night.
Re IQE (LON:IQE) Thanks kalkanite,
Yes, though some of the technology moves very quickly, none of this happens over night, and it doesn't spring up in someone's garage. Even in photonics, there was plenty of good research being done in the 90s. IQE (LON:IQE) won't be the only ones with good technology. To me, they appear to be fishing in the low end of the value chain in focusing most of their efforts on wafer production, when they have other higher-value technologies that are easier to ring-fence. Having said that, being the first to supply a rapidly growing market can be all that's needed to make a load of cash. I probably won't invest but I am intrigued about their strategy and the state of the photonics field generally, so I might dig a bit deeper.
Hi Ed Miller, you wrote about IQE: "To me, they appear to be fishing in the low end of the value chain in focusing most of their efforts on wafer production, when they have other higher-value technologies that are easier to ring-fence."
I have no great technical expertise in this field, other than a degree in physics many years ago, but (from what I've read) producing wafers for compound semiconductors seems to be much more difficult technically than producing silicon wafers. This is particularly the case for compound semiconductor wafers for VCSELs, which may require up to hundreds of tiny layers of different materials. Producing reasonably large yields of wafers of sufficient quality for the VCSEL manufacturers is not easy, and IQE seem to have a better mastery of that technology than most of its competitors.
Re IQE (LON:IQE) Thanks pka,
I cannot see how or why anyone would produce seeded single-crystal wafer barstock by laying down hundreds of alternating micro-layers for each wafer prior to the wafer being cut. My understanding is that these alternating micro-layers (it's probably more correct to call them nano-layers, but no matter) are deposited onto a monolithic semi-conductor wafer, after it has been cut, using micro/nano-fabrication (additive manufacture) techniques. It might well be that [epitaxial growth] of single-crystal barstock is more difficult in some semi-conductors than in silicon (very probably so), but I've no idea at this stage what alternatives there are to the semi-conductor/manufacturing process(es) chosen by IQE (LON:IQE) and how well or otherwise IQE's patents close down the possibility of competition. Anyway, I'm a layman so I'll look into it out of curiosity and nostalgia for my previous profession (sadly it never was a career, but that's another story!) as a metallurgist/ materials technologist, but investors/potential investors should not assume the IQE (LON:IQE) technology is unique, ring-fenced and without viable alternative unless they have access to specialist knowledge confirming so.
Hi Ed Miller,
You wrote about IQE: "I cannot see how or why anyone would produce seeded single-crystal wafer barstock by laying down hundreds of alternating micro-layers for each wafer prior to the wafer being cut."
My understanding is that IQE does exactly that. I assume the reason is because it's much cheaper to do this on the whole wafer rather than on each individual component after the wafer has been cut.
Re IQE (LON:IQE) compound semi-conductor wafer manufacture for VCSELs - thanks, I'm surprised, and if so there will still be much valuable nano-manufacture required to produce their optically-active semi-conductor junctions on their VCSEL chips, so I'll look into it.
Hi pka,
I've been having a bit of a delve into the iii IQE (LON:IQE) discussion cess-pool and it has left me feeling a little dirty and not much better informed yet - makes me even more appreciative of the contributors here and reminds me of why I don't go there any more. I'll keep reading, but so far I've yet to read anything that could not have been pushed out by IQE's marketing department when what I want, ideally, is a literature review of the various technologies of IQE (LON:IQE) and its competitors and their routes to market, written by a competitor scientist or engineer, or an academic - the sort of thing that will hurt my brain to understand but will actually tell me something financially useful.
"...when what I want, ideally, is a literature review of the various technologies of IQE (LON:IQE) and its competitors and their routes to market..."
As a starting point, your best bet is probably a 42-page Stifel analyst note authored by Lee Simpson in August 2017. It contains a good deal of technical information as well as a discussion of IQE's competitors.
I don't think it was ever meant to be made publicly available so I won't link to it here, but if you do a Google search for 'iqe stifel note' you should find a link to a comment on iii where the poster (monty1965) gives a URL to the document. I've just checked and it's still openly accessible.
Re IQE (LON:IQE) Thanks Luthrin (& pka too) - the link to the Stifel research report is still openly available as you say.
Re IQE (LON:IQE) compound semi-conductors, for what it is worth, my reading so far indicates that IQE (LON:IQE) is applying layers (such as aluminium nitride in the case of wireless filter applications for smartphone Front-End Modules) by epitaxial deposition (rather than the conventional sputter coating) to monolithic single-crystal wafer substrates. I would expect that be be far superior to sputtering and more difficult to do. I would think they have patent cover but I don't know if that is sufficient to prevent competitors doing the same, and unless the patent is water-tight competitors will start doing it now they know IQE (LON:IQE) are.
On another matter John - that of Burford Capital (LON:BUR) - and I'm reluctant to admit it whilst I'm still interested in buying more shares, I bought an initial position after digging into it over the weekend, as you'd suggested, though I wish Berenberg had kept its bloody mouth shut until after I'd finished buying! I would have liked to have bought more if I'd had the cash. Who knows though, perhaps the placing just announced, and a market drop, could provide a good buying opportunity (- please send cash in case - I'll be most grateful, thanks!). Anyway, thanks to you and other advocates for the suggestion.
Yes I expect Burford Capital (LON:BUR) will open lower after that placing. It’s annoying when great results are followed by insiders selling but I can hardly blame them even if it does tend to put a dampener on things. If not now, when would they be able to cash some in?
Glorenfeld, Re IQE (LON:IQE) At face value, 'wafer fabrication' would mean just that: supplying 6" single-crystal wafer for further processing to make microchips (which sounds like a major part of their business), but on their website and in their annual report IQE (LON:IQE) say they have businesses that fabricate micro-circuits via lithography, as well as fabrication of micro-components, including 'exotic' photonics components. I haven't explored revenue mix/segmental info etc.
in reply to paraic84 no45 above,
know v little about the company but tend to go for family run concerns, been looking on rte for broker comment but can't find any, v strong balance sheet and reasonable outlook and record, v few shares in the free float so could be volatile, might grow into the valuation if this is a cyclical upturn, or receive an agreed takeover bid eventually as eg Fenner today?
Looks like it’s as you were regarding GYM (LON:GYM) a positive update but a muted/expected response from Mr Market. Will take a bit more to move the needle in the right direction. They mention some new initiatives, will need to keep a careful eye on continued growth.
Might be outside your remit but interested in what's going on at DLAR today? Seems like an extreme reaction to the news that the CFO is standing down?
Judy
Anybody know what the market didn't like about Cloudcall (LON:CALL) results today? Looks on track to me (Revenue 6.9M +42% as expected from Jan trading update, and loss narrowed)
Not small cap but I wondered if you had a view on the Aviva preference share proposals? When is an irredeemable share actually irredeemable if a court can set it aside on request under the guise of "capital reconstruction"?
David,
Aviva (LON:AV.) Aviva prefs.
There is quite a reasonable explanation here: https://www.aviva.com/investors/credit-investors/Additional-information-for-preference-shareholders/
If you are a holder, I sympathise, and suggest that you write to every single fund manager in which you hold shares (pensions, investment trusts, units, etc.) complaining vigorously and asking them to vote against.
Of course, ordinary shareholders may regard these prefs as ridiculously expensive and welcome their cancellation (if it happens).
Regards,
Richard
They are expensive but I daresay they were priced right for the time when they were issued.
I think this is the thin end of a pernicious wedge for all investors. How long before other companies use this route to get out of their obligations to shareholders and bondholders? And how long before we can't be sure what we think we are buying is in fact what we are buying if "irredeemable" can become redeemable at will? Very concerning.
Re Aviva (LON:AV.) : "irredeemable" can become redeemable at will
- That sounds scary. And outrageous.
There's a nice little thread on here about the possible redemption of these Aviva preference shares...
https://www.stockopedia.com/content/aviva-and-the-current-price-collapse-of-irredeemable-preference-shares-336348/
David, re: Aviva preference shares
There is a lot of very useful information here
https://www.fixedincomeinvestments.co.uk/discussion/topic/aviva-scheming-to-redeem-preference-shares-at-par/page/4/#post-1883
Mark Taber who seems to host this site also provides a lot of good information on Twitter.
I am also a holder of the Aviva preference shares. Interestingly Ecclesiastical Insurance (who also have preference shares) have confirmed that they have no plans to cancel theirs and have criticised Aviva strongly for their plans.
The fact that something is legal does not mean it is an okay thing to do. C.f. E.g. Paul’s recent comments on directors who lost a vote on taking their company private (at a low price) and then got the shares suspended by sacking a NOMAD and failing to find a new one. Probably not illegal but definitely immoral.
My thoughts on Aviva:
1. If it says “irredeemable” on the tin that should mean irredeemable
2. The price at which I bought my preference shares reflected the fact that they were considered to be irredeemable. Had I known that they could be cancelled I would have bought at a much lower price or not at all
3. If an insurance company looks for loopholes to allow it to cancel irredeemable preference shares, what trust can there be that it will treat its clients, bond holders and ordinary shareholders in a fair way
4. The suggestion (above) to write to other fund managers who may hold Aviva shares makes a lot of sense
BOO
Reporting: 28-Feb-14 28-Feb-15 28-Feb-16 28-Feb-17
Revenue (£m): 109,791 139,851 195,394 294,635
Revenue rules, Damian. When revenue grows like this costs and margins are entirely under management control.
Amazon is a good comparator. It's a land grab and you don't let competitors crawl under the wire.
Like many I can't figure out BOO. The story has not changed and to give away a bit of margin to grow the business is neither here nor there in the longer term scheme of things. You can't integrate/grow two new businesses (PLT/Nasty Gal) or get the new giant warehouse fully sorted for free. Certainly we are now much more in risk on mode than when the sp topped out at near 270p.Big contrast with ASOS which seemingly can do no wrong.
Canada Pension Fund published a 0.5% short on BOO, six days ago.
Results due 25 April.
Paul, at some point I would value your observations about BOOs relentless share price weakness.
I can find nothing in the story that has changed and the margin argument is thin
gruel.
Given your background I can think of nobody better to comment - flattery will get me everywhere :-)
Seriously, I bought when you first explained the business. Up until then I had a 'no shops' rule.
apad
I've been doing some fairly detailed analysis of Boohoo.Com (LON:BOO) recently and broadly speaking I agree with your assessment. Right now their margins are being hit by a number of cost pressures such as increased advertising, spending money on additional warehouse space that isn't fully utilised and growing the two new brands (PLT and Nasty Gal). In addition growth within the core brand has moderated slightly although not hugely. So right now all of the costs are going against the company.
However analyst forecasts still point to high top-line growth and, to a lesser degree, bottom-line growth. So I believe that Boohoo.Com (LON:BOO) are doing exactly the right thing by investing for the future but the costs are making them look less attractive in the present day. That said I'd like to see falling margins and rising costs both stabilise at a sustainable level since extrapolating recent trends in both of these areas doesn't look too pretty.
Either way we'll only get some up to date numbers when the results come out. That's the time to make an informed decision.
Damian
Can I add my request for Paul’s thoughts on Boohoo.Com (LON:BOO). At the time of the last trading update (11 January) you were still very positive. And that trading update raised its guidance on revenue growth from 80% to 90% and gave some clear indications of expected EBITDA margins. Since then the share price has continued to slip and you have sold out of your holding on BMUS. Is there more information or further thinking? Are you following the Minervini advice to trust the market and always sell when the price does not go the way you expect it to go?
My own view is the softening in the share price partly reflects softening we're seeing in the share prices of other high growth companies (e.g. like Purplebricks (LON:PURP) or to a lesser extent £G4M), especially where there has been some news that costs or some other even minor spanner thrown into the overall growth story.
It smacks somewhat of desperation to go back 20 years in order to attempt to disparage IQE . My involvement is much more recent with a first investment at 20p in 2011. Today's IQE report is lengthy and I haven't digested it all, but the outlook includes ...Expected Compound Annual Growth Rates over the next 3 to 5 years, based on current products, in the ranges of: Wireless up to 10%; Photonics 40-60%; and InfraRed of 5-15%. Potential for higher growth with new product introductions." Surely this is highly relevant to the investment case and explains the present uncomfortably large p/e.
Re Cloudcall (LON:CALL) (which I don't hold) TechMarketView's daily email (http://www.techmarketview.com/ukhotviews/) is positive about progress and prospects. Their opinions are usually worth considering as part of DYOR.
any views on Mincon, a small Irish engineer of drilling consumables previously reviewed by Graham, came out with good results today and shares very largely held by family and one or two institutions?
Hi mw8156. I follow Mincon (LON:MCON) but don't currently hold. The revenue growth looked good today although fairly consistent with (previously revised) expectations during the year. This is not a sector I know very well so the key question for me, given this is trading on a high PE, is how much more growth can we expect? (They mention this is probably the start of a new upcycle). They say today's acquisition means they will have revenue of 120m euros even if there is 0% growth so that's encouraging and good to see they are using their huge amount of cash at long last. However, they also warn growth might not exceed single digits in the first half.
So if we conservatively guesstimate that EPS increases by c.30% in 2018 then that would put it on about 5.5p and a forward p/e ratio of 22 for 2018 which could be on the pricier side. Given how small this share is and the spread, I would want to understand more about the outlook for the mining and construction industries at the moment before buying back in.
One thing I didn't understand is why the net profit attributable to shareholders is significantly lower than the overall profit increase. Any idea why? Shouldn't it be consistent or have the number of privately held shares increased?
It seems to me that IQE's short-term profits are being held back by its capital investments to support rapid growth in demand for its epiwafer products in various sectors. The following extract from IQE's results announcement today is relevant to this:
"Capacity expansion
In November 2017, IQE announced the placing of 67.9 million new ordinary shares, raising gross proceeds of approximately £95 million. The fund raise was primarily to finance a capacity expansion programme to deliver the scale needed to capture multiple high growth market opportunities. Of immediate significance is the ramp in demand for VCSELs. In addition, the fund raising is enabling the acceleration of product development.
At the heart of the capacity expansion is the creation of a new foundry in Newport, South Wales. This 'Mega Foundry' will house up to 100 tools, creating a facility with unparalleled capacity and economies of scale in the industry. The first 5 tools are now in-situ and on track for production in H2 2018, a further 5 tools are scheduled for delivery in Q3. Preparation is underway to call off a further 10 tools within the next 12-18 months.
The establishment of the new foundry is being supported by the Cardiff City Region City Deal, which is funding the construction of the infrastructure. IQE is leasing the building under an 11 year lease, which has a 3 year rent free period and an option to purchase. This support has enabled IQE to focus its own investment on adding new tools, which requires upfront investment in both opex and capex. The lead time to get new tools into production is approximately 9-12 months, from which time a fully utilised tool making VCSELs has a payback of c. 1 year."
In my opinion, that very short payback time represents an excellent return on IQE's capital investments in new tools.
IQE (LON:IQE) "'The capital expenditure of £11.3m reflects cash paid directly to equipment suppliers...Mega Foundry' will house up to 100 tools...first 5 tools are now in-situ...further 5 tools...3 year rent free period".
So I think that means to fill the foundry will cost a further £190m (if they've paid for just 5 tools), or £90m (if they've also paid for the next 5). Unless they cut investment elsewhere I maintain they will need to raise more money.
Their adjusted EBITDA shows £385k for the rent-free period. I think that means over 11 years they have an approximate £4m commitment. Their unadulterated profit figures do reflect the lease costs, but their balance sheet, EBITDA, cashflow and probably tool payback calculations do not.
While the leases for IQE don't overly concern me, it will be interesting to see what happens to some retailers and lease funded roll-outs when IFRS 16 comes in next year and they have to put them on their balance sheets.
Hi leoleo73, you wrote:
"IQE (LON:IQE) "'The capital expenditure of £11.3m reflects cash paid directly to equipment suppliers...Mega Foundry' will house up to 100 tools...first 5 tools are now in-situ...further 5 tools...3 year rent free period".
So I think that means to fill the foundry will cost a further £190m (if they've paid for just 5 tools), or £90m (if they've also paid for the next 5). Unless they cut investment elsewhere I maintain they will need to raise more money."
But IQE don't need to fill the foundry. They will only buy more new tools than they are currently planning to purchase if and when they have signed contracts with the customers of their epiwafer products to justify the capital expenditure.
"IQE (LON:IQE) don't need to fill the foundry"
If they grow photonics 60%pa for 5 years they probably do: 5 machines x 1.6^5 = 50 machines. Then double that because price per unit will have halved in that time (if they are very lucky). And if photonics doesn't grow then they have a massively overvalued low-zero growth business with a lease liability for underutilised buildings.
Hi leoleo73,
If IQE's photonics demand does grow at 60% pa for 5 years, it seems to me that they can use part of the ongoing profit from those tools that have already had their investment paid back within 2 years of purchase to fund invesment in new tools
Indeed and even if you assume the lower end of their growth estimates then I think the two year pack back period on these tools presents a strong case that they have enough cash to fund further investment without coming back to the market or incurring debt.
We pretty much already knew the 2017 results for IQE (LON:IQE) , so these weren't really of much interest to me. What is far more of interest was to understand how the jam tomorrow will taste and how much of it there might be.
Some have expressed disappointment at the outlook, but imho that either implies unrealistic expectations and/or a failure to really appreciate the information that has been given.
In this statement we are presented with some unusually detailed forecasting assumptions at the segment level both for 2018 and for 3-5 years out.
Working these through would suggest the following :
2018 Revenues +10 % to +23% Operating profits +14% to +44%
2019 and beyond Revenues +16% to +30% Operating profits +33% to +48%
Now I have done enough business forecasting over the years to know not to put too much faith in forward projections like that but as a scaling of the opportunity I find that very useful and frankly quite exciting at the top end.
The question of course is does that justify the valuation?
Bad form probably replying to ones own post, but hey ho.
On reflection I was too bamboozled by the sheer luxury of figures to play with at the segment level, but actually when you put them together like this the figures for 2018 are much too wooly
In addition to the segment figures they also say :
That doesn't make sense to me. Even in 2017 with the big H2 "ramp", the split was only 46:54 (revenues)The 10-23% revenue growth together with 40:60 split give a H1 revenue range of £68m (down 3% on previous H1 and down 19% on H2) up to £76m (up 8% on previous H1 but down 10% on H2.)
H2 numbers would then range between £102m & £114m both materially up on H2 last year.
I can certainly buy the idea that H1 will be down on last years H2 given the impact of the iphone X launch, presumably apple's big relevant product launches will also be H2 this year. But, I can't accept the degree of apparent uncertainty in H1 numbers given that we are already 2 1/2 months into H1.
I think the management were stung by some of the accusations in the Shadowfall & Muddy Waters papers and have tried too hard to put lots of data out there, without tieing becoming hostages to fortune by being too definitive.
Personally I think it is the 40:60 split that doesn't make too much sense, I suspect 45:55 might be a more reasonable expectation which would put H1 somewhere in the range £76 - £85m (But of course I've actually not got much basis for picking 45:55).
Hopefully when the next update the market (July for the H1 TU) they give a clear steer on the direction for the Full Year. As ever I expect the analysts will have better guidance in any case, so I look forward to reviewing updated forecasts.
An explanation on the H1/H2 split might be that the guidance on growth rates is based only on "expansion of products currently in production" whereas the 40:60 split takes into account future product launches, given the comment in the same sentence that phasing is "heavily influenced by the timing of OEM new product launches" and comments elsewhere in the statement that customer qualifications are currently ongoing which are expected to lead to production this year.
Is that possibly a hint at upgrades to come later in the year?
You could be right bestace on the rationale of the H1:H2 split, but I just cannot make sense of the specific numbers - implying a fall from H2-17 to H1-18 followed by a 50% increase in H2. It "feels" to me rather like a "from the hip" statement that somehow made it into the official statement.
I am though quite interested in their revenue recognition policy and how much forward visibility they actually have on when revenues and margins will be booked. I got the sense that they left their December trading statement as late as possible in order to have a clear picture of what business would actually fall in to 2017. (I will probably contact them and ask that in the next TU they give a little more visibility on this point)
I don't want to get too excited about such things, but there were several comments that I thought hinted that the top end of the quoted growth range could be exceeded as the market develops.
I would like to think that where they have quoted relatively wide ranges of growth percentages that the bottom end is virtually nailed on, the top end is closer to what they actually expect and that new applications could deliver above the top end of the range. But that is just tentative speculation on my part and even if that is the case I don't think the market will price that in without more material evidence.
Another vote for IQE (LON:IQE) and Cloudcall (LON:CALL) I can't add anything to the comments already made. I am underwhelmed by both
Solid results from Polypipe (LON:PLP) this morning. Adjusted earnings of 27.2p (slightly above consensus of 26.8p) with dividend raised to 11.1p (above 10.9p expectations). They seem to have coped well with raw material price increases and are benefiting from general pipe renewal plans.
Outlook seems broadly positive with house building market remaining strong although possibly some impact from Carillion collapse in non-residential market. Management are on the ball in selling a French subsidiary and closing a factory in Dubai. Interested in any thoughts on this company as it's not too expensive and has some decent quality metrics.
I took one look at the results from Polypipe (LON:PLP) and that was enough to sever my interest in them. They did raise an eyebrow for me a while ago, but with all of the metrics showing only single digit growth now, with margin down slightly and a mixed outlook they are defo not for me. I think a fair price for them is only around 300p... but what do I know; the share price is down today.
I know what you mean. I think that Polypipe (LON:PLP) is fundamentally a decent company with sensible management but it's not about to blow the doors off! I don't think that it's worth 25% less because of the mixed but positive outlook as it's not priced all that highly. However this view is based on the adjusted figures and given the decent gap to the underlying figures I need to take a closer look at the actual adjustments employed.
Any thoughts on Bloomsbury Publishing (LON:BMY) please? Stock is +9.8% this morning.
Unscheduled positive trading update for FY18 (Feb y/e) yesterday. Management expect sales slightly above expectations, profit ‘well ahead’ and cash very strong. FY18 sales are described as ‘excellent’ especially in January/February with lower returns. They mention strong title performance such as Tom Kerridge, Lose Weight for Good helped by the successful TV series; this book has strongly outperformed the previous comparable title, Dopamine Diet.
BMY suggest FY18 net cash at £25m. 2018 P/E 13x.
Bloomsbury Publishing (LON:BMY)
Cash generation exceptionally strong. Given £16.9m at interim stage there is an increase of £8.1m, but allowing for £5m dividends paid in H2 this gives cash generated of £13m+ in H2. This backs up "profits will be well ahead".
Phil
(Given the volumes at the end of yesterday there must have been a leak)
I've almost doubled my holding in Bloomsbury Publishing (LON:BMY) this morning, I think the progress is smashing.
I've dumped my holding in Cloudcall (LON:CALL) and, although this could be the tipping point as someone suggested, they are too small scale for me and taking too long coming to profit.
I am similarly underwhelmed by the IQE (LON:IQE) results (yeah, wafer sales/profit are up but licensing has significantly dropped), and cannot understand why they are priced beyond 100p at the mo.
GYM (LON:GYM) please. Has a lot of similarities to a retail roll out but in a different sector. Cash flows plough back into opening new sites until opportunities for good new sites abate. As fewer new sites open business can be run as a cash cow with high profitability and strong dividend growth.
Inline set of results from GYM (LON:GYM) and further growth in sites and revenues expected. Would be good to get an assessment from Paul (and others).
I also would be keen to have your views on Cloudcall (LON:CALL). I agree with Carcosa's points but am not sure what to make of the fact that the recent additions by Bullhorn appear to use software of competitors to Cloudcall (LON:CALL) (if I have understood correctly)
Putting the treatment of capitalised costs on the same basis as last year shows the GP margin up by 44% but the bottom line improvement of 13%.
Overall I am ok with these results but not as excited as I hoped to be.
Long Cloudcall (LON:CALL).
Housemartin2, ( Cloudcall (LON:CALL) )The implied suggestion is that based on the Force.com platform, it would be a straightforward integration of CloudCall’s plug-in. Connexys has probabaly added c.20% to Bullhorn’s customer base.
Cloudcall (LON:CALL). Ah thanks Carcosa. So my competitor comment is not relevant and rather Force.com is complementary.
Care to comment on Cloudcall (LON:CALL) Final Results today?
Seems to me that they really have stopped making a mess of things and are targeting genuine opportunities after rejigging their software architecture such that there are no more bespoke solutions requiring constant tinkering with.
Bullhorn, their largest customer have themselves recently acquired further companies that Cloudcall could expect to obtain business from. Furthermore, and importantly, the narrative reads that they now have sufficient funding/finance in place that no longer restricts their expansion. Hence this really can be seen as a tipping point, where the attention to growth and future profits is possible.
My morning smallcap tweet:
Lighthouse (LON:LGT), £AD4, Lidco (LON:LID), Pennant International (LON:PEN), Redt Energy (LON:RED), Air Partner (LON:AIR), NAHL (LON:NAH), Judges Scientific (LON:JDG)
Lighthouse Group (LGT) 2 yr renewal of contract with General Federation of Trade Unions. Highlights Lighthouse's capacity to deliver 'holistic financial planning solutions'. Ugh. I thought that word had been retired.
Adept4 (AD4) CFO leaves today, interim CFO starts today. "We thank Ian for his contribution to the business."
LiDCO Group (LID) Argon Medical Devices gives notice to terminate the distribution contract. "Given the timing of the termination and the low margin achieved, this is not expected to have a material impact on LiDCO's results for the year ending 31 January 2019. Furthermore, LiDCO is in discussions with a number of companies about other distribution opportunities to take advantage of its sales reach in the UK, which the company hopes will attract higher margins."
Pennant (PEN) The re-scoping of major UK Contract (as trailed in prelims) increases value by £3.5m to ~£12m. Also statement of intent from a major ME customer worth £10m. Hopes to say more in June.
redT Energy (RED) selected by a consortium of European companies to be the primary energy storage technology provider for a large scale tidal generation project in the UK. Will supply a 0.6MW, 3MWh redT flow machine.
Air Partner (AIR) wins contract for contract for Airfield Wildlife Control Services at 3 RAF bases in Scotland.
NAHL Group (NAH) FY trading in line, EPS ahead of expectations at 21.7p (27p). Consensus is 24.52p though. FY div cut to 15.9p (19.05p). Current trading in line. I hold.
Judges Scientific (JDG) FY rev up 25%, adj EPS up 56% to 131.9p. Results boosted by 'very favourable' exchange rates so this is not the new normal. Current trading in line.
IQE (LON:IQE) Well, I am underwhelmed. OK there is 15% of the business that could double each year (as long as all the cash flow is put into it, 5 machines this year potential for another 95 in Cardiff) and 85% that could grow at up to 5% a year. They had cash of just under £5m, raised £95m and but £46m remains. Someone please check but eps dropped from 2.66p to 2.09p so p/e at 140p/2p is 70. I must have missed something here.
Regards,
Seadoc
IQE (LON:IQE) - This was pretty much as expected, but I agree with Seadoc about cashflow. To look at it another way, they will clearly need to issue more shares to raise funds for investment to support those estimated growth rates. This will dilute those gains for shareholders - you can't take the current P/E and project it falling according to their expected growth rates (which are much less than the headline 40-60% when averaged across the whole business). If the price falls then the shares might look better value, but then the dilution becomes higher.
Looking quickly at the cashflows, they seem to have earned an incremental £7.3m on investments of £28m. Some of those investments will of course have been to sustain existing earnings, and some of the investment will be to support future growth (e.g. buildings to contain tools). While most of this investment will not have accrued a full year of earnings, since investment was similar last year this should balance out. Guessing £6m of investment was to sustain the previous year's earnings and £22m to create the new earnings, provided the investment continues to make returns for 3 years or more it is worthwhile. Technology is fast moving and contracts uncertain, but 3 years seems a reasonable to me and not obvious folly.
Are you the same Seadoc who is telling everyone on the iii board that he is short IQE (LON:IQE) and looking to buy back in at 50p?
Please do share the link to this post John :)
Rob,
Hope it is OK to put on here:
http://www.iii.co.uk/investment/detail/?display=discussion&code=cotn:IQE.L&it=le&action=detail&id=12287281
Seadoc
John,
Yes, I can see no point in using different names. I am short at 110 a penny (last of the big gamblers!). I think I have also previously posted fair price of 60p on SCVR and that I might go back in at that. To be totally transparent, and still trying to update my spreadsheet, maybe 40p? Earnings 2p a share. 15% of business growing like topsie. 85% might grow up to 5%. S&P not doing well so say x20 as PE (generous as 85% might grow 5% a year) 2p x 20 is 40p. I sold out in 30s having bought in teens. What is your view John?
Regards,
Seadoc
Hi Seadoc,
I've been in and out of IQE (LON:IQE), but I'm currently a holder having bought in at 110p, coincidentally just as you were going short!
What do I think? I think it's an enormous opportunity that they have but I'm not convinced that the current management and structure is the right one. I'd be happier if it was run like a conventional business. At the moment I see it as some sort of academia/Welsh politics and development driven thing with the directors doing rather nicely and investors a bit of an annoying distraction.
John,
IQE (LON:IQE) Exactly. Not sure if it was on here, iii or even lse (use same name on all) that I expressed views about the joint ventures. The directors are doing well, all profits ever made have been paid to them. There has been no dividend. I have "finished" my spreadsheet. I was right to sell just under 40p. Not sure if Paul or Graham is flying the spaceship today but would be interested in a professional view. 20yrs ago IQE (LON:IQE) shut the old plant in Wales and drew a huge wad of cash (sp to 800p) and set up in Singapore, major tumble to teens, that when I bought. FWIW I bought Conviviality (LON:CVR) with proceeds of sale IQE (LON:IQE) , more than doubled my money and got same feelings, sold out around £3, felt I had made a mistake as it went up and up but the money is in now the bank (actually in Norcros (LON:NXR) ).
I am very lucky, but the more I do research (mostly listening to Paul and Graham), the luckier I get.
Regards,
Seadoc
With the share based payments it relates to accounting treatment on the Options if I understand correctly. This was to be expected given the very large share price movement over the course of the financial year.
Assuming that does not recur and based on removal of finance costs of £2m (since now there is no debt) and taking their midpoint of growth metrics I expect an EPS of 4.5-5p in this year with upside potential.
I see photonics as a growth story for the next 5+ years and expect 20%+ YoY growth at IQE for foreseeable future. I think people fundamentally misunderstand this about IQE and assume it is just an Apple distributor.
A multiple of 25-30* earnings is not abnormal for this type of sector with strong IP moat and large market share of 90%.
So for me fair value is north of 120p and up to 200p, so probably about right at the moment. Personally I think they get taken out circa 180p
IQE (LON:IQE)
I think you are right David, the options were probably granted at a much lower share-price than they vested.But there is an aspect to this that puzzles me. The gross value of the share based payments is given as £7.5m but with an associated tax credit of £5,4m (about 72%) so a net impact of only £2.1m.
In the prior year the total figure was £2.9m with no tax adjustment.
This implies to me (although I could be leaping to the wrong conclusion) that the "capital gain" has been written off against tax - does anyone understand this?
Re IQE (LON:IQE) .....implies "capital gain" has been written off against tax - does anyone understand this?
No, but it sounds a bloody nice trick - wish I knew how to do it!
Why would photonics be a growth story for only the next 5+ years (- genuine question)? The microchip has only been around for about 60 years, and micro-electronics are still developing and growing. Surely, photonics will eventually replace most electronics, no?, but it'll take a lot longer than five or so years - probably a lot more than 50 years I should think, especially in consort with quantum computing.
No position in IQE (LON:IQE) , no intention of taking one anytime soon, and not an endorsement.
absolutely - I think Photonics is a much longer term growth story and is really only in its infancy. What I meant (and could probably have articulated better) is that I believe there is good 5 year visibility of strong double digit compound growth. The company reckons on 40-60% in photonics and 10% elsewhere. Extrapolating that means they expect to reach $500m sales in 5 years at 20% operating profit margin = circa $100m. Translates to 14p EPS.
A current year PE of sub 30 for IQE (LON:IQE) isn't expensive for that, especially for such high barriers to entry and a 90% market share. I understand a lot of IQEs contracts in photonics space are multi-year so that also underpins visibility.
It has had a good run and I understand why there is a debate on value. I think it is circa fair value at 140p but has upside over a 5 year window to 300p. I don't think we will ever see that as I am firmly in the camp that someone will take it out and I'm expecting that to be no higher than 200p alas.
I am long - took some profits along the way - relatively happy with todays results but happy to hold here
Fair enough. I think it's worth people understanding that photonics are not niche: photonics will eventually replace [micro]electronics, itself an industry that is still growing and developing after 60 years. That is not the same as me saying go buy IQE (LON:IQE) . Frankly I have not looked into it anywhere like in enough detail, especially given its JV/subsidiary structure - I would much prefer that its productive assets were directly held, but there we go, such arrangements are not uncommon with nascent technologies. I wouldn't rely on high barriers to entry (unless you are sure they have technology no-one else will be able to match or exceed) - there is a lot of research in the world on photonics, huge players in this and an absolute avalanche of money that will flood into this new industry - though there is something to be said for first-mover advantage.
The long-term contracts sound interesting, since electronics (/ photonics) are always highly cyclical - even if the cyclicality is superimposed on a long-term growth curve. Nor do I understand chatter about epiwafers being novel, since seeded, epitaxial* growth is the basis of single-crystal silicon (or your semi-conductor of choice) wafer production, though perhaps I've misapprehended the point, since I've only approached the debate on IQE (LON:IQE) in passing rather than in great depth.
*(Epitaxial growth just means aligned growth of the same crystal planes/orientations across boundaries - such as aligned growth nucleated from a seed crystal, i.e. the new single-crystal silicon bar (from which wafers are cut) is basically a larger clone of the small starter crystal, if anyone is interested - probably only me.)
Thanks - given your technical knowledge in this space I am surprised you haven't spent more time researching this company, I would have thought it right up your street.
Management address the barriers to entry and the IP that protects their products (at least short to medium term). I agree with you that there will be the proverbial avalanche of money into the industry, which is why I feel IQE will get taken out by a larger player at well below my 5 year target prices. If you can buy 90% market share with long term contracts and ready made manufacturing facilities and continue to invest to innovate and protect your position that's far easier than R&D with no guarantee of success. Natural proviso of course that the price is right but 180-200p doesn't feel problematic.
Well, I might take a look at IQE (LON:IQE) David, starting with barriers to entry. Most of the cash funds I was sitting on have been spent. I'm wary of buying wafer producers because the industry is so cyclical and, let's be honest, producers of hardware are rarely the real winners in exploiting new technology - doubly so with wafers, which are just substrates - commodity items - even if photonics substrates will initially be regarded as somewhat fancy. The chipset designers benefit from strong branding and IP-led asset-light business models, not the producers of the substrates in which their clever designs are realised. Now, those companies that are the first to exploit and monitise the new computing power of photonic quantum computers could really clear up.
I could well imagine IQE being bought out by a big player if they are very good at what they do. Else they will simply be squeezed out by much larger/cheaper/better competing production. They might just be squeezed out by the Chinese/South Koreans or Singaporeans anyway? I'll take a little look but I'm getting fed up with having way more ideas than cash to spend on them and IQE (LON:IQE) seemed a long way from being genuinely profitable when I had a look in passing. I have foolishly lost too much money on jam tomorrow stuff not to wait for real profits to show up. My foolish naivety is a shame perhaps since I lose some opportunities a more canny investor might catch. Anyway, I don't mean to dampen your enthusiasm if you have done your research, drawn a correct conclusion and patiently got stuck in where others fear to tread - I hope you make a packet.
well - I for one would be very interested in your take if you do decide to spend a bit of time on it. I think IQE has positioned itself well and is rather more than a straight wafer producer but a new set of technical eyes is always welcome to revisit the investment case.
For transparency I bought IQE at circa 23p and took some profits at 155p so I'm clearly pretty happy but like you have also been burnt before on jam tomorrow stuff : which of us hasn't!!!
There are also a couple of aggressive hedge funds shorting this stock so I am conscious that any set of accounts will be attacked with the same level of breathless sensationalism as before. That can be short term detrimental but as long as the business case really does hold water will also lead to a big short squeeze higher at some point.
Well okay, I hope IQE (LON:IQE) are more than a wafer producer of a slightly novel semi-conductor (and probably one amongst multiple alternatives). I don't know what else, if anything, they do, and I would view wafer production as the least exciting and lowest profit-potential technology 'stream' in realising the potential of photonics. Even the IP around creating the photonics micro-components on their semi-conductor substrates (many of which I understand will need to be novel relative to silicon-wafer micro-electronics - based on reading, way back, of research that must be at least 15 years' old now) are surely more exciting, novel and profit-worthy than that of wafer production, and all of which I would expect to pale in relation to the profits of those exploiting the new computers made possible by such technologies to their full potential, or even to the profits of those selling the new chipset designs, as I've said.
If I come to any other view once I've had a bit of a look at IQE (LON:IQE) I'll drop you a line, for what it's worth, though there might already be much more informed views amongst Stockopedia's scientifically-literate readers on what IQE (LON:IQE) do, what their novel IP is, and how difficult it is to match or best, and what they have that will prevent wafers being simply commodity items in an industry likely to be flooded by excess production amidst irrational over-enthusiasm. We would both be glad to hear from them. (Just my off-the-cuff views - other views are possible, so please don't be offended!)
:) not remotely offended. I am genuinely interested in other views to help me constantly challenge my own. I don't just need confirmation, I'm already naturally biased.......
On a quick first look at the IQE (LON:IQE) website and accounts, I'd call out a few positives: they are (according to themselves, and I've no reason to doubt it) the clear global leader in their field; they are involved in micro-component and micro-circuit fabrication (far more promising than just wafer production in my view, as I've said), including the Vertical Cavity Surface Emitting Lasers (VCSELs) that others have mentioned, and their technology is protected by 180 patents - that's a lot of IP protection if they know how to write good patents (one hopes they've learnt along the way); they are generating more cash from operations than I'd realised (though I haven't looked at the implications of their JV structure beyond some fairly scathing comments I've read previously on SCVR in response to Matt Earl's ditty, and whose detail certainly escape me now).
If memory serves, a couple of readers here have worked/do work in the industry. Their view on how effectively or otherwise those micro-fabrication patents might ring-fence market share and preserve margins on photonics component manufacture could be invaluable. Likewise, tracking down any relevant trade publications could shed light on that crucial point: let's hear from the industry insiders please!
I would guess they only like to predict up to 5 years ahead.
Being a holder, I have also been reviewing IQE (LON:IQE) this morning. On the surface, and using adjusted figures, they have slightly exceeded expectations (adjusted PBT: 24.3m vs. expected 24.1m). But it's the adjustments that most concern me. 9.4m in total adjustments, which bring non-adjusted PBT back down to 14.9m (a 19% reduction on prior year of 18.4m). These adjustments include a whopping 7.5m in Share Based Payments (SBPs), which however you read into SBPs they are generally a form of Director's remuneration and therefore are a real cost to the business.
@Seadoc your concerns regarding only £46m of the £95m fundraising remaining I feel are less worrying, since they have cleared their previous bank borrowings of £42m.
The outlook sounds quite good, with the most exciting prospect being their new Mega Foundry in Newport, South Wales.
There is certainly a draw for many to investing in a UK manufacturer who continues to develop innovative technology. However, the proof will be in the wafer pudding - the valuation is high and they therefore must meet future ambitious targets to justify those generous share based payments.
Decision: Sold half of my holding at 141p and remaining sceptical about the rest.